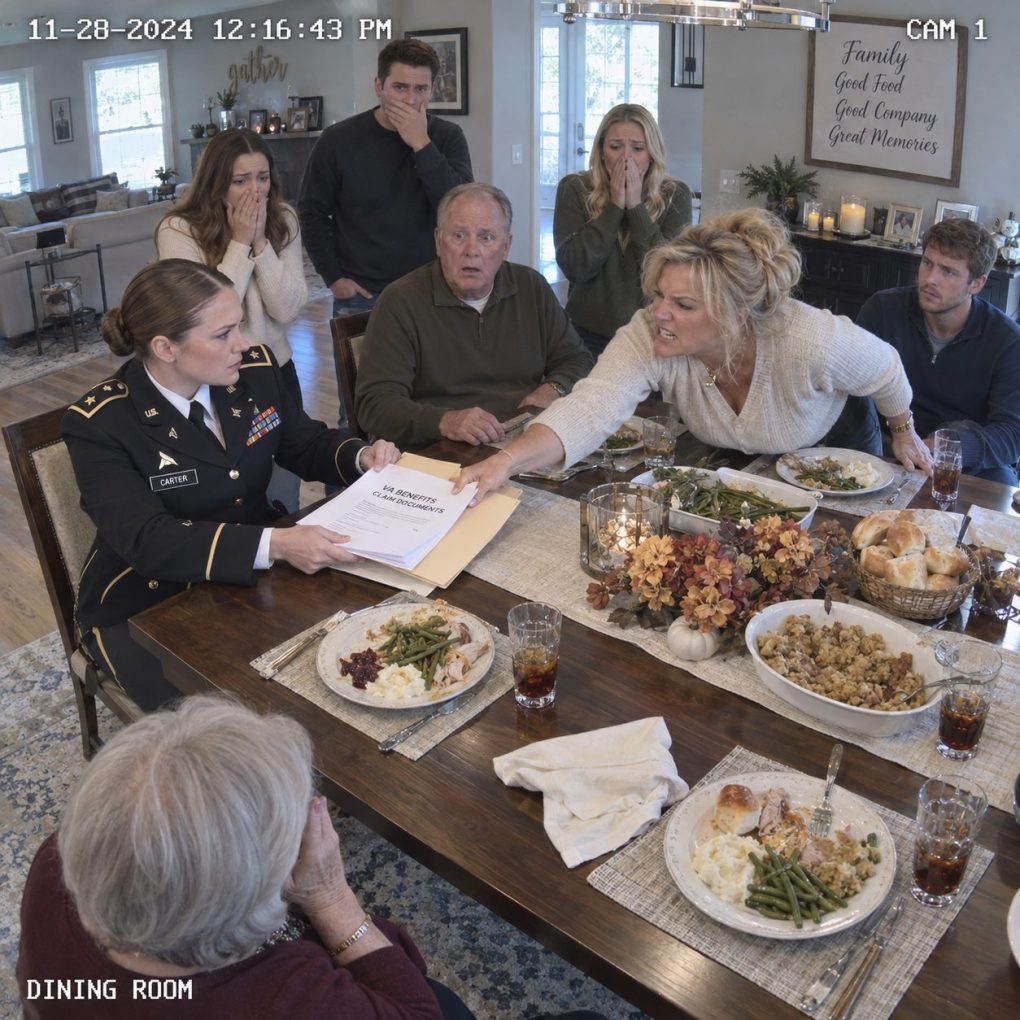
“Your salary should help this family,” my father’s wife said, reaching across the dinner table for the paperwork beside my plate.
I pulled it back before she could touch it.
“Tell your wife my Army money belongs to me—not to her.”
The room went completely silent.
My father, Thomas, froze with his fork halfway to his mouth.
His wife, Denise, stared at me as if I had broken some sacred rule.
For three years, she had acted as though my paycheck belonged to the household simply because I was the unmarried daughter who “had fewer responsibilities.”
Never mind that I was thirty-two.
Never mind that I had served twelve years in the Army.
Never mind that I paid my own mortgage, insurance, student loans, and supported a younger soldier’s widow through a private fund I had helped establish.
To Denise, none of that counted.
She wanted access.
The papers beside my plate were beneficiary forms for a military savings account and updated estate documents I had brought because Dad had asked whether he was still listed as an emergency contact.
Denise saw numbers.
That was enough.
“You have no children,” she said. “Your father has bills. This family has bills.”
I looked at Dad.
He said nothing.
That disappointed me more than her greed.
Denise leaned back and crossed her arms.
“I’m just saying, if you’re making that kind of money, it’s selfish to hoard it.”
I almost laughed.
“That kind of money?”
She had no idea what I made.
But she thought she did.
Because six months earlier, Dad had mentioned that I received base pay, housing allowance, and additional compensation tied to my assignment.
Denise apparently translated that into unlimited cash.
My stepbrother, Kyle, cleared his throat.
“Maybe everyone should calm down.”
I ignored him.
Then I looked at Denise.
“There’s an account you forgot I can see.”
Her expression changed.
Slightly.
Dad frowned.
“What account?”
She answered too quickly.
“She doesn’t know what she’s talking about.”
That confirmed it.
Two weeks earlier, I had logged into an old joint banking profile Dad and I had used years ago when I helped manage his finances after surgery.
I expected the account to be dormant.
Instead, I found regular transfers.
Large ones.
From Dad’s retirement savings.
Into an account ending in 4481.
Denise’s private account.
At first, I assumed Dad knew.
Then I noticed the transfer descriptions.
Household reimbursement.
Medical expense.
Property tax.
Except Dad’s medical bills had been covered.
The property taxes came from another account.
And some of the “household” transfers happened while Denise was in Florida shopping for a new SUV.
I placed my phone on the table.
“I can see every transfer from Dad’s retirement account.”
Denise went pale.
Dad looked at her.
“What transfers?”
Nobody moved.
I opened the banking app.
Then I turned the screen toward him.
The total withdrawn over fourteen months was $86,400.
Dad stared at the number.
Then at his wife.
And finally asked the question she had clearly hoped he would never ask.
“Where did my money go?”
Denise’s first explanation was that Dad had authorized everything. She said the transfers covered groceries, home repairs, insurance, and “all the invisible expenses nobody appreciates.” Dad listened without interrupting, then asked her to show him the receipts.
She had none.
That was when the dinner ended.
I took Dad into his study and pulled up the account history. We went through every transaction line by line. Some were ordinary. Others made no sense.
There were transfers on dates Dad had been hospitalized. Several matched credit-card payments Denise had made to luxury retailers. One was followed the same day by a $12,000 payment to a dealership in her name.
Dad looked physically smaller by the time we finished.
“I gave her access because I trusted her.”
I did not say what I was thinking.
Trust does not survive well when someone treats it like permission.
The next morning, Dad called his financial adviser and attorney. They froze discretionary access to his retirement accounts and reviewed the documents Denise had been using.
What they found was worse than careless spending.
Dad had signed a limited financial authorization after his surgery two years earlier. It allowed Denise to pay certain household bills while he recovered.
She had continued using that authority long after he returned to managing his own affairs.
Several transfers fell outside the stated purpose.
Dad’s attorney advised him to document everything before confronting her again.
Denise, meanwhile, called me fourteen times.
I answered once.
“You had no right to interfere in our marriage.”
“I didn’t.”
“You turned him against me.”
“I showed him his own bank statements.”
Silence.
Then she tried a different approach.
“You don’t understand how expensive it is taking care of him.”
That sentence made something in me go cold.
Dad was not helpless.
He cooked.
He drove.
He handled appointments.
He had simply trusted the wrong person with access.
Two days later, Kyle called me.
He sounded embarrassed.
“Did Mom take money from Dad?”
“I don’t know what she intends to call it.”
He was quiet.
Then he admitted Denise had given him $20,000 six months earlier for a business venture.
She told him it came from an inheritance.
There had been no inheritance.
That money had come from Dad.
Kyle offered to return it immediately.
Dad told him to wait until the lawyers sorted everything out.
For the first time, I saw how financial secrecy spreads damage beyond the person who starts it.
By the end of the week, the review identified more than $110,000 in questionable transfers over two years.
Not every dollar was necessarily improper.
Some had paid legitimate household costs.
But enough appeared personal that Dad’s attorney recommended formal action.
Denise stopped arguing about my Army salary.
Suddenly, nobody cared what I earned.
Dad filed to revoke every financial authority she held.
Then he made one more decision.
He asked her to leave the house while the accounts were investigated.
That night, she stood in the foyer with two suitcases and looked at me.
“This is what you wanted.”
I shook my head.
“No. I wanted you to stop reaching for money that wasn’t yours.”
Dad stood behind me.
And for once, he did not stay silent.
The investigation never turned into the dramatic criminal case Denise claimed I was trying to create. Dad’s attorney separated what could be documented clearly from what was simply poor financial management.
Some transfers were legitimate.
Others were not.
Denise eventually admitted she had used Dad’s accounts for personal purchases because she believed marriage entitled her to the money.
That belief became the center of their divorce.
Dad did not pursue every possible civil claim. He chose a negotiated settlement requiring Denise to repay a substantial portion of the disputed funds and surrender any claim to several retirement assets.
Kyle returned the $20,000 voluntarily.
That mattered to Dad.
He had been afraid the betrayal extended to everyone.
It did not.
My relationship with him changed too.
A month after Denise moved out, Dad asked me to dinner.
No paperwork.
No bank statements.
Just food.
Halfway through, he said, “I should have stopped her when she talked about your salary.”
I looked at him.
He continued.
“I thought staying quiet would keep the peace.”
“That usually means someone else pays for it.”
He nodded.
“I know.”
Then he apologized.
Not for losing money.
For treating my independence like something that needed to be justified.
That apology was harder for him than anything involving lawyers.
Months later, I deployed again.
Before leaving, I updated my beneficiaries and financial instructions.
Dad asked no questions about the amounts.
He only said, “Make sure everything goes where you want it to.”
That was growth.
Denise tried to repair things once.
She sent me a long email explaining that she had grown up believing family money should always be shared.
I believed part of that.
But sharing requires consent.
Access is not ownership.
I never answered.
Dad sold the house the following year and moved into a smaller place closer to my brother.
He said the old house felt too full of arguments.
He also hired an independent financial manager.
“No more family banking,” he joked.
I agreed.
The strangest part was how little the original argument mattered in the end.
Denise had reached for my Army paperwork because she believed my income should serve everyone else.
Instead, that moment exposed how casually she had been using money that belonged to someone else.
My salary was never the real issue.
Entitlement was.
Years later, at a family dinner, Kyle’s daughter asked what I did in the Army.
Before I could answer, Dad smiled and said, “Something she worked very hard for.”
No comment about salary.
No joke about medals.
No suggestion that success created debt to relatives.
Just respect.
I remembered that first dinner.
The papers.
The silence.
The account ending in 4481.
And the lesson became obvious.
Family can ask for help.
Family can accept generosity.
But family does not get to turn love into financial access and call the difference selfishness.
Money given freely can strengthen relationships.
Money taken through pressure, guilt, or secrecy destroys them.
That night, pulling the paperwork away from Denise felt like a small act.
It was not.
Sometimes one boundary reveals every place people were counting on you not having one.