“Don’t worry about the bill. Natalie pays for everything.” My husband, Eric, said it loudly enough for his entire family to hear as we stood in the lobby of a ski resort outside Aspen on Christmas Eve. His brother laughed and raised his glass toward me. “There she is—our family bank account.”
Everyone laughed except me. Eric’s mother, Diane, had already booked three spa treatments to my room, his sister Madison had ordered designer ski gear from the resort boutique, and his brother Kyle had upgraded his family to a two-bedroom suite. Eric had promised them all that I would cover the Christmas trip without asking me once.
I owned a medical staffing company in Denver and earned considerably more than Eric, who worked in commercial insurance. For six years, I had paid most of our mortgage, vacations, and emergency expenses because I believed marriage meant helping each other. Somewhere along the way, Eric decided helping him meant financing everyone related to him.
The first warning came two weeks earlier when I saw a $9,840 resort deposit on my personal American Express card. Eric was an authorized user for household emergencies. When I confronted him, he smiled and said, “It’s Christmas, Nat. Don’t embarrass me in front of my family.”
Then I discovered restaurant reservations, ski rentals, transportation, and shopping charges totaling nearly $23,000. Eric had also told Diane she could buy Christmas gifts with another card linked to my account. I quietly called both card companies and removed every authorized user except myself.
I did not cancel anything already paid. I simply froze access to my personal credit and moved my business income into an account Eric had never been authorized to use. Then I packed a small suitcase and drove to Aspen with everyone else as if nothing had changed.
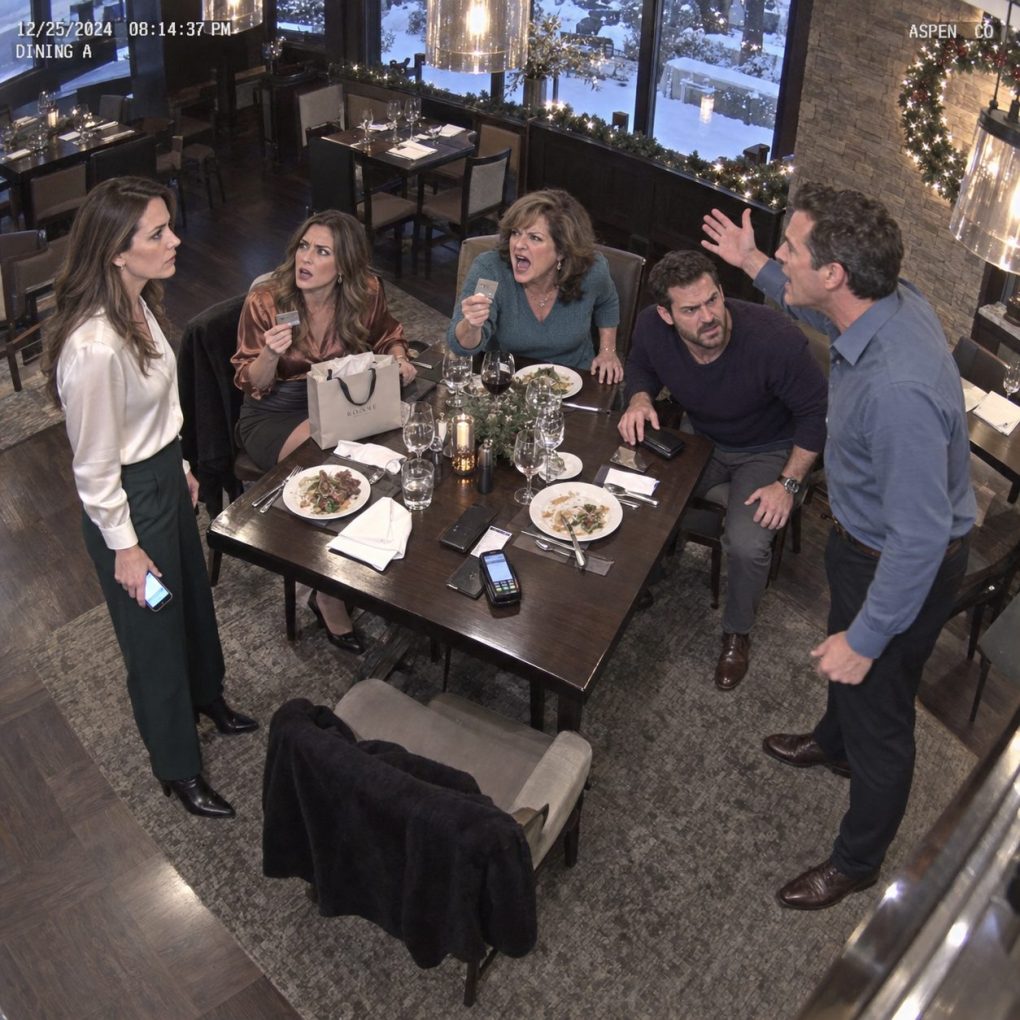
By Christmas Eve, their confidence was almost impressive. Kyle ordered a $320 bottle of champagne at dinner. Madison told the waiter to put the entire table on “Natalie’s account,” while Diane joked that marrying me was the smartest financial decision Eric had ever made.
I finished my steak, placed my napkin beside the plate, and stood. Eric frowned. “Where are you going?” I looked around the table and said, “Home.”
He followed me into the lobby, whispering angrily that I was humiliating him. I handed him his wallet and told him everything already charged to me was paid, but from that moment forward, every new expense belonged to whoever ordered it. His face changed when he understood.
Ten minutes later, Madison tried to buy a $1,700 coat from the boutique. Her authorized card was declined. Then Kyle’s card failed at the restaurant, Diane’s failed at the spa desk, and Eric’s face went white as his phone lit up with messages: DECLINED. DECLINED. DECLINED.
Eric called before I reached the highway. I let the first three calls ring out, then answered through the car speakers. He did not ask whether I was safe driving through the snow; he shouted, “Turn the cards back on right now.”
I told him there was nothing to turn back on. The cards were mine, the accounts were mine, and I had revoked authorization legally with the issuers. Eric said his family was standing in the lobby being treated “like criminals” because several charges had failed.
“They’re being treated like customers who need to pay,” I said. Eric went silent for a second, then accused me of deliberately setting him up. I reminded him that he had spent weeks promising my money to people without my permission.
The resort manager eventually required Eric’s family to provide valid cards for incidental deposits. Their rooms had already been prepaid through Christmas morning, so nobody was thrown into the snow. But the upgrades, spa appointments, expensive dinner extras, boutique purchases, and additional activities were no longer my responsibility.
That distinction did not matter to Diane. She sent me a message saying, “A wife should never publicly shame her husband.” Five minutes later, Madison wrote that I had ruined Christmas because her children had expected new ski equipment.
I pulled into a gas station near Glenwood Springs and read the messages beneath fluorescent lights. My hands were shaking, but not from guilt. For the first time, I could see how thoroughly Eric had trained everyone to treat my income as community property while treating my opinions as inconvenient.
When I reached Denver after midnight, I went directly to our home office. I downloaded eighteen months of statements and started highlighting charges I had never approved. There were football tickets for Kyle, furniture for Diane, Madison’s car repair, family dinners I had never attended, and more than $41,000 in transfers and purchases.
The next morning, Christmas Day, Eric finally came home alone. He dropped his suitcase inside the doorway and demanded to know whether I planned to apologize. I slid a folder across the kitchen counter instead.
He flipped through the statements, growing quieter with every page. I asked whether he could explain why his mother’s new refrigerator had been charged to my card or why Kyle’s overdue property tax payment had come from our joint savings. Eric said, “They needed help.”
“So did you ask me?” I said. He looked away. That was when I realized our argument was no longer about Christmas Eve; it was about six years of Eric deciding that access to me meant access to everything I had earned.
I spent the week between Christmas and New Year’s separating what was legally mine from what we actually shared. I did not empty joint accounts or hide marital funds. I simply redirected my future business distributions, changed passwords on my personal accounts, and met with an attorney before making any larger financial decisions.
Eric reacted as though I had betrayed him. He told his family I was becoming “obsessed with money,” and Diane called twice to explain that successful people had a responsibility to help relatives. I asked whether that responsibility included being consulted before spending tens of thousands of dollars.
Diane hung up on me. Madison blocked me on social media after posting that some people “forget who family is when they get successful.” Kyle never contacted me directly, although he quietly repaid $3,400 after my attorney requested documentation of several transfers.
Eric resisted counseling because he insisted our only problem was my reaction. When he finally agreed to one session, the therapist asked him why he had told his relatives I would pay without discussing it with me. Eric answered, “Because she always could.”
The room became very quiet. The therapist asked him whether being able to afford something meant I had consented to buy it. Eric stared at the floor for so long that I already knew his answer.
Two weeks later, I learned something worse. Eric had promised Diane that I would help with a $60,000 down payment on a retirement condo in Arizona. He had never mentioned it to me, yet Diane had already placed a refundable deposit on a unit because she believed the money was guaranteed.
That was the moment I stopped trying to repair the marriage. I filed for divorce in February after my attorney reviewed our finances. I was not leaving because Eric’s family enjoyed my money; I was leaving because my husband believed my boundaries disappeared whenever he found my generosity useful.
The divorce was not dramatic in the way Christmas Eve had been. There were spreadsheets, appraisals, attorneys, and uncomfortable negotiations about property we had accumulated together. My separate business interests remained carefully documented, and our marital assets were addressed through the legal process.
Months later, Madison emailed me unexpectedly. She did not apologize, but she admitted Eric had always told them I had personally approved every gift and payment. She wrote, “We thought you wanted to do all of it.” I believed that part.
The following Christmas Eve, I spent dinner with three friends at my house in Denver. Everyone brought something, nobody handed me the bill, and nobody called me their bank account. When we raised our glasses, I realized the lesson had never been about refusing to help people—it was about finally understanding that generosity without consent is not generosity at all.