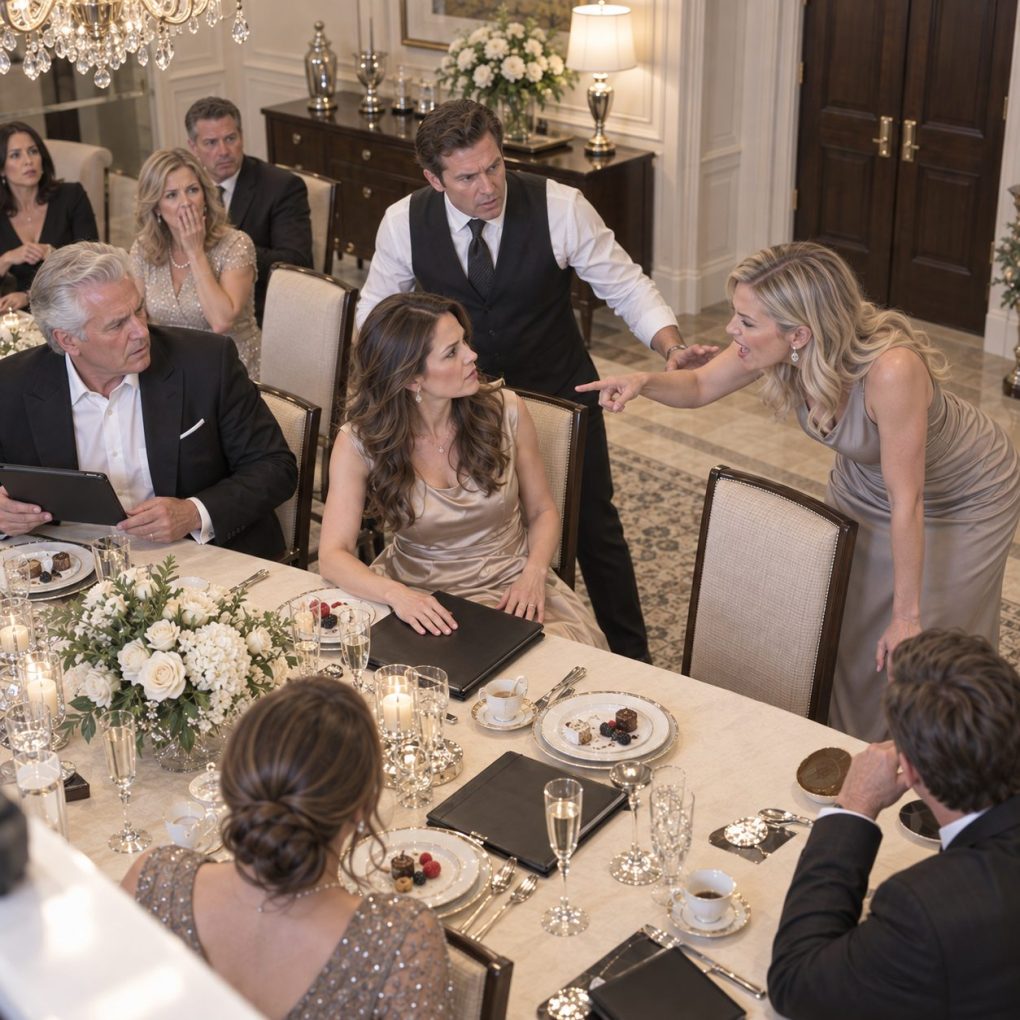
The founder of Calder Systems told me replacing me with his daughter would take six weeks. His daughter, Vanessa, apparently thought she could shorten that timeline to one evening. At our annual leadership dinner in Chicago, she raised her glass in front of forty executives and announced that some employees needed to recognize when “their era was over.”
Everyone knew she meant me.
I had served as chief operating officer for eleven years, beginning when Calder Systems had twenty-eight employees. Now we had more than nine hundred. Vanessa had joined the company eighteen months earlier with the title of senior vice president and the confidence of someone who believed inheritance and experience were interchangeable.
Her father, Martin Calder, smiled while she spoke.
Then Vanessa turned toward me. “Claire has agreed to help with my transition before pursuing new opportunities.”
“I haven’t agreed to that.”
The table went silent.
Martin leaned closer and quietly said, “We discussed six weeks.”
“No. You informed me you wanted six weeks.”
Vanessa laughed. “Claire, don’t make this embarrassing. You’re an employee.”
That sentence told me neither of them had reviewed the company’s original capitalization documents.
Seventeen years earlier, when Calder Systems nearly ran out of money, I had invested $180,000 of my savings alongside three early investors. In return, I received a small block of Class B voting shares carrying protections against certain changes in company control.
My ownership was not enormous.
The rights attached to it were.
The following morning, Martin intended to call a special board meeting to appoint Vanessa president and transfer several executive powers to a family-controlled management entity.
There was one problem.
Section 8.4 of the original shareholder agreement required approval from seventy-five percent of protected Class B voting interests before any transaction transferring substantial management authority to a related party.
Martin had apparently forgotten it existed.
I had not.
I opened my briefcase and placed a copy of the agreement beside my untouched dinner plate.
Vanessa’s smile disappeared.
Martin read the highlighted paragraph twice.
Then he looked at me.
“How many of those shares do you still own?”
“All of them.”
His attorney, seated three chairs away, suddenly stopped eating.
I closed the folder.
“You wanted six weeks to replace me.”
I looked directly at Vanessa.
“Tomorrow morning, you’re going to discover why trying to do it overnight just became much more expensive.”
By 8:00 the next morning, Calder Systems’ outside counsel had confirmed that Section 8.4 remained valid. Nobody had removed it during later financing rounds because the protected Class B shares had never been converted.
Martin owned more economic equity than I did.
That did not give him every vote he wanted.
Two other early investors still held protected shares. Together, the three of us controlled enough Class B voting power to prevent the proposed related-party management transfer.
I had not contacted either investor before dinner.
I did not need a conspiracy.
Martin had simply proposed a transaction requiring approval he did not have.
At 9:30, the board meeting began.
Vanessa arrived carrying a presentation labeled LEADERSHIP TRANSITION. The first slide named her president effective immediately.
Outside counsel interrupted before she reached slide two.
He explained that the board could consider changes to ordinary executive appointments, but transferring the powers described in Vanessa’s plan to a family-controlled management company triggered contractual protections under the shareholder agreement.
Vanessa looked at her father.
“You said you controlled the company.”
Martin answered carefully. “I control the largest block.”
“That isn’t the same thing,” I said.
Then came the expensive part.
My employment agreement contained a change-of-control provision negotiated years earlier after private-equity investors considered buying Calder Systems. If my authority was materially reduced through certain related-party restructuring without cause, I could resign for good reason and receive two years of salary, my earned incentive compensation, continued benefits, and accelerated vesting of specified equity awards.
Martin had remembered my salary.
He had forgotten the rest.
The potential package exceeded $1.6 million.
I was not threatening to trigger it merely because Vanessa insulted me. My attorney had already warned that contractual rights depended on exactly what the company implemented.
But Martin’s proposed restructuring came dangerously close to the language in my agreement.
The board postponed the transition.
Vanessa exploded after the meeting. She accused me of holding her family’s company hostage.
I reminded her that seventeen years earlier, when payroll was uncertain, Martin had asked me to risk my own savings because he said early employees deserved to become owners.
I had believed him.
Apparently, he had too.
He had simply forgotten that ownership still mattered once the company became valuable.
For the next month, negotiations replaced speeches.
Martin could still change senior leadership through lawful corporate procedures. My shares did not make me untouchable, and I never claimed they did.
What they prevented was the specific shortcut he had chosen.
The board eventually hired independent counsel to review the proposed succession plan. That review found another problem: Vanessa’s management entity would have received substantial fees while taking over functions already performed inside Calder Systems.
Several independent directors wanted competitive proposals before approving anything.
Vanessa blamed me.
I voted against her proposal, but I was only one part of the resistance. Once directors examined the transaction without Martin presenting it as a simple promotion, they began asking their own questions.
That was exactly what corporate governance was supposed to accomplish.
Martin eventually abandoned the management-company structure.
He still wanted Vanessa to become president someday, but the board required a development plan instead of immediate succession. She would rotate through operations, finance, and client management before another vote.
I received a different proposal.
The company offered to buy my protected shares as part of a broader recapitalization.
The first offer undervalued them.
I rejected it.
The second recognized not merely their percentage ownership but the contractual protections attached to them. After independent valuation and weeks of negotiation, we reached an agreement.
I also negotiated my departure.
I remained COO for four months while an external search firm found a successor. My exit package honored the compensation and equity rights already contained in my contract.
There was no dramatic takeover.
I did not steal Martin’s company or throw Vanessa out of the building.
I simply refused to surrender rights I had purchased when those rights were worth far less than they eventually became.
At my final board dinner, Martin sat beside me.
He admitted he genuinely had forgotten Section 8.4.
“I never thought those old shares would matter again,” he said.
“That’s why contracts survive memory,” I answered.
Vanessa did not attend.
Six months later, I joined another technology company as an operating adviser and invested in two startups.
I kept one framed document in my home office: not my Calder resignation letter, but the original certificate for those Class B shares.
Years earlier, Martin had given them to me because the company desperately needed my money and commitment.
Years later, he discovered that loyalty written into a contract was not something a founder could erase at dinner.
He thought replacing an employee would take six weeks.
His expensive mistake was forgetting he had made me an owner seventeen years before.