After we moved into our new home, I went to the bank expecting nothing more than a simple address update on my husband’s account. Then the banker suddenly stopped typing, turned the screen toward me, and said, “Ma’am… I think you need to see this,” and one glance was enough to make my stomach drop.

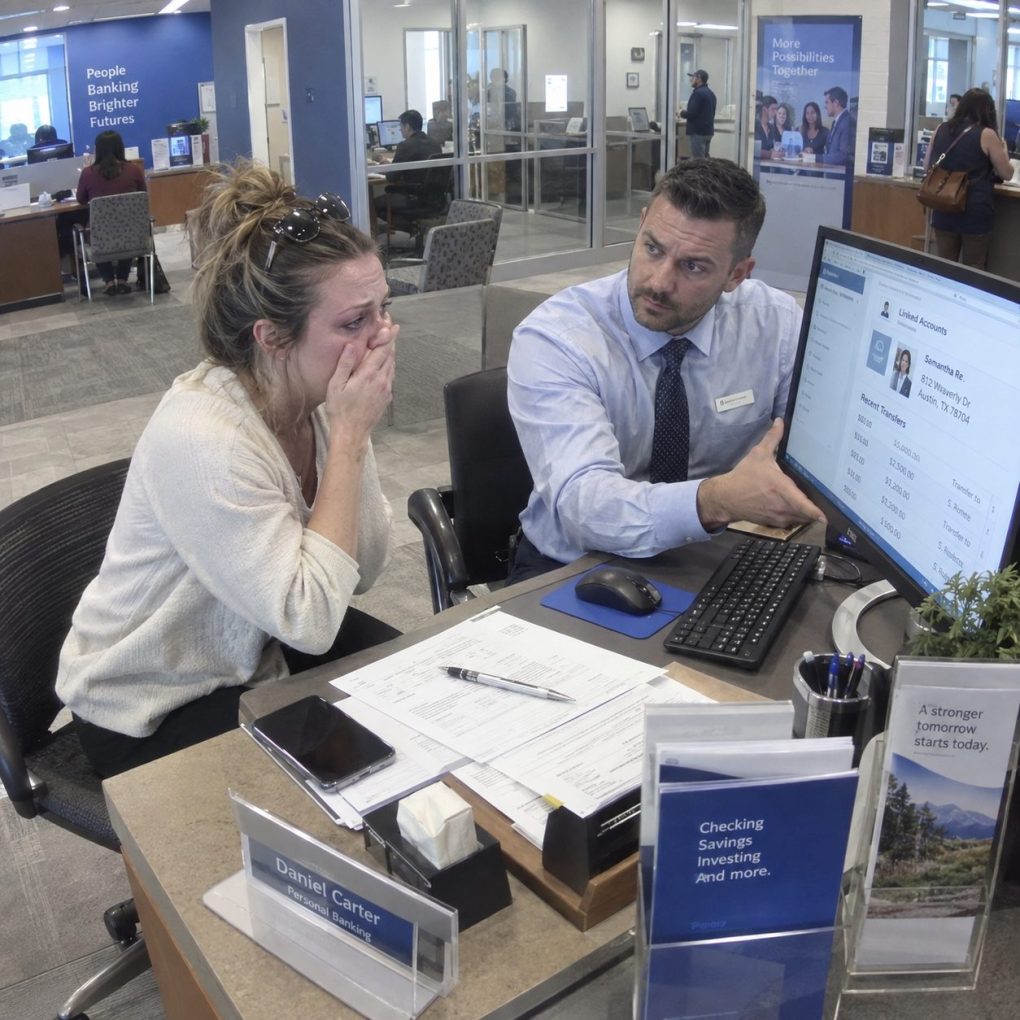
Three days after we moved into our new house outside Denver, I stopped at our bank to update the mailing address on the checking account my husband, Aaron, had opened years earlier and later added me to as a joint owner. The banker, Marcus Lee, checked my driver’s license, typed for less than a minute, and then suddenly stopped with both hands hovering over the keyboard.

“Mrs. Collins,” he said carefully, “before I change anything, can I confirm that you recognize this account?”

He turned the monitor slightly toward me.

Beneath our checking account was another product attached to my customer profile: a home-equity line of credit for $185,000, opened eleven months earlier using my name, Social Security number, and our previous house as collateral. I stared at the balance, then at a scanned signature that looked enough like mine to fool someone who had never watched me write it.

I could barely breathe.

“I never signed that.”

Marcus immediately stopped touching the keyboard.

“Are you certain?”

“Please,” I whispered. “Close it.”

He turned the screen away, but the numbers were already burned into my mind.

Marcus called the bank’s fraud department while I sat frozen beside his desk, and within minutes another employee joined us and explained that because the loan was attached to my identity, I had the right to dispute it. They printed only the documents I was legally entitled to receive, and one page showed that almost the entire loan had been transferred within forty-eight hours to an account belonging to Willow Creek Properties LLC.

I knew that name.

Aaron had mentioned Willow Creek several times, describing it as a real-estate investment owned by one of his business partners. He had even blamed our delayed kitchen renovation on money he had supposedly invested in that company.

My phone rang while I was still sitting in the bank.

Aaron.

I stared at his name until Marcus quietly said, “You don’t have to answer that here.”

I answered anyway.

“Hey,” Aaron said cheerfully. “Did you get the address changed?”

My throat tightened.

“Why is there a hundred-and-eighty-five-thousand-dollar loan in my name?”

Silence.

Not confusion.

Silence.

Then Aaron said, “Natalie, don’t do anything until I get home.”

That sentence frightened me more than a denial would have.

“What did you use the money for?”

“It’s complicated.”

“Did you forge my signature?”

“Natalie, listen to me.”

I ended the call.

The fraud specialist slid one final document across the desk.

It was the destination account information for the original transfer.

Willow Creek Properties had two authorized owners.

One was Aaron.

The other was a woman named Vanessa Reed.

Her address was a condominium fifteen minutes from the office where my husband claimed to work late three nights a week.
I did not drive to Vanessa’s condominium, although every furious instinct in me wanted to stand on her doorstep and demand an explanation. Instead, I called my older brother, then a divorce attorney named Rebecca Sloan, who told me the same thing the bank had already said: do not confront anyone until I understood exactly what had been done in my name.

That afternoon, the bank froze further draws from the line of credit while its fraud department opened an investigation. I filed an identity-theft report and gave investigators samples of my genuine signature, including mortgage documents from our recent home purchase that made the differences obvious once someone knew where to look.

Aaron came home around seven.

I had never seen him look frightened before.

“Natalie, I can explain the loan.”

“Start with Vanessa Reed.”

He stopped halfway across the kitchen.

That was the second answer he gave me without speaking.

Aaron eventually admitted that Vanessa was not a business partner. She was someone he had met four years earlier while working on a commercial-development project, and what began as an affair had continued long after he repeatedly promised me that his late nights were caused by deadlines and client meetings.

I thought the worst part had arrived.

Then he said, “There’s something else.”

Vanessa had a three-year-old daughter.

Aaron was the father.

I remember sitting down because my knees stopped cooperating.

For three years, my husband had maintained another household while we discussed starting a family of our own. The condominium belonged to Willow Creek Properties, an LLC Aaron had created with Vanessa, and the money borrowed in my name had been used partly to pay down its mortgage and partly to cover business debts Aaron had accumulated after one of his developments failed.

“You stole my identity to buy your mistress a home?”

“It wasn’t like that.”

I laughed once, although nothing was funny.

“Then tell me what it was like.”

Aaron insisted he had always planned to repay the loan before I discovered it. He said our old house had enough equity, the property investment would eventually recover, and he had forged my electronic authorization because he believed I would refuse to let him use our marital assets.

“You’re right,” I said. “I would have refused.”

“That’s why I couldn’t tell you.”

The absurdity of his answer silenced me.

I packed a suitcase that night and stayed with my brother.

Over the following weeks, the situation became worse as investigators reconstructed the paperwork. Aaron had not simply imitated my signature once; he had created an email address resembling mine, uploaded a copy of my driver’s license, answered identity-verification questions using information from our tax returns, and communicated with the lender while pretending to be me.

The bank’s investigators also found that several monthly payments on the fraudulent loan had come from our legitimate joint checking account.

I had seen those withdrawals before.

Aaron had labeled them “property tax reserve” in the spreadsheet he used to manage our household finances.

Rebecca stared at the records during one of our meetings and said, “This is why you do not let him turn this into an argument about an affair. The affair matters to your marriage, but the financial fraud is a separate issue.”

I filed for divorce.

Aaron responded by asking me not to involve police because a criminal case could destroy his career and affect his ability to support his daughter. When I reminded him that he had been willing to put nearly two hundred thousand dollars of debt under my name without permission, he accused me of trying to punish an innocent child.

That was the last private conversation I had with him.

From then on, everything went through lawyers.

And once financial investigators began examining Willow Creek Properties, they discovered that the loan in my name was not Aaron’s only hidden debt.

Aaron had borrowed against two business assets, carried tens of thousands of dollars in undisclosed credit-card debt, and moved money between personal and corporate accounts whenever payments became difficult to manage. Not all of that activity was illegal, but it explained why he had become desperate enough to treat the equity in our former home as money he could secretly access.

The bank’s forensic review concluded that I had not authorized the home-equity loan.

Because the lender’s identity-verification procedures had also failed to catch several inconsistencies, the bank eventually removed the fraudulent debt from my responsibility while pursuing recovery through Aaron and the property connected to the transaction. My credit reports took months to correct, and I placed additional fraud protections on my accounts because I no longer knew what information Aaron might have used elsewhere.

The criminal investigation continued separately.

Prosecutors relied not only on my accusation but on the fake email account, electronic application records, uploaded identification, banking transfers, and messages Aaron had sent Vanessa discussing the loan. One message was especially damaging because Vanessa had asked, “Does Natalie know you’re using the old house?”

Aaron had answered, “She doesn’t need to know if I replace it before we sell.”

We had sold that house four months later.

The loan had remained.

Vanessa cooperated with investigators after hiring her own attorney, insisting Aaron had told her I knew about the financing and had agreed to the investment. Her messages supported parts of that claim, and prosecutors ultimately treated her primarily as a witness rather than assuming she had participated in the identity theft.

That distinction mattered to me.

I hated learning that she had been involved with my husband, but I refused to invent crimes for her merely because I was angry.

Aaron eventually pleaded guilty to charges related to identity theft, forgery, and financial fraud rather than taking the case to trial. His sentence included prison time, supervised release, restitution, and restrictions connected to handling certain financial accounts, although the exact losses were divided among several civil and criminal proceedings.

Our divorce was finalized before his sentencing.

The new house we had purchased together was sold because neither of us could realistically maintain it alone while the financial disputes were unresolved. After legitimate debts and legal expenses were addressed, my share of the remaining equity became the down payment on a much smaller townhouse.

The first night there, I ate takeout on the floor because I had not purchased a dining table yet.

It was the most peaceful meal I had eaten in years.

A few months later, Vanessa contacted me through our attorneys.

She did not ask for forgiveness.

She simply wrote that she had ended her relationship with Aaron and intended to raise their daughter without involving me in their lives. She also apologized for believing his repeated claim that our marriage existed only “on paper.”

I never responded.

Some truths did not require another conversation.

Marcus, the banker who first noticed the loan, called after the fraud department officially closed my dispute. He was careful not to discuss anything confidential, but he asked whether my credit file had finally been corrected.

“Yes,” I told him. “It’s clean.”

There was a pause.

“I’m glad I stopped typing that morning.”

“So am I.”

For months afterward, I kept thinking about how ordinary the discovery had been.

There was no lipstick on a shirt, no mysterious hotel receipt, and no stranger knocking on my door with photographs. I had walked into a bank carrying a utility bill because we had moved and I wanted our statements sent to the correct address.

If Marcus had simply changed the address without noticing the second product attached to my profile, I might not have discovered the truth until a missed payment damaged my credit or investigators came looking for money I never knew I had borrowed.

Aaron had spent years dividing his life into separate compartments: wife, mistress, child, investments, debt, lies.

He believed that as long as those worlds never touched, he could continue controlling all of them.

In the end, everything collapsed because of one routine screen at a bank.

The moment Marcus turned that monitor toward me, I thought I was looking at a loan.

What I was actually seeing was the first crack in the life my husband had built behind my back.