“You need to be out in two weeks.”
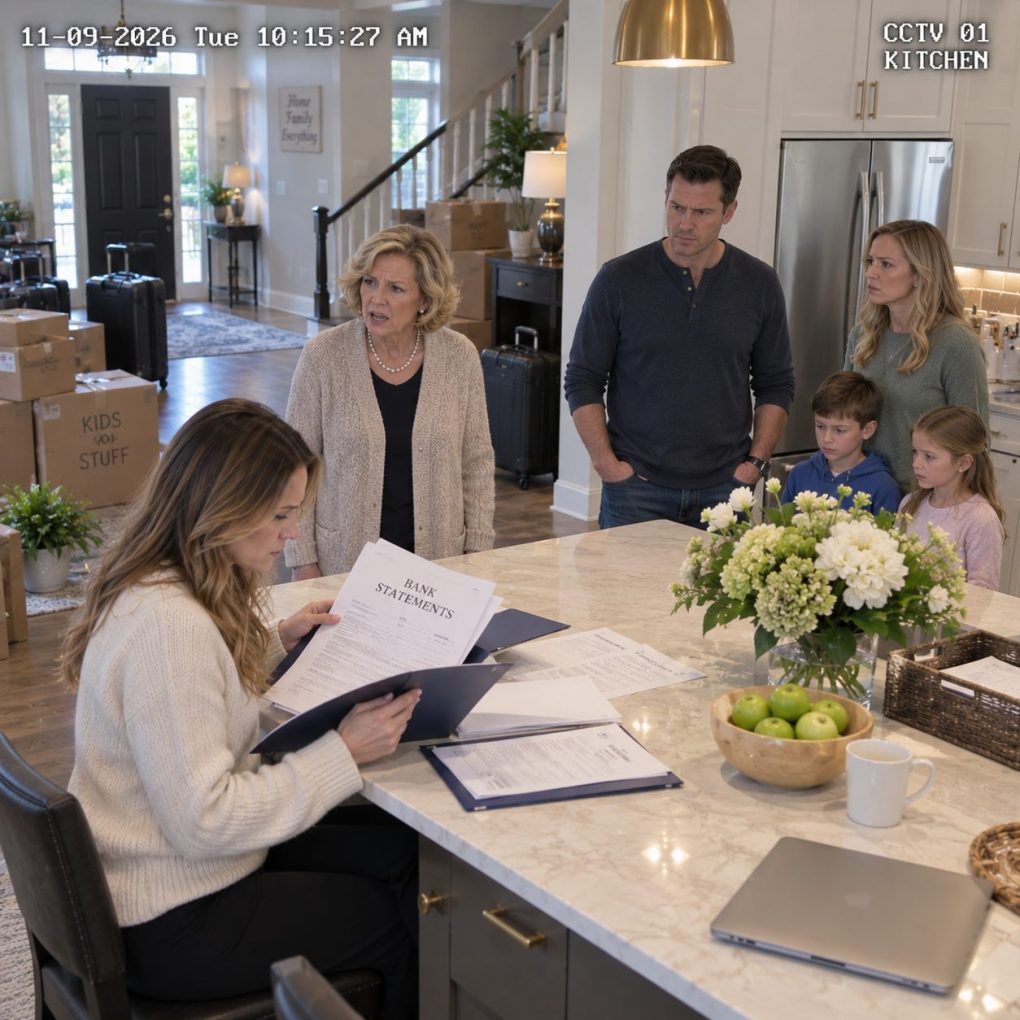
My mother-in-law said it from the kitchen of the house I had been quietly funding for years.
Linda stood beside the counter with her daughter, Megan, while my husband, Scott, stared at the floor.
I waited for him to say something.
Anything.
He didn’t.
Linda folded her arms.
“Megan needs the space more than you do. She has three kids.”
I looked around the kitchen.
The cabinets I had paid to replace.
The refrigerator I had bought.
The roof I had refinanced my own condo to repair.
For six years, Scott’s family had called this “Linda’s house.”
Technically, that was true.
Her name was on the deed.
What nobody ever mentioned was that she had been less than three months from foreclosure when I stepped in.
Scott and I had only been married a year then.
Linda had fallen behind on the mortgage after his father died.
The bank had already started sending notices.
Scott begged me to help.
So I did.
Not with one check.
With an agreement.
My attorney drafted it.
I paid the arrears, then began making the mortgage directly.
In exchange, Linda signed a secured repayment agreement stating that every housing payment, tax payment, major repair, and insurance advance I made would become a documented debt against the property.
If the house sold or transferred, I was repaid first from the proceeds.
If Linda defaulted on the agreement, additional protections applied.
Nobody talked about that paperwork after the crisis passed.
They just got used to me paying.
Now Megan wanted to move in after her divorce.
Apparently, I was the easiest person to remove.
Scott finally spoke.
“Rachel, maybe we can find an apartment.”
I stared at him.
“We?”
He flinched.
Linda sighed.
“Don’t turn this into drama.”
I nodded slowly.
“Two weeks?”
“Yes.”
“Okay.”
Megan smiled.
That was almost funny.
I walked upstairs to the bedroom Scott and I had used for five years and opened the bottom drawer of my desk.
Inside was a thick blue folder.
Bank statements.
Mortgage confirmations.
Property-tax receipts.
Insurance payments.
Contractor invoices.
The signed repayment agreement.
I added everything once.
Then again.
The total was just over $286,000.
I called my attorney, Daniel Reeves.
He answered on the second ring.
“Rachel?”
“I think the agreement just became relevant.”
The next morning, Linda found an overnight letter taped inside the front door.
She opened it at the kitchen table.
Scott was beside her.
Megan was making coffee.
I watched Linda read the first page.
Then the second.
Her face drained of color.
“What is this?”
I closed my suitcase.
“The amount you owe me if you want me out.”
Scott grabbed the papers.
Megan stopped smiling.
And for the first time, all three of them realized the house they thought they were rearranging came with a bill none of them had ever bothered to count.
Linda accused me of trying to steal her house. I reminded her I had never asked for ownership. The agreement said exactly what it had always said: I was a secured creditor for specific payments I had made on her behalf.
Scott read the documents twice.
Then he looked at me.
“You kept all of this?”
“You signed as a witness.”
His face changed.
He had forgotten.
That hurt more than Linda’s demand.
Years earlier, he had sat beside me in my attorney’s office and thanked me for saving his mother’s home.
Now he had stood silently while she gave me fourteen days to leave it.
Linda called her own attorney that afternoon.
He did not tell her what she wanted to hear.
The agreement was properly executed.
The payment records matched.
The mortgage company confirmed years of transfers from my accounts.
Property taxes, roof replacement, plumbing repairs, insurance premiums, and emergency electrical work were all documented.
Not every household expense counted toward the secured balance.
My attorney had been careful about that.
Groceries did not.
Utilities did not.
Furniture did not.
Only the categories listed in the agreement.
That made the number harder to dismiss.
Then came the clause Linda had completely forgotten.
If she voluntarily transferred possession of the property to another household while demanding that I vacate, the secured balance became immediately due unless we signed a written modification.
Megan stared at her mother.
“You said the house was paid off.”
“It almost is.”
“That’s not what this says.”
The mortgage had less than $70,000 remaining.
My documented claim was more than four times that.
The house was worth around $410,000.
There was equity.
But nowhere near the amount Linda imagined she could casually hand to Megan.
Selling the house would mean paying the mortgage, transaction costs, and then addressing my secured claim from what remained.
Moving Megan in did not magically erase any of it.
Scott pulled me aside that evening.
“Can we fix this?”
I asked, “Which part?”
He looked exhausted.
“All of it.”
“You watched your mother throw me out.”
“I thought you’d stay with me somewhere else.”
That answer told me he still did not understand.
He thought this was about where I slept.
It was about whether I mattered when his family wanted something.
Then Linda made the situation worse.
She tried to refinance the house to pay me off and keep enough money for Megan’s move.
The lender found my recorded interest during title review.
The refinance stalled immediately.
By morning, what had been a family moving plan had become a financial emergency.
Megan could not afford another rental deposit.
Linda could not access enough equity without resolving my claim.
Scott could not solve either problem because most of our joint savings had already been spent covering his family’s past emergencies.
For the first time in six years, nobody asked me for another payment.
They asked me what I wanted.
I looked at all three of them and answered:
“An exit.”
Scott went pale.
“You mean from the house?”
I looked at him.
“No.”
That was when he finally understood the marriage was now part of the negotiation too.
I did not file for divorce the next morning.
I moved into a short-term apartment and gave myself time to decide without Linda, Megan, or Scott standing in the same room.
That distance clarified everything.
Scott asked for counseling.
I agreed.
Not because I had already decided to stay, but because fourteen years of partnership deserved an honest ending if nothing else.
In therapy, he admitted something I had never heard him say aloud.
He had spent his entire life managing his mother’s fear of losing security.
When she demanded something, he gave in because resistance felt cruel.
When I became financially capable, he quietly let me become the solution.
Then he stopped noticing what that cost me.
That explanation was useful.
It did not erase what happened.
Meanwhile, Linda’s attorney negotiated with mine.
I had no desire to force an immediate sale if another workable option existed.
Eventually, we reached one.
Linda sold a smaller investment parcel she had inherited years earlier and used the proceeds, along with part of a legitimate home-equity loan, to repay a substantial portion of my documented claim.
The remaining balance was converted into a formal installment obligation secured against the house.
Megan did not move in.
She found a rental near her children’s school.
For once, Linda helped her without using my money.
That mattered.
Scott and I separated for six months.
During that time, he opened individual accounts, stopped volunteering our resources to relatives, and repaid part of the joint savings he had previously diverted toward family emergencies.
He also apologized without adding “but Mom.”
That mattered too.
We eventually stayed married.
Slowly.
With boundaries that existed on paper and in behavior.
Linda never liked the agreement afterward.
But she respected it.
Years later, she sold the house voluntarily and moved into a smaller condo.
My remaining balance was paid at closing exactly as the documents required.
When the wire hit my account, I felt less triumphant than I expected.
Mostly, I felt finished.
Scott asked whether I regretted helping his mother all those years ago.
I thought about it.
“No.”
He looked surprised.
“I regret helping people who thought help erased the need for respect.”
That was the difference.
The payments had not been the mistake.
The silence around them was.
I had quietly covered crisis after crisis because I believed generosity should not keep score.
I still believe that.
But generosity is not the same as pretending money has no consequences.
It is not agreeing to become invisible because other people benefit from your contribution.
And it is definitely not allowing someone to call a house theirs while treating the person keeping it afloat like a disposable guest.
The blue folder stayed in my filing cabinet long after the final payment cleared.
I kept it for one reason.
It reminded me that documentation is not hostility.
Sometimes it is the only thing standing between what people remember and what actually happened.
Linda remembered giving us a home.
Scott remembered everyone helping everyone.
Megan remembered a family property she could move into.
The records remembered something else.
They remembered every payment.
Every repair.
Every promise.
And when the family finally tried to erase my place in the house, the paperwork simply refused to cooperate.