My mother-in-law’s phone was still in her hand when she told me I had thirty days before she “stopped carrying” me.
We were halfway through her seventieth-birthday dinner at a steakhouse outside Boston. Twelve relatives were watching. My husband, Evan, stared at his plate while his mother, Diane, smiled over her wineglass.
“For seven years, I’ve paid for your house, your vacations, your cars, everything,” she said. “Let’s see how long you last without my money.”
A few people laughed because they thought she was joking.
I didn’t.
Diane had spent years telling that story. According to her, I was the lucky daughter-in-law who married into security. I worked from home, dressed simply, drove the same gray Volvo for six years, and never corrected her when she announced that her monthly transfers were “keeping our little family afloat.”
The truth was more complicated, and until that night, I had kept it private for Evan’s sake.
He finally looked at me. “Claire, don’t.”
That hurt more than anything Diane had said.
Not “Mom, stop.”
Just don’t, aimed at me.
Diane leaned back. “Starting tomorrow, no more mortgage help. No more family card. No more summer camp. You wanted independence? Congratulations.”
I set down my fork.
“Okay. Stop paying.”
Evan’s knee knocked mine under the table. I ignored it.
Diane laughed. “You have no idea what things cost.”
Actually, I knew exactly what things cost.
For seven years, I had reviewed the quarterly statements for Bennett Home Supply, the company Diane called “the family legacy.” I knew its margins, debt covenants, payroll cycles, and the reason its operating line had survived the pandemic.
Me.
Seven years earlier, when Evan’s father was dying, he had asked me for one favor. Bennett Home Supply was close to defaulting, and the bank would renew its credit line only if someone with sufficient liquid assets signed a personal guarantee.
I had recently sold my stake in a software company I helped build before marrying Evan.
I signed.
No one at family dinners knew. Diane believed her husband had “worked something out with the bank.” Evan knew the truth, but his father had asked us to keep it quiet until the company recovered.
It never really recovered.
At 10:47 that night, after we got home and Evan accused me of “making Mom look stupid,” I opened my laptop.
The company’s credit line was up for annual renewal the next morning.
For three years, my attorney had warned me to stop guaranteeing debt for people who treated me like an obligation.
This time, I listened.
I emailed the bank and copied my attorney. I did not withdraw money or touch Diane’s accounts. I simply declined to renew my personal guarantee.
At 8:16 the next morning, Diane called Evan.
He put her on speaker.
“My banker says the line can’t be renewed.”
Then she went silent.
When she spoke again, she wasn’t laughing.
“Claire,” she whispered. “What did you do?”
Before I could answer, Evan’s face changed.
Because Diane’s banker had apparently told her something else.
Something Evan had promised me she would never find out.
For the first time in seven years, Diane was about to learn who had really been keeping her family business alive. But the bank’s revelation wasn’t the part that frightened Evan most. There was another secret buried in those accounts.
Diane’s next words came out breathless. “The banker says you’re the guarantor. You? Since when?”
I looked at Evan. He wouldn’t meet my eyes.
“Since your husband asked me seven years ago,” I said. “The line was going to be closed. I guaranteed it.”
Diane went quiet, then snapped that Robert would never have done something that important without telling her. I almost believed she was genuinely shocked until Evan stood up and walked into the kitchen.
That was when I knew there was more.
I followed him. “What did you tell her?”
He rubbed both hands over his face. “I told Mom Dad refinanced some investments. I thought it would keep the peace.”
“Seven years of peace for whom?”
His phone rang again. This time it was Diane’s controller, Melissa Grant. She asked to speak to me privately. Evan tried to keep the call on speaker, but I took the phone and stepped into my office.
Melissa sounded terrified.
The bank had requested updated records because my guarantee was being removed. While preparing them, she found years of charges coded as “executive family support”: our mortgage transfers, resort deposits, vehicle payments, gifts to Evan’s sister, even Diane’s birthday trips.
I felt cold.
“How much?”
“Just over four hundred eighty thousand dollars since 2019.”
I stared at the wall.
Diane had not been supporting us with her personal money.
She had been routing company funds through an expense account, then presenting those payments to the family as gifts from herself.
Worse, part of that cash had come from the revolving credit line I personally guaranteed.
For years, she had humiliated me for living on money that, indirectly, I was helping the company borrow.
Melissa said Robert had prohibited personal expenses from being charged to the business. After his death, Diane had changed the classifications. She had also signed several approvals herself.
Then Melissa said something that made my stomach drop.
“Claire, Evan approved some of them too.”
I stopped breathing for a second.
Not all of them. But enough.
When I walked back into the kitchen, Evan saw my face and knew exactly what I had learned.
“I can explain.”
“No,” I said. “Tell me whether you knew your mother was using company money to play benefactor.”
He sank into a chair.
He admitted Diane had told him the transfers were harmless accounting. He signed because she promised the company would repay everything once sales improved. He never told me because he knew I would refuse to keep guaranteeing the line.
Then the doorbell rang.
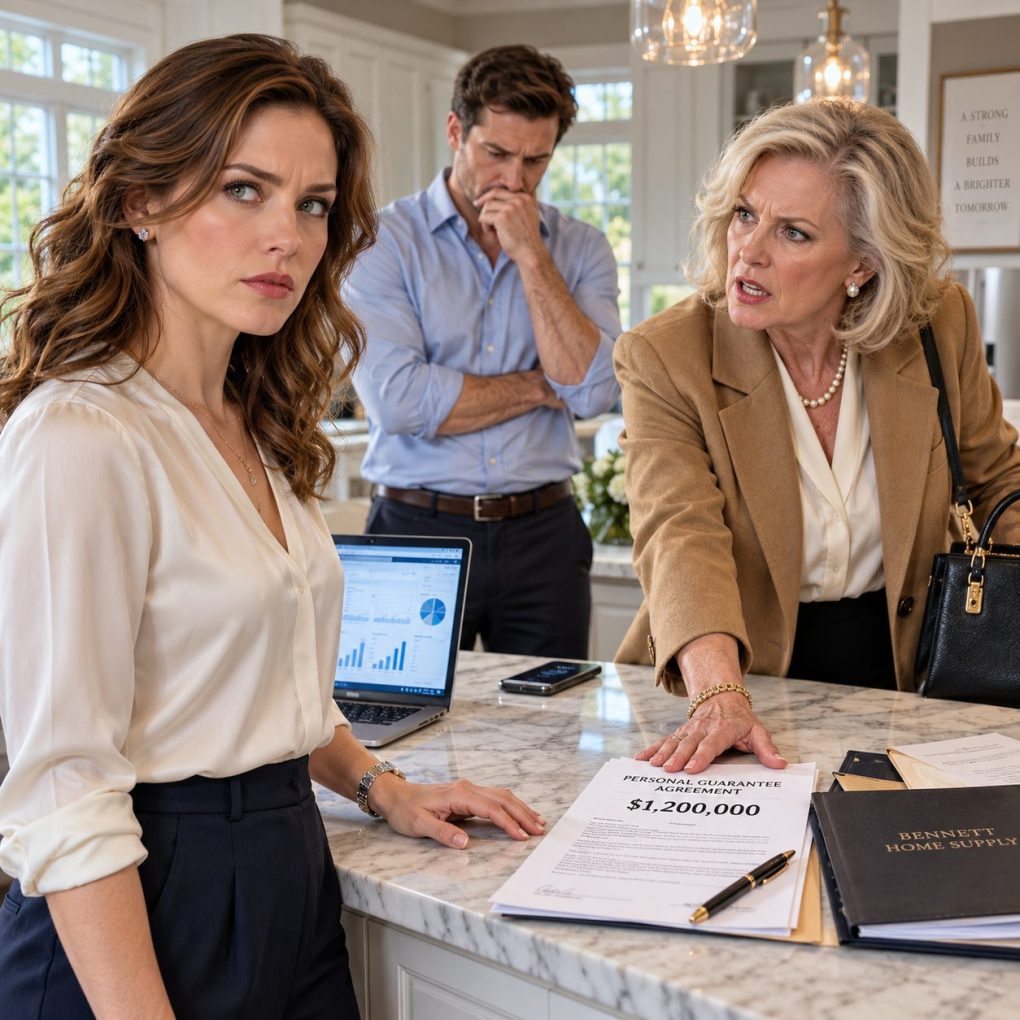
Diane was standing on our porch in yesterday’s clothes, clutching a folder.
She pushed past Evan, dropped the papers on my kitchen island, and said, “Sign this, and we can fix everything.”
I looked down.
It was a new personal guarantee.
For $1.2 million.
And my name was already typed on the signature line.
I did not touch the pen.
Diane pushed it closer. “This is temporary. Once holiday inventory turns, the bank will relax.”
I looked at the $1.2 million figure again. “Your current line is six hundred thousand.”
“We need room.”
“For what?”
Evan answered quietly. “The old line, vendors, payroll, and the expenses Melissa found.”
That ended the argument. They were asking me to risk twice as much money so the company could bury a problem they had hidden from me.
I slid the papers back.
“No.”
Diane called me emotional and vindictive. She said I was willing to destroy a company that employed eighty-three people because of one unpleasant dinner.
“The dinner didn’t create this,” I said. “It just ended my willingness to carry it.”
Then I called my attorney, Laura Chen.
By noon, Laura was at our house. She reviewed the proposed guarantee, Melissa’s records, and my original agreement with the bank. Her advice was simple: sign nothing and let the bank finish its review.
The next two weeks were brutal.
The bank suspended new advances while it examined the company’s financial statements. Vendors started calling. Diane told relatives I had “frozen the family business,” and my sister-in-law sent me a furious message calling me cruel.
I forwarded it to Evan.
“Handle your family.”
For once, he did.
He told them I had guaranteed the company’s debt for seven years. He told them Diane’s so-called gifts had come from company accounts. And he admitted that he had approved some of those expenses.
Nobody laughed after that.
The independent review found $482,000 in personal and family expenses charged to Bennett Home Supply. Some might have been lawful compensation or distributions if documented properly. Others had no business purpose at all.
The accountant warned that amended filings could be required. The bank refused to renew the line under the existing structure.
Diane blamed Melissa, then Evan, then me.
Laura’s response was one paragraph: I had taken none of Diane’s money and touched none of her accounts. I had simply declined to guarantee another year of borrowing with my own assets.
A week later, Diane came back without a folder.
“What do you want?” she asked.
“I want my name off the debt. I want the employees protected if possible. And I want you to stop telling people you supported me.”
“You want the company.”
“No. I never did.”
That seemed to unsettle her more than anger would have.
Bennett Home Supply still had real value: three profitable locations, loyal vendors, and a strong regional name. Its biggest problems were debt and management.
The bank gave the family a short period to pursue a sale or new financing. Diane wanted me to provide the financing.
I refused.
Instead, Evan contacted a larger New England home-improvement group that had tried to buy the company before. Three weeks later, they made an offer large enough to pay the bank, catch up key vendors, preserve most jobs, and leave the family something after closing.
There was one condition.
Diane could not stay in management.
She cried when she read it.
For years, she had treated the company as proof that she was the person holding everyone else up. Now saving it required her to let go.
She accepted.
The sale closed in January. The bank was paid in full, and my personal guarantee was formally released. Seventy-nine of the eighty-three employees received offers from the buyer. The remaining four received severance.
Diane also signed an agreement addressing the personal expenses found in the review. Part of her sale proceeds went toward repayment, while the accountants handled the required tax corrections.
There were no handcuffs, no courtroom spectacle.
There were still consequences.
She lost control of the company. She sold her lake house that spring. And for the first time in years, she had to live within a budget she could not disguise as generosity.
My marriage was harder.
I could understand Evan being afraid of his mother. I could not excuse him turning that fear into dishonesty.
He moved into a furnished apartment for three months. We started counseling. I made no promises about whether we would stay married.
What changed things was not his apology. It was what he did afterward.
He stopped asking me to keep family secrets. He showed me every account. He corrected relatives when they repeated Diane’s version of events. Most importantly, he took responsibility without adding “but Mom” to every sentence.
Slowly, trust stopped feeling impossible.
We eventually stayed together, not because the crisis fixed us, but because Evan spent the next year becoming someone who could disagree with his mother without using me as a shield.
Diane and I did not become close.
Six months later, she came to our house for our daughter’s birthday. She brought one gift, stayed two hours, and never mentioned what it cost.
Before leaving, she stopped beside me in the kitchen.
“I was wrong about you,” she said.
Then, after a long pause, she added, “I liked people thinking you needed me.”
That was the closest thing to honesty I had ever heard from her.
“I know.”
A year after the steakhouse dinner, I drove past the old Bennett Home Supply headquarters. The stores were still open. Employees were still arriving for work. Life had continued without Diane controlling it and without me financing it.
For seven years, I thought keeping quiet was the price of keeping peace.
It wasn’t peace.
It was permission.
The night Diane said, “Let’s see how long you last without my money,” she expected me to panic.
Instead, I stopped guaranteeing hers.
That decision did not destroy the family.
It finally forced us to tell the truth about who had been carrying what.