The locksmith was drilling through my front deadbolt when I pulled into the driveway.
I slammed the car door so hard the neighbor’s dog started barking. “What are you doing?”
Before the locksmith could answer, my mother-in-law, Carol, stepped out of my house holding a folder against her chest.
“Lauren,” she said, with that calm little smile she used whenever she was about to tell me how my own life should work. “Don’t make a scene.”
My husband, Evan, appeared behind her.
He wouldn’t look at me.
That scared me more than the drill.
“Evan?”
He rubbed both hands over his face. “Just come inside.”
“No. Tell him to stop.”
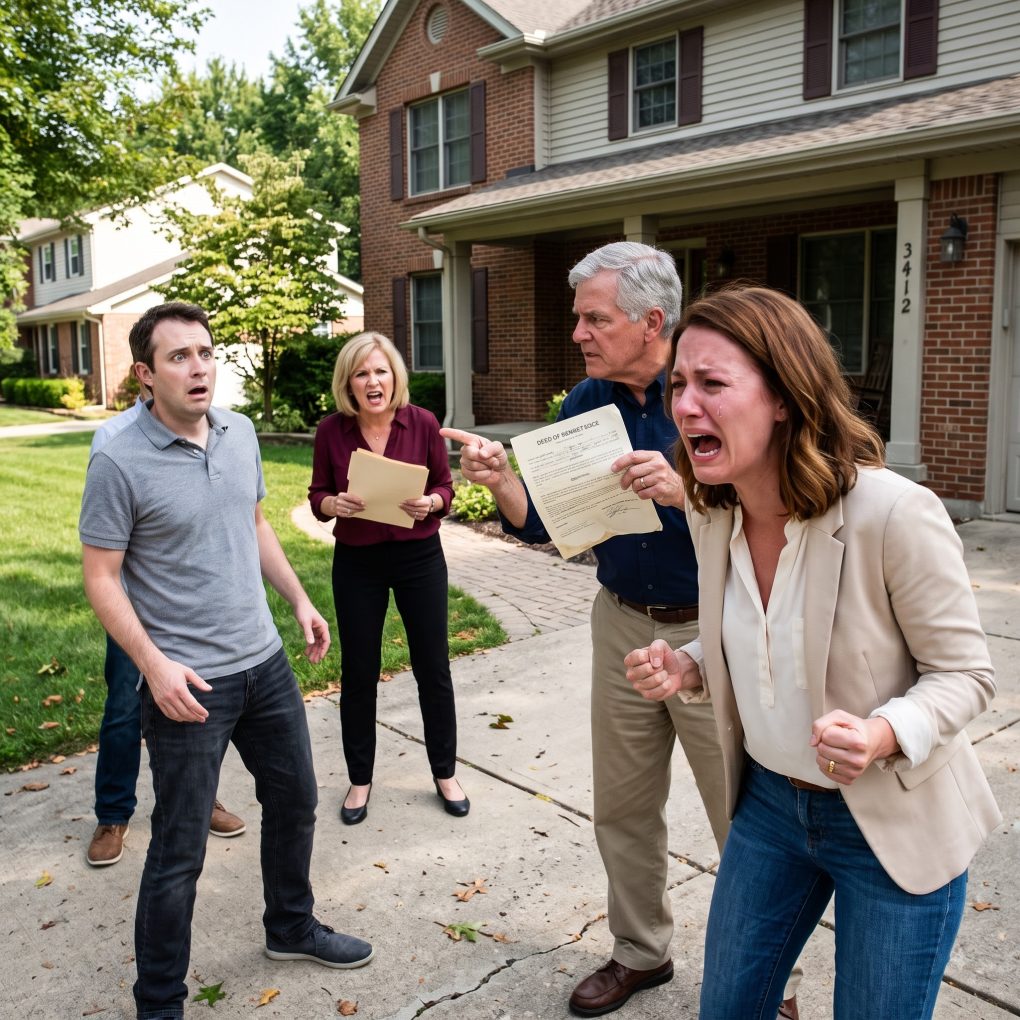
Carol lifted the folder. “He’s changing the locks because this house is legally mine now.”
For a second, I actually laughed.
Not because it was funny. Because my brain rejected the sentence.
Then she opened the folder and handed me a photocopy stamped by the Franklin County recorder’s office.
QUITCLAIM DEED.
My address.
My husband’s name.
My name.
And beneath them, Carol’s.
I stared at the signature beside my printed name.
It looked almost like mine.
Almost.
“What is this?”
Evan finally stepped forward. “It was supposed to be temporary.”
My stomach dropped.
“You knew?”
“Lauren, listen—”
“You knew?”
Carol cut in. “Your husband understands that family sometimes has to make sacrifices.”
I looked at Evan. “Did you sign this?”
He swallowed. “My part, yes.”
“And mine?”
Silence.
The locksmith stopped drilling.
I could hear a lawn mower somewhere down the block, absurdly normal while my marriage cracked open on the driveway.
Carol sighed. “We needed the property transferred for financing. I’m not taking anything from you.”
“You are literally changing the locks on my house.”
“It’s collateral.”
“For what?”
Evan muttered, “Mom had a business problem.”
I turned on him. “So you gave her our house?”
“We can reverse it.”
“Then reverse it now.”
Carol’s voice sharpened. “It doesn’t work that way.”
That was when I called my father.
He was twenty minutes away, but he made it in twelve.
Dad didn’t yell when he arrived. Daniel Reed never yelled. He walked straight past Carol, took the deed from my shaking hand, and read every line twice.
Evan started talking fast.
“Daniel, this is just paperwork. Carol needed short-term financing. Nobody is losing the house.”
Dad ignored him.
He took out his phone, searched something, then looked at the notary stamp.
His face changed.
Carol noticed too.
“What?” she snapped.
Dad turned to Evan.
I had already pulled off my wedding ring.
I held it out to my husband.
“You can stay married to your mother,” I said. “I’m done.”
Evan stared at the ring in my palm.
Carol suddenly reached for the deed. Dad moved it behind his back.
“Give me that,” she said.
“No,” Dad replied.
Evan took one step toward him, then stopped when Dad raised his phone.
“I checked the Ohio notary database,” Dad said. “And I called the number attached to this commission.”
Then Dad asked one question.
Quietly.
“Evan, why was this deed notarized by a woman who died six months before Lauren supposedly signed it?”
Evan’s face went completely white.
I thought the forged deed was the betrayal. I was wrong. Before that afternoon ended, one glowing notification on Evan’s phone would reveal that Carol wasn’t the only person trying to take my house—and the reason my husband needed the money would make the fake signature look like only the beginning.
For three seconds, nobody moved.
Then Evan whispered, “Mom?”
Carol’s expression hardened. “That doesn’t prove anything.”
Dad held up the deed. “A dead notary’s stamp on a document my daughter never signed proves enough.”
The locksmith packed his tools, handed me my original key, and drove away.
Carol tried to follow him.
I stepped between her and the driveway. “You’re not leaving with that folder.”
“This is my property.”
“No,” Dad said. “It’s evidence.”
Evan looked sick.
I asked him again. “Who signed my name?”
He stared at Carol.
That answer was enough.
She snapped, “I was trying to save this family.”
“From what?”
Neither answered.
Dad flipped to the second page of the deed. At the bottom was a return address for a company I had never heard of: Brighton Capital Services.
He searched the name.
A lending office in Cincinnati.
Then he called.
A woman answered and, after Dad explained that I was the homeowner named on a disputed deed, transferred us to a fraud specialist.
The specialist couldn’t disclose everything, but she said enough.
There was a loan scheduled to close at nine the next morning.
The collateral was my house.
The requested amount was $187,500.
My knees nearly gave out.
Evan grabbed my elbow.
I pulled away.
“You said temporary paperwork.”
“It was.”
“One hundred eighty-seven thousand dollars is not paperwork.”
Carol folded her arms. “I would have paid it back.”
“With what?”
Silence.
The fraud specialist asked me to email my ID and a statement that I had never signed the deed. Dad began taking photos.
Then Evan’s phone, sitting on the porch railing, lit up.
CLOSING PACKAGE APPROVED — E. MERCER CONSULTING LLC.
I looked at him.
“Who is E. Mercer Consulting?”
Carol answered too quickly. “It’s nothing.”
I picked up the phone.
Evan reached for it. “Lauren, don’t.”
I opened the email.
The loan proceeds were not going to Carol.
They were going to an account belonging to E. Mercer Consulting LLC.
Evan Mercer.
My husband.
The man who had spent the afternoon pretending his mother had dragged him into her emergency.
I felt strangely calm.
“What did you need $187,500 for?”
His eyes filled.
“Tell her,” Carol said.
Evan shook his head.
Dad looked from him to Carol. “There’s more.”
Evan sat on the porch step.
Finally, he said, “I already took money.”
My throat tightened.
“How much?”
“Eighty-two thousand.”
“From where?”
He looked directly at me.
“The account your grandmother left you.”
I couldn’t speak.
That account required my signature for any withdrawal.
Unless someone had forged that too.
Then Carol’s phone rang.
She glanced at the screen and suddenly looked afraid.
She answered.
A man’s voice carried through the speaker.
“Mrs. Mercer, we know the deed is being challenged. If the money isn’t here by tomorrow, we’re coming after both of you.”
Carol hung up.
I stared at Evan.
“Both of you?”
He closed his eyes.
Dad asked, “Evan, who exactly do you owe?”
Evan finally told the truth in pieces.
A year earlier, he and Carol had started a small house-flipping company without telling me. Carol found distressed properties. Evan handled financing. Their first project went over budget, then a contractor dispute froze the sale.
Instead of admitting they were losing money, Evan took $82,000 from the investment account my grandmother had left me.
He forged my authorization.
He told himself he would replace the money before I noticed.
Then their buyer disappeared.
The private investor who had financed the renovation wanted his money back. Interest and penalties kept growing. By August, Evan and Carol owed more than $150,000.
That was why they needed my house.
Not to save Carol’s business.
To cover the hole they had created together.
Carol had prepared the false deed. Investigators later determined that the notarial information had been copied from an old document connected to a deceased notary. Evan supplied copies of my identification and financial records. Once the deed was recorded, they applied for the $187,500 loan through Evan’s LLC.
They planned to pay the investor, replace my missing inheritance, reverse the deed, and tell me nothing.
If everything worked, I was never supposed to know.
It didn’t work.
Dad called the police from my driveway.
The fraud specialist at Brighton Capital froze the closing before a dollar was released. My attorney filed an emergency action challenging the deed the next morning, and the lender agreed not to proceed while the ownership dispute was investigated.
Carol stopped acting confident the moment detectives arrived.
Evan stopped defending her about ten minutes later.
By midnight, they were blaming each other.
The threatening caller turned out to be the private investor. He had not sent anyone to hurt us, but he had threatened immediate lawsuits, liens, and fraud complaints if he was not repaid. The danger was financial and legal, but by then that was enough to make my hands shake.
I spent the next months untangling what they had done.
The forged deed was eventually declared invalid.
My house stayed mine.
The $187,500 loan never closed.
My bank’s fraud investigation confirmed that the withdrawal from my inheritance account had not been authorized by me. Between recovered funds, insurance coverage, and restitution required from Evan, most of the $82,000 came back.
My marriage did not.
Evan asked me to reconsider exactly once.
He said, “I was scared.”
I believed him.
I also knew fear had not signed my name.
Fear had not lied to me for a year.
Fear had not stood on my porch while his mother changed my locks.
Carol moved out of state after selling her condo to settle part of the debt. Evan pleaded to charges related to the forged documents and agreed to restitution. Our divorce became final the following spring.
Dad came with me to the courthouse.
When we walked outside, he handed me the old house key Carol had tried to replace.
“You keeping this?” he asked.
I looked at it for a moment, then slipped it into my pocket.
“Yes.”
Not because it opened a door.
Because nobody would ever decide again, behind my back, who was allowed to enter my life.