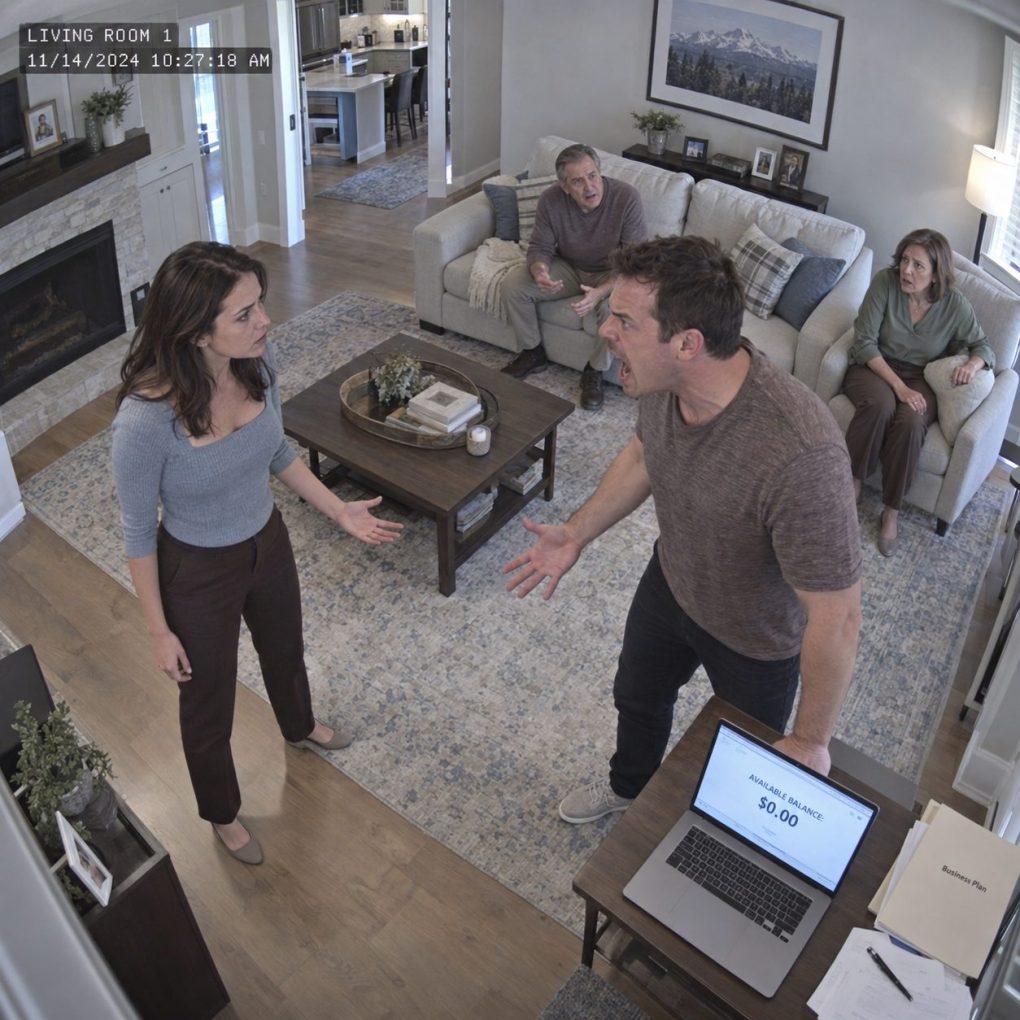
My brother called me laughing at 8:17 on a Monday morning. “Mom and Dad finally gave me access to your account,” Derek said. “Two hundred thirty-six grand. Guess who’s getting his business back?” Then he logged in—and went completely silent.
The balance on the old account was $0.00. I was sitting in my car outside a Denver medical office when I heard his breathing change. “Where is it?” he demanded. I looked through the windshield and said, “Somewhere you can’t touch.”
For twelve years, that account had held nearly everything I saved. I opened it at seventeen with my parents because I was still a minor, and nobody ever removed them as joint owners. By thirty-one, it contained $236,418 from my salary, bonuses, and years of living below my means.
My parents never contributed more than the original $200 opening deposit. Still, their names remained on the account, and legally that gave them powers I had been stupid enough to ignore. I learned how dangerous that was when Dad casually mentioned helping Derek “get back on his feet.”
Derek’s restaurant had collapsed eight months earlier. He owed vendors, a commercial landlord, and several private lenders after expanding too quickly. Instead of downsizing, he convinced our parents that one large cash injection would rescue everything.
I told them no. Mom cried, Dad called me selfish, and Derek sent me a message saying, “Family money should stay in the family.” That sentence bothered me enough to schedule an appointment with my bank.
The branch manager explained that because the account was jointly titled, either parent could withdraw funds without my approval. Worse, they could request additional online credentials or transact personally. I felt sick listening to him.
That afternoon, I opened a new account at a completely different bank in my name only. After confirming there were no holds, scheduled payments, or tax complications, I transferred every dollar that belonged to me and closed my access to the old banking profile.
I said nothing to my family. Three days later, Mom called asking for my birth date “for an insurance form.” I refused, then received a security alert showing someone had attempted to reset online credentials.
Now Derek was on the phone, staring at zero dollars after my parents had apparently handed him access. His cheerful voice disappeared. Then I heard Dad in the background say, “What do you mean she moved it?” and I knew this had never been about asking me for help.
Derek accused me of stealing money from my own family. The absurdity was so sharp I almost laughed, but I didn’t. I asked him one question instead: “Why were you logging into an account containing money you knew I earned?”
He said Dad had authorized it. I reminded him Dad had not earned the money either. Derek became defensive and claimed everyone had already agreed I could “afford to spare it.”
That phrase told me everything. There had been a family decision about my savings, and I had not been included. I ended the call and immediately contacted the bank’s fraud department.
Because my parents were joint owners, their own access had not necessarily been fraudulent. Sharing credentials or trying to create access for Derek, however, violated bank security rules and triggered an internal review. The representative froze the old profile while they investigated.
Then my mother arrived at my apartment. She did not knock gently. She pounded on the door until I opened it and shouted, “Do you understand what you’ve done to your brother?”
I asked whether she understood what she had tried to do to me. Mom insisted they were only “borrowing” $180,000 and planned to leave the rest untouched. I asked when anyone had intended to tell me.
She looked away. That silence hurt more than the amount. They had planned to take most of my savings first and explain later, once Derek had already used the money.
Dad came twenty minutes later carrying a folder. Inside was a business plan for Derek’s new restaurant concept, complete with projections showing my money as “family equity.” My name appeared on one page as a contributing investor.
I had never agreed to invest a dollar. When I pointed that out, Dad said they assumed I would eventually understand because the restaurant could “make all of us rich.” I asked whether Derek had told them about the judgment against him.
Both of them froze. I had found it two weeks earlier through public court records: a former investor had successfully sued Derek for misrepresentation related to his previous restaurant expansion. He owed more than $90,000 under the judgment.
Derek had apparently never mentioned it. Dad sat down without speaking, while Mom kept insisting there had to be an explanation. I told them the explanation was simple: they had nearly handed $180,000 of my money to someone already hiding serious debt.
Derek showed up that evening furious that I had “turned Mom and Dad against him.” I told him I had done nothing except show them a public court judgment he had deliberately hidden. He called the lawsuit meaningless.
Dad asked him directly whether he owed the money. Derek avoided the question twice before finally admitting that he did. He then claimed the new restaurant would solve everything once it opened.
That was the same logic he had used the first time. Borrow more, grow faster, and hope future revenue erased past mistakes. The difference was that this time he wanted to build the gamble with my savings.
My parents did not apologize immediately. For several days, they focused more on how embarrassed they felt than on what they had attempted. I stopped taking their calls until Dad finally sent a message containing the words I needed to see: “We had no right to decide for you.”
The bank closed the old joint account after all pending items cleared. My new account remained untouched, and I added security alerts, a verbal password, and restrictions preventing account information from being discussed with anyone except me.
I also met with an attorney. She helped me review beneficiaries, emergency contacts, and the other financial documents I had lazily left connected to family members. The experience taught me that independence is not just earning your own money; it is controlling access to it.
Derek never got the restaurant money. His planned lease fell apart when he could not produce the promised equity contribution. Eventually, he entered a repayment arrangement for the judgment and took a management job with an established restaurant group.
Months later, Mom admitted she had convinced herself taking my money was acceptable because I was single, financially stable, and “didn’t need it right now.” I told her that deciding I needed my own money less than Derek did was still taking it.
Our relationship survived, but it changed. I no longer discuss balances, bonuses, or investments with my family. When money comes up, I change the subject instead of defending what belongs to me.
Derek thought the frightening moment would be discovering $236,000 had disappeared. It wasn’t. The real shock was realizing the zero on that screen meant something permanent: I had finally removed my family’s ability to make financial decisions on my behalf.