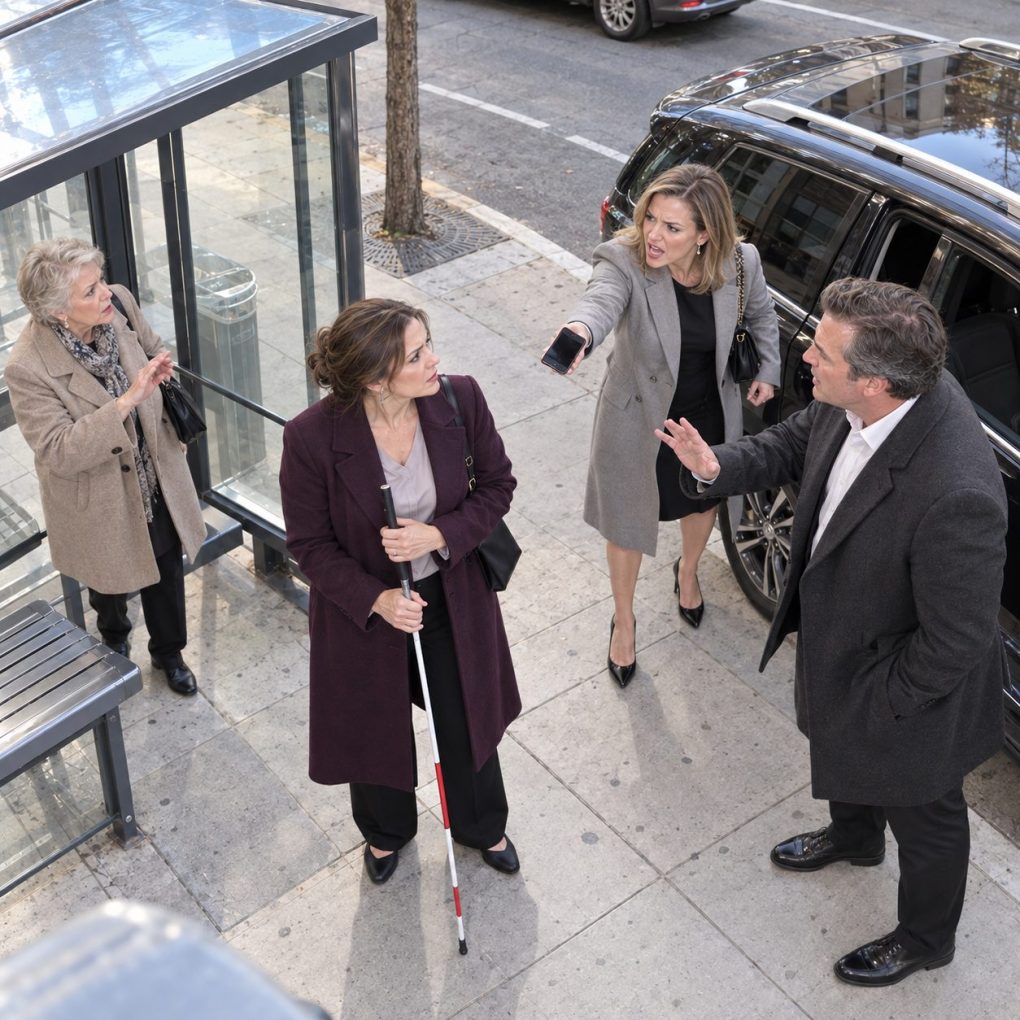
My sister left me sitting alone at a bus stop in Denver with twenty-three dollars in my coat pocket and no phone. Before closing the car door, Melissa leaned toward me and whispered, “You need to understand that you can’t manage your life anymore.” Then her husband drove away while I listened to their engine disappear into traffic.
I had lost my sight eighteen months earlier after complications from an infection damaged both optic nerves. Melissa initially offered to help with banking, transportation, and paperwork. I trusted her because she was my sister, not because blindness had erased my ability to think.
That morning, she claimed we were meeting an attorney about our late father’s estate. Instead, Melissa and her husband, Kevin, drove me to a bank and asked me to authorize several documents. When I demanded that someone read every page aloud, Kevin became irritated.
I refused to sign.
That was when Melissa admitted they had already moved money.
One hundred eighty-six thousand dollars from the inheritance account Dad had left solely to me had been transferred over several months. Melissa claimed she had authority because I had previously signed a limited financial power of attorney allowing her to pay specific household expenses during my rehabilitation.
I asked for my phone.
Kevin refused.
“Call anyone you want after you calm down,” he said.
Twenty minutes later, they abandoned me at the bus stop.
They believed taking my phone meant taking my evidence. They had forgotten what I did before losing my sight. For fourteen years, I investigated corporate fraud for an accounting firm. I had built cases from altered invoices, hidden transfers, falsified approvals, and executives who underestimated audit trails.
A woman waiting nearby heard me asking where we were. I explained that I was blind and needed assistance contacting someone. She let me use her phone.
I did not call Melissa.
I called my former colleague, Rebecca Shaw.
Rebecca arrived forty minutes later. From her car, I contacted the bank’s fraud department and reported unauthorized transfers. Then I called an attorney who specialized in financial exploitation and estate disputes.
That evening, Rebecca helped me access my accounts using my laptop’s screen reader.
The transfers were there.
$24,000. $38,000. $51,000. Smaller withdrawals followed.
The final transfer had occurred that morning.
I listened as the screen reader announced the receiving account information.
Then I smiled for the first time all day.
Melissa and Kevin had transferred the money into an LLC.
And Kevin had used that same LLC two years earlier in a business venture I had already investigated for him.
I knew exactly where to begin. Two years earlier, Kevin had asked me to review the bookkeeping for his struggling construction company. I found sloppy records but no obvious fraud. One entity, KLM Property Services LLC, had been created to purchase renovation materials and later became inactive.
That was the account receiving my inheritance.
My attorney, Sarah Mitchell, warned me not to investigate my own case as though I were still working professionally. We needed admissible records, not clever theories. She contacted the bank, preserved the account information, and began the legal process of obtaining transaction records.
I revoked Melissa’s power of attorney immediately.
The original document became important. It authorized her to pay utilities, medical expenses, rent, and rehabilitation costs from one designated checking account. It did not authorize her to access my inheritance account, transfer assets to herself, or move money into Kevin’s company.
Melissa called Rebecca the next morning because she could no longer reach me directly.
“She’s confused,” Melissa claimed. “Her disability has made her paranoid.”
Rebecca said nothing about where I was staying.
Meanwhile, Sarah discovered that several transfer requests contained electronic authorization records supposedly created by me. The transactions had been initiated from the internet connection at Melissa and Kevin’s house.
That alone proved little. I had stayed there during rehabilitation.
But the dates mattered.
Two transfers occurred while I was attending an adaptive technology program in Colorado Springs. Transportation records and program attendance confirmed I had been seventy miles away.
Then the bank produced another detail.
My account’s contact phone number had been changed three months earlier.
The new number belonged to Melissa.
Security alerts had therefore gone to her instead of me.
Kevin finally called Sarah and insisted the $186,000 represented reimbursement for caring for me. Sarah asked him for invoices, written agreements, or documentation showing I had approved such payments.
He provided none.
Instead, Melissa sent a spreadsheet claiming hundreds of thousands of dollars in caregiving expenses. I recognized the pattern immediately when Sarah read it aloud: round numbers, repeated descriptions, and charges entered months after the supposed services occurred.
They had manufactured an explanation after the transfers.
That mistake was worse than silence.
Sarah obtained an emergency court order restricting further movement of disputed funds while the case proceeded. Approximately $112,000 remained traceable in accounts connected to the LLC.
The rest had been spent.
When Melissa learned the accounts were restricted, she left me a voicemail.
“You’re destroying this family over money.”
I saved it.
Then I asked Sarah one question.
“When do they have to explain everything under oath?”
The answer was during depositions several months later. By then, Sarah had obtained banking records, account-change logs, transfer histories, and documents connected to KLM Property Services. Independent evidence had replaced every accusation Melissa once dismissed as my confusion.
Kevin’s explanation changed repeatedly. First, the transfers were reimbursement. Then they were investments I had supposedly approved verbally. Finally, he claimed Melissa handled everything and he merely allowed his LLC to receive the money.
Melissa blamed Kevin.
Their story collapsed because the records did not require either of them to confess. Her phone number had replaced mine on the account. Transfers had originated from their home. Money entered Kevin’s LLC and then paid their mortgage, credit cards, vehicle loan, and personal expenses.
The most painful discovery concerned my phone.
They had not taken it impulsively at the bus stop. Messages between them showed they had discussed preventing me from contacting the bank before confronting me that morning. Sarah referred those records to the appropriate authorities along with the financial evidence.
The civil case ended before trial.
Under the settlement, the remaining funds were returned, and Melissa and Kevin were required to repay additional amounts under an agreed schedule secured against property they owned. My attorney’s fees were also addressed as part of the resolution.
Separate authorities determined what consequences followed from the financial conduct. I did not control that process, and I stopped trying to predict it.
Melissa asked to see me once.
I agreed only with Sarah present.
My sister cried and said she had convinced herself that I would eventually need all my money managed for me anyway. After losing my sight, she said, I seemed vulnerable.
“I was vulnerable,” I answered. “That wasn’t permission.”
There was nothing else to discuss.
A year after the bus stop, I moved into an apartment designed for independent living. I used screen-reader software for banking, labeled household items with tactile markers, and hired transportation when necessary. Rebecca still helped sometimes, but only when I asked.
I also returned to work part-time.
My old firm invited me to advise investigators on financial-document analysis and interview strategy. I could no longer examine spreadsheets visually, but accessible software allowed me to work differently.
During my first week back, a younger investigator asked how I had recognized the pattern in my own case so quickly.
I told him fraud rarely depends on genius.
It depends on access, trust, and the belief that the victim will not look closely enough.
Melissa and Kevin had understood the first two perfectly.
Their mistake was assuming blindness had taken away the third.