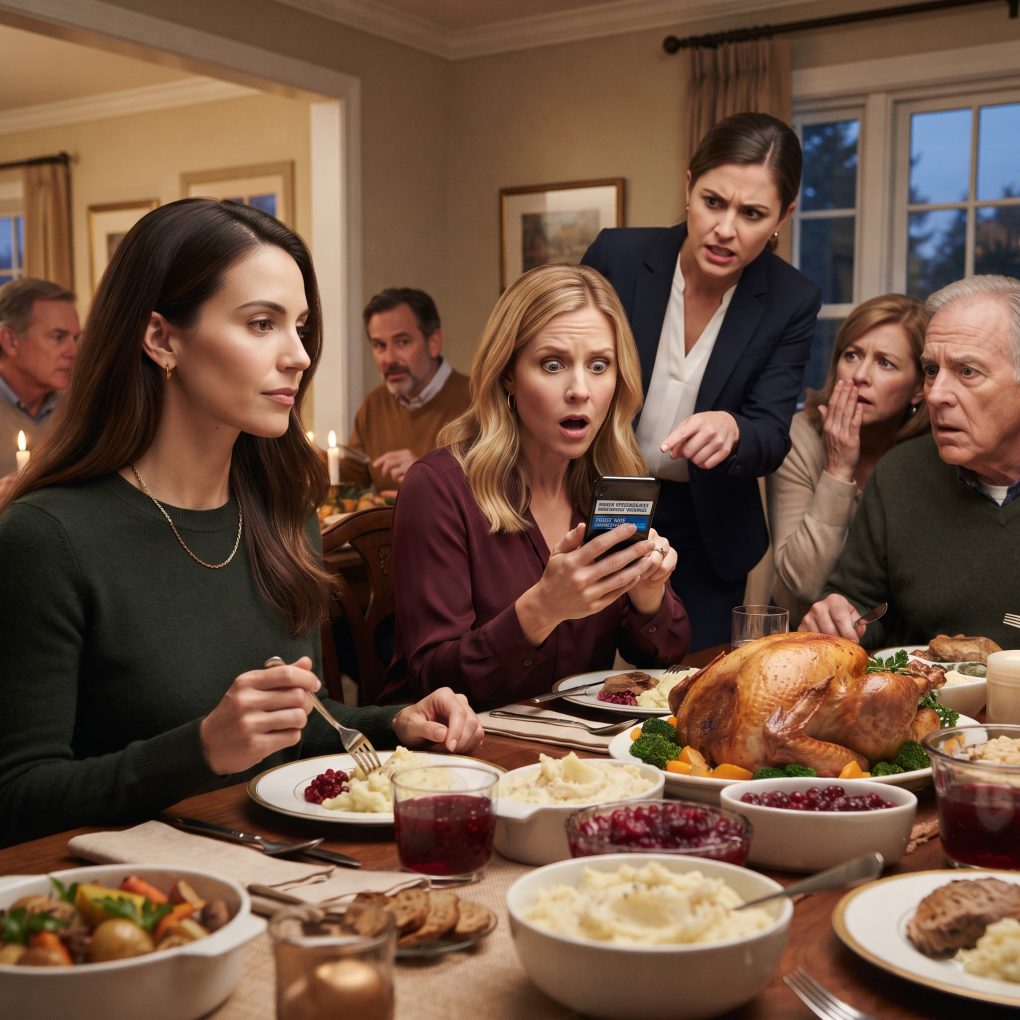
“They laughed at my investments during Thanksgiving dinner, mocking me at the table. Then her assistant burst in with devastating news: their major shareholder just dumped $250 million in shares and the stock is crashing.”
“STILL PLAYING WITH YOUR LITTLE INVESTMENTS?” my sister laughed across the Thanksgiving table.
Everyone smirked.
I kept eating.
She had spent the last ten years climbing the corporate ladder, and lately she loved reminding everyone that she was now the CEO of a publicly traded company.
My investments, meanwhile, were “cute,” according to her.
Mom laughed.
Dad shook his head.
I said nothing.
Then the dining-room doors suddenly flew open.
My sister’s executive assistant stood there, pale and breathless.
“Ma’am…”
My sister frowned.
“What are you doing here?”
The assistant held up her phone.
“Your major shareholder just sold $250 million in shares.”
Silence.
My sister’s smile disappeared.
“What?”
“The stock is plummeting. We’re down almost nine percent in minutes.”
Dad stopped chewing.
Mom whispered, “Is that even possible?”
The assistant nodded.
“They’re still selling.”
My sister jumped up.
“Who?”
The assistant hesitated.
“We’re trying to identify the account.”
My sister grabbed the phone.
“How much remains?”
“Another $70 million order is pending.”
Her face went white.
She turned toward me.
For the first time that evening, she wasn’t laughing.
“Why are you looking at me?” I asked.
“Because you invest in companies like mine.”
I shrugged.
“I invest in lots of companies.”
Her assistant suddenly stared at her screen.
“Ma’am…”
“What now?”
“The brokerage just confirmed the identity of the seller.”
My sister snatched the phone.
Her eyes moved across the screen.
Then she froze.
Dad leaned forward.
“Who is it?”
My sister slowly looked at me.
“You.”
Nobody moved.
I put down my fork.
My mother whispered, “You sold $250 million?”
I calmly wiped my hands with a napkin.
“No.”
My sister’s voice shook.
“Then why is your investment firm listed as the seller?”
I looked directly at her.
“Because I didn’t sell it.”
I paused.
“Someone sold it for me.”
And suddenly, my sister’s assistant received another notification.
She read it aloud.
“Your entire executive board has been summoned to an emergency meeting.”
My sister’s face went pale.
Because the meeting wasn’t about the falling stock.
It was about why I had just been removed from the company’s shareholder register.
They thought I was just the quiet relative who played with small investments. But the stock collapse had exposed something far more serious than a giant sale. Someone had moved millions of shares without my permission—and the person who ordered it knew exactly how to make my family blame me.
My sister stared at me.
“You’re saying someone sold your shares without permission?”
“Yes.”
“Then why did your investment firm execute the order?”
“I don’t know yet.”
Her assistant’s phone buzzed again.
She looked at the screen.
“There’s another update.”
My sister snapped, “Read it.”
“The exchange has placed a temporary review on the transaction.”
Dad stood.
“Can the sale be reversed?”
The assistant shook her head.
“Not automatically.”
My sister looked at me.
“This is going to destroy the stock.”
“Maybe.”
“You’re a major shareholder!”
“I was.”
She stopped.
“What does that mean?”
I reached into my jacket and pulled out my phone.
“Three months ago, I transferred voting authority over my shares to an independent custodian.”
My sister frowned.
“Why?”
“Because I was preparing for something.”
“For what?”
I looked at her.
“Your board.”
She went silent.
For months, I’d noticed unusual changes inside her company.
Executives leaving unexpectedly.
Quarterly numbers being revised.
A major acquisition announced despite concerns from several analysts.
I hadn’t accused anyone.
I simply started asking questions.
Then my investment manager discovered that someone had been attempting to move my voting rights.
That was when I separated my assets from the family’s influence.
My sister shook her head.
“So you knew something was wrong.”
“I suspected something was wrong.”
“And you didn’t tell me?”
“You would’ve called it jealousy.”
She looked away.
Then her assistant interrupted.
“Ma’am, the emergency meeting has started.”
My sister stared at the phone.
“We’re not even there.”
“They started without us.”
That was strange.
Her company had strict board procedures.
Nobody should have been able to call an emergency meeting without the chairman.
My phone buzzed.
I looked down.
A message from my investment manager.
DO NOT ENTER THE BOARDROOM.
I immediately called him.
“What happened?”
“Your sister’s board isn’t investigating the stock sale.”
“What are they investigating?”
He hesitated.
“Your voting shares.”
My stomach tightened.
“Why?”
“Because the company claims your shares were pledged as collateral for a private loan.”
I stared at the screen.
“I never pledged them.”
“I know.”
Then he sent me a document.
My signature appeared on a loan agreement.
I stared at it.
The signature looked real.
But I knew I hadn’t signed it.
My sister walked closer.
“What is that?”
I showed her.
She read the first page.
Then the second.
Her expression changed.
“That lender…”
“What?”
“That company belongs to our CFO.”
Silence.
Her assistant whispered:
“But why would the CFO use your shares?”
My investment manager called again.
I answered.
“We found something else.”
“What?”
“The $250 million sale wasn’t initiated by your account.”
“Then who?”
“It came from the company’s internal securities administrator.”
My sister stepped backward.
Someone inside her company had used corporate authority to sell my shares.
And there was only one reason they would do that.
They needed the stock price to fall.
Then the assistant screamed.
“Ma’am!”
Everyone turned.
She was staring at the trading screen.
“The company just announced an emergency disclosure.”
My sister grabbed the phone.
The headline appeared:
MAJOR SHAREHOLDER LIQUIDATION LINKED TO INTERNAL FINANCIAL REVIEW.
Below it was another line.
CEO UNDER BOARD INVESTIGATION.
My sister’s face went completely white.
She looked at me.
“I swear I didn’t know.”
I believed her.
But then her phone received one final message.
Stop looking into the CFO, or the next sale will be personal.
And suddenly, this wasn’t just about money anymore.
My sister stared at the message.
“Personal?”
I nodded.
“Don’t respond.”
She looked at me.
“What do we do?”
“For once,” I said, “we tell the truth.”
She swallowed.
The assistant immediately called the company’s general counsel.
Within minutes, lawyers were involved.
The emergency board meeting was temporarily suspended while the trading activity was reviewed.
But the damage had already happened.
The stock had fallen sharply.
Investors were demanding answers.
Employees were calling executives.
News outlets were asking whether the company had concealed financial problems.
And my family Thanksgiving had turned into an impromptu corporate crisis.
My sister sat across from me.
“Tell me everything you know.”
I looked at her.
“I don’t know everything.”
“Then tell me what you suspected.”
I explained what my investment manager had discovered over the previous three months.
Several institutional accounts connected to the company had moved unusually large amounts of stock shortly before major announcements.
A consulting firm had received millions in payments.
The firm’s listed officers appeared legitimate, but its ownership records were difficult to trace.
And most importantly, someone had repeatedly attempted to obtain information about my voting shares.
I had separated my assets from the company and placed the shares under independent custody.
But someone had apparently found another route.
My sister listened without interrupting.
Then she asked:
“Why didn’t you tell me?”
I looked at her.
“Because every time I tried to talk about business, you laughed.”
Her face tightened.
“I was joking.”
“You called my investments pocket change.”
She looked down.
“I know.”
The assistant returned from the hallway.
“The general counsel is on the phone.”
My sister answered.
“What did you find?”
“We have a problem.”
“Another one?”
“Yes.”
The lawyer explained that the company had discovered an unauthorized securities instruction.
Someone had used an internal administrator’s credentials to initiate the $250 million sale.
The order had been disguised as a routine portfolio adjustment.
But the transaction had never been approved by the actual shareholder.
Me.
My sister asked:
“Can we identify who entered it?”
“We’re tracing the access logs.”
“Do it.”
The call ended.
I looked at her.
“Who has authority over securities administration?”
She hesitated.
“The CFO’s office.”
My phone buzzed.
My investment manager had sent another message.
Found the source.
Then an attachment appeared.
It contained login records.
The unauthorized order had been entered from a company laptop assigned to the CFO.
My sister closed her eyes.
“Mark?”
Her CFO was Mark Reynolds.
He had worked beside her for seven years.
She trusted him completely.
Or thought she did.
She immediately called him.
No answer.
Again.
Nothing.
Then his assistant called.
“Mark left the building twenty minutes ago.”
My sister stood.
“Where is he going?”
“We don’t know.”
I stopped her.
“Don’t chase him.”
“Why?”
“Because if he knows we’re onto him, he’ll destroy evidence.”
The general counsel agreed.
“She’s right.”
My sister stared at me.
“You just told me not to trust my own CFO.”
“No.”
I looked at her.
“I told you to trust the evidence.”
Within an hour, investigators secured the CFO’s office.
His company laptop was missing.
His desk drawers had been emptied.
But the security team discovered something in the conference room.
A small external drive.
It contained spreadsheets.
Thousands of transactions.
Payments.
Stock movements.
Executive compensation adjustments.
And a list of names.
My sister’s name appeared first.
Mine appeared second.
Under mine was a handwritten note:
REMOVE VOTING CONTROL BEFORE LIQUIDATION.
My sister read it twice.
“Liquidation?”
The general counsel explained.
Someone had planned to force a large stock sale, push the share price down, and then acquire shares cheaply through affiliated accounts.
The $250 million transaction wasn’t designed simply to make money from selling.
It was designed to create panic.
The falling stock would damage investor confidence.
The company’s market value would drop.
Then hidden buyers could purchase shares at a discount.
But there was another piece.
The fraudulent loan agreement carrying my forged signature was intended to create the appearance that I had authorized the sale.
If the plan worked, I would become the public scapegoat.
The company could blame me for the collapse.
My sister could claim she had been misled.
And the real perpetrators could buy the company at a much lower valuation.
My sister looked horrified.
“They were going to make it look like you attacked me.”
“Exactly.”
She sat down.
“I almost believed it.”
“I know.”
She looked at me.
“I accused you.”
“You did.”
“I thought you were trying to hurt the company.”
“I know.”
She wiped her eyes.
“I’m sorry.”
Before I could answer, security reported that Mark had been located at a nearby airport.
Investigators intercepted him before he boarded his flight.
The external drive, transaction records, and access logs became critical evidence.
Under questioning, Mark eventually admitted that he had worked with two outside investors who wanted to gain control of the company.
He had used internal credentials to manipulate shareholder records and securities instructions.
He also admitted creating the fraudulent loan document with a forged version of my signature.
But he insisted my sister had not been part of the scheme.
The investigation confirmed that.
She had been careless about internal controls, but there was no evidence she had knowingly authorized the fraudulent transactions.
The company spent months repairing the damage.
The questionable stock sale was reviewed by regulators and the relevant financial institutions.
The board replaced several senior executives.
The company’s internal security systems were rebuilt.
Independent oversight was added to major shareholder transactions.
And my shares?
They remained mine.
The $250 million sale was not treated as a legitimate decision by me.
My investment firm worked with the appropriate authorities to document that the order had been unauthorized.
The market eventually stabilized, but the company never returned to exactly what it had been.
Too much had changed.
My sister remained CEO for a time, but she voluntarily gave up some of her control and accepted a stronger independent board structure.
Months later, she invited me to dinner.
Not Thanksgiving.
Not a shareholder meeting.
Just dinner.
She looked different without the boardroom around her.
“I owe you something,” she said.
I smiled.
“What?”
“An apology.”
“You already gave me one.”
“Not the important one.”
She took a breath.
“I spent years thinking that because I succeeded publicly, I was more successful than you.”
I didn’t interrupt.
She continued.
“I mocked your investments because I thought they were small.”
“They weren’t small.”
“I know.”
She smiled sadly.
“You were just quiet.”
I nodded.
“That was the mistake.”
“What?”
“Everyone thought silence meant I didn’t know what I was doing.”
She laughed softly.
“Apparently, you knew exactly what you were doing.”
“Sometimes.”
We sat quietly.
Then she asked:
“Do you still invest?”
I smiled.
“Of course.”
“Still little investments?”
I raised an eyebrow.
She laughed.
“Sorry. Bad joke.”
I shook my head.
This time, I laughed too.
The Thanksgiving insult had lasted less than a minute.
The consequences lasted months.
But the most important thing wasn’t the $250 million sale.
It wasn’t the falling stock.
It wasn’t even exposing the people who had tried to manipulate the company.
It was realizing that I no longer needed to prove anything at the family table.
My sister had once measured success by titles, stock prices, and the size of an investment account.
I had learned to measure it differently.
By independence.
By knowing when to walk away.
And by never confusing someone’s opinion of you with the actual value of what you’ve built.
At the next Thanksgiving, nobody mentioned my “little investments.”
My mother asked about my business.
My father asked about my plans.
And my sister simply smiled when I sat down.
This time, there was no laughter at my expense.
Just a quiet understanding.
They finally knew the truth.
I had never been the person at the table with the least power.
I had simply been the one who never needed to announce it.