My phone vibrated against the steering wheel, flashing a notification that froze the blood in my veins: Flagged Activity on Account Ending in 4092. Action Required.
I pulled into a gas station parking lot, my heart hammering against my ribs. Dad had been in a memory care facility for three years, succumbing slowly to severe Alzheimer’s. My older brother, Mark, had taken total control of Dad’s finances from day one. He told us Dad was broke. He showed us spreadsheets claiming the $7,800-a-month facility fees had completely wiped out Dad’s life savings. To keep Dad in a decent place, my two sisters and I had been sending Mark $600 each month without fail. Meanwhile, Mark suddenly had enough money to buy a brand-new Ford F-250 and remodel his kitchen. When we asked, he claimed he was taking on extra consulting work. We trusted him. He was the eldest son, the dutiful caretaker.
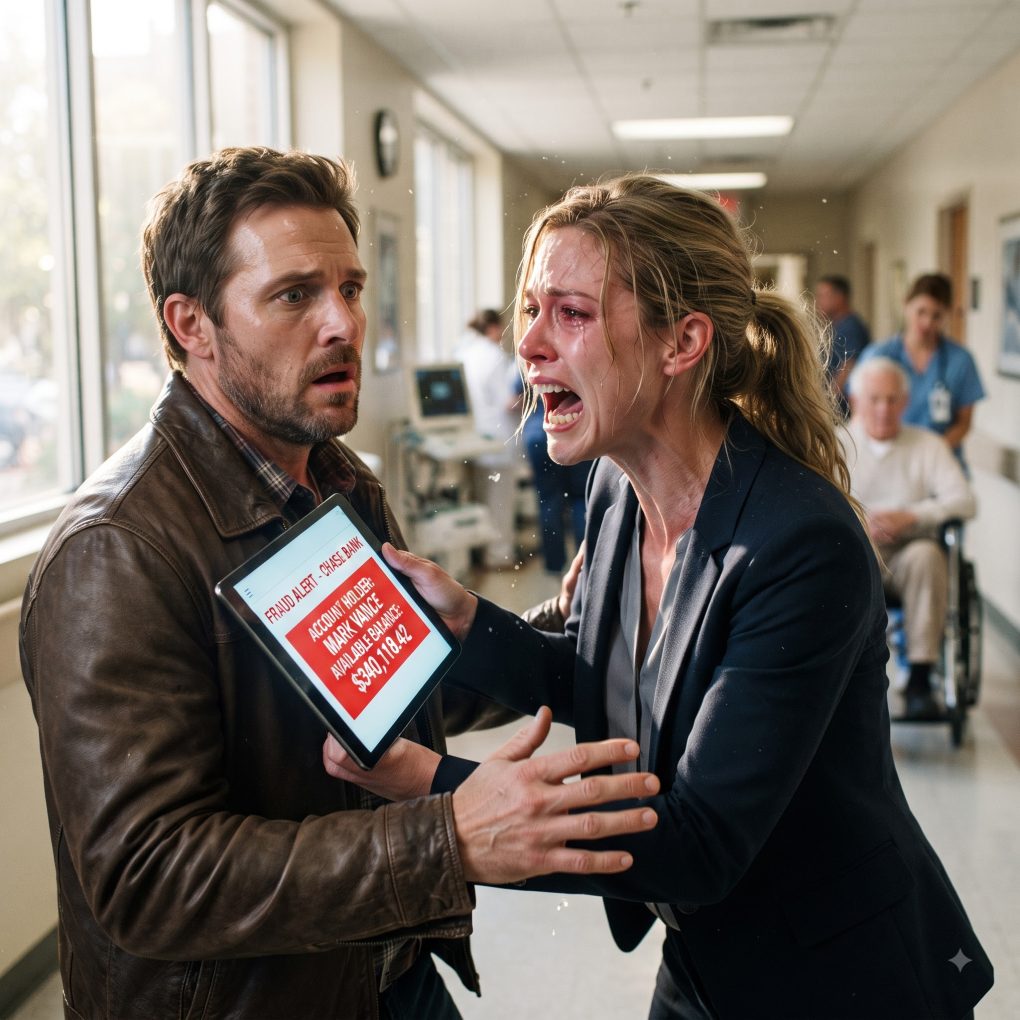
I opened the banking app, using the emergency administrative access Dad had assigned to me years ago before his diagnosis. The notification wasn’t a glitch; it was a fraud warning triggered by an attempted wire transfer of $50,000 to an offshore entity. But it wasn’t Dad’s old checking account. It was a high-yield commercial account registered at Chase Bank under a single name: Mark Vance.
Below the name, the current available balance stared back at me in cold, unforgiving digits: $340,118.42.
My hands shook violently as I took a screenshot. $340,000. That wasn’t just saved money; that was Dad’s entire home sale equity from 2021—money Mark swore had gone directly to the nursing home’s corporate escrow. For thirty-six months, Mark had been hoarding Dad’s real fortune in a private account, while draining $1,800 a month from his own siblings under the guise of elder care expenses.
I immediately called the auditor listed on the notification. Five minutes into the call, the auditor revealed something even worse. “Mr. Vance, this account wasn’t just holding funds. It’s been receiving monthly deposits from a third-party trust account registered under your father’s social security number—an account that has been actively drawing federal assistance for low-income seniors.”
Mark wasn’t just stealing from us; he was committing federal benefits fraud using Dad’s identity.
Just as the auditor was explaining the wire transfer attempt, my call-waiting chimed. It was Mark. I switched lines, forcing my voice to stay level. “Hey, Mark.”
“Hey,” Mark said, his tone unusually tense. “I need you to transfer your monthly $600 right now. The nursing home called. Dad’s account is overdrawn, and they’re threatening to discharge him by tonight.”
A chilling text from an unknown number arrived seconds later, proving that $340,000 wasn’t just stolen cash—it was the buy-in for a dangerous secret Mark thought he had buried forever.
“They’re threatening to throw Dad out onto the street, Sarah,” Mark urged, his voice tight with fake panic over the phone. “I’m at the facility now. The supervisor is standing right in front of me with the discharge papers. Just Venmo me the six hundred bucks so I can clear this up.”
I stared at the Chase account balance on my tablet while holding the phone to my ear. $340,118.42 sitting in his personal account, and he was still trying to squeeze a few hundred dollars out of me by using our dying father as emotional leverage.
“Where are you exactly, Mark?” I asked softly, stepping into my car and locking the doors.
“I told you, I’m at the Oakridge Senior Living center,” he lied seamlessly. “The front desk is breathing down my neck.”
“That’s strange,” I replied, feeling a cold surge of rage. “Because I just called Oakridge billing ten minutes ago to verify Dad’s insurance. They told me Dad’s room has been fully paid six months in advance by a state Medicaid subsidy program. In fact, they said they haven’t billed our family a single dime since last November.”
Silence slammed over the line. The background noise on Mark’s end—which sounded like a crowded coffee shop, definitely not a nursing home lobby—instantly cut out as he pulled the phone away from his mouth.
“What are you talking about?” Mark finally muttered, his tone shifting from frantic brother to cold predator. “Who told you that?”
“The forensic auditor at Chase, Mark,” I said, my voice trembling with suppressed anger. “The one who flagged an attempted $50,000 offshore wire transfer from an account under your name. The account holding three hundred and forty thousand dollars of Dad’s money while you forced me and the girls to pay for your truck.”
Mark didn’t stammer. He didn’t apologize. Instead, a low, bitter laugh came through the speaker. “You think you know what’s going on, Sarah? You think I kept that money to buy a truck? You have no idea what Dad left behind.”
“You stole his money and drained ours!” I screamed.
“Dad was broke when he went into that home, Sarah!” Mark snapped, dropping all pretense. “That money in the account isn’t Dad’s savings. It’s hush money from his former business partners. Dad didn’t just run a logistics firm in the nineties. He was laundering cash for a private investment group in Chicago. When his dementia started getting bad, those partners realized he was a liability. They set up a payoff trust to keep him comfortable and keep his mouth shut. I found out about it three years ago when I took power of attorney.”
My heart stopped. “What?”
“If you go to the police, or if that auditor files a report with the IRS, that entire trust gets frozen, and the people behind it will know Dad’s finances are being investigated,” Mark whispered, his voice trembling with genuine terror now. “They don’t care that Dad has Alzheimer’s. They care about paper trails. That fifty-thousand-dollar wire wasn’t me stealing—it was me trying to pay off the auditor who found the account last week before he blew the whistle.”
Just as Mark finished speaking, my phone chimed with a incoming secure email alert from Dad’s primary attorney. Attached was a document Mark didn’t know existed: a revised living trust signed by Dad four years ago, naming a third beneficiary neither of us had ever heard of.
I stared at the legal PDF loading on my screen. The document was titled The Vance Family Irrevocable Asset Protection Trust, dated exactly four years ago—six months before Dad’s official Alzheimer’s diagnosis.
I stepped out of my car, walked straight into the local police precinct lobby in downtown Columbus, and sat on a wooden bench, listening to Mark breathe heavily over the speaker.
“Mark,” I said, keeping my tone dead pan. “Who is Julian Vance?”
The silence on the line was deafening. I heard Mark inhale sharply, followed by the muffled sound of a car door slamming shut. “Where did you see that name?”
“It’s on Dad’s true trust document,” I read off my screen. “The one filed with the county probate court, not the fake one you printed out for us at Christmas. Dad didn’t leave his estate to you, me, and the girls. He named Julian Vance as the primary trustee and beneficiary of a two-million-dollar annuity policy.”
“Sarah, hang up the phone and meet me,” Mark pleaded, his voice cracking. “Don’t read any further. You don’t understand what Dad did.”
“I understand completely,” I said, flipping through the attached pages. “You told me Dad was laundering cash for Chicago mobsters to hide your own theft. You made up an insane criminal story because you thought I’d be too terrified to look into the bank accounts.”
The truth was right there in black and white. There were no mobsters. There was no secret offshore criminal syndicate threatening our family. That entire story was a desperate, psychological smoke screen invented by Mark to stop me from digging into the Chase account.
Julian Vance was our half-brother—a son Dad had from a relationship prior to marrying our mother. Dad had spent the last decade of his clear-minded life trying to make amends with Julian, setting up a structured annuity to support Julian’s medical care for severe cerebral palsy.
When Dad’s memory began to fail, Mark seized control of the power of attorney. Mark discovered the $340,000 remaining from the sale of Dad’s house—money explicitly earmarked by the trust to fund Julian’s care facility and supplement Dad’s private nursing care. Mark hid the existence of the trust from the rest of us. He redirected Dad’s care to state-subsidized Medicaid by falsely declaring Dad destitute, moved the $340,000 into his own private commercial account, and concocted the story about the facility costing $7,800 a month so he could extract $1,800 every month from his three siblings.
The $50,000 wire transfer that flagged the bank fraud alert wasn’t a payoff to a secret entity—Mark was trying to move the money out of state because he realized the county probate court was initiating a routine four-year audit of Dad’s trust accounts.
“You manufactured an entire conspiracy because you couldn’t admit you stole from a disabled brother and squeezed your own sisters dry,” I whispered, tears of rage hot against my cheeks.
“Sarah, listen to me,” Mark begged, his composure completely shattered. “I was drowning in debt! My business went under during the pandemic. I was going to lose my house! I was going to put the money back once my real estate deal went through. I was keeping Dad safe! The Medicaid facility is fine!”
“You put Dad in a state-funded ward while you bought a luxury truck with money you stole from us,” I said bitterly. “And you let Julian’s care facility go unpaid for six months. They were about to file a lien against Dad’s estate.”
“Please, Sarah. We’re family. If you hand those bank statements to the auditor, I’m going to prison. Think about my kids.”
“I am thinking about family,” I replied. “I’m thinking about Dad, who worked forty years to make sure all his children were taken care of. And I’m thinking about Julian.”
I didn’t wait for him to respond. I hung up the phone, walked up to the duty officer at the front desk, and handed over my tablet along with the folder of printed financial records, the fraud alerts, and the certified probate trust documents.
The investigation moved with terrifying speed once the financial crimes unit got involved. Federal investigators audited every account tied to Mark’s name. Within three weeks, the state froze all of Mark’s assets, including his home equity and his newly purchased truck.
Because Mark had falsified state assistance forms to get Dad onto Medicaid while holding hundreds of thousands of dollars in hidden accounts, he was charged with grand larceny, elder financial abuse, and state welfare fraud. Facing overwhelming documentary evidence, Mark accepted a plea bargain six months later. He was sentenced to forty-two months in a state correctional facility and ordered to pay full restitution to Dad’s estate and to us.
Using the recovered funds, my sisters and I immediately transferred Dad to a top-tier private care facility closer to my home, where he spent his final days surrounded by genuine comfort and dignity. We also established contact with Julian’s legal guardians, ensuring his annuity payments were permanently secured under a court-appointed independent trustee.
Mark thought he could use fear, lies, and family loyalty as weapons to cover his greed. But in the end, paper trails don’t lie—and justice finally brought light to the dark web of deception he built.