“Rachel, I want a divorce.”
Evan said it before I had even taken off my coat.
His sister Melissa was sitting at our kitchen island with a glass of my wine in her hand, watching me like she had bought tickets to the show. Evan stood beside her with his arms folded, jaw tight, wearing the expression he used whenever he had already decided I was the problem.
I looked from him to Melissa. “You’re sure?”
He blinked. I think he expected tears, bargaining, maybe some desperate speech about eleven years of marriage.
Instead, I set my purse on the counter.
“Yes,” he said. “Melissa helped me see how controlling you’ve become.”
That almost made me laugh.
Controlling.
For six years, I had paid the mortgage on our house outside Raleigh, covered Evan’s health insurance while he bounced between “business opportunities,” paid Melissa’s car note after her divorce, kept her utilities from being shut off twice, and covered the private-school tuition for her sixteen-year-old son, Tyler.
The latest tuition installment was $11,000.
Every time I tried to set a boundary, Melissa told Evan I was using money to “keep the family obedient.”
Now he nodded along as she said, “This is healthier for everyone.”
I pulled out my phone.
Evan’s expression changed. “What are you doing?”
“Accepting your decision.”
I opened our household account, removed my personal checking account as the backup funding source, then canceled every automatic payment that belonged to Melissa or Tyler. Her electric bill. Her SUV. Her phone plan. The monthly payment on a personal loan I had guaranteed after her ex-husband left.
Then I logged into Tyler’s school portal and canceled the scheduled $11,000 tuition payment due Friday.
Melissa stood so fast her stool scraped the floor.
“You can’t do that.”
I looked at her. “Why not?”
“That’s Tyler’s education.”
“And you’re his mother.”
Evan stepped toward me. “Don’t punish a kid because you’re angry at me.”
“I’m not punishing anyone. You asked to separate our lives. I’m separating them.”
His face hardened. “You know Melissa can’t cover all that right now.”
“Then maybe the two of you should have discussed the budget before discussing my divorce.”
The room went silent.
I packed a bag that night and checked into a hotel downtown. By morning, I had contacted a divorce attorney and moved my direct deposit into an account Evan had never touched.
For the next two days, my phone exploded.
Melissa called seventeen times. Evan sent messages accusing me of being vindictive, cruel, unstable, heartless.
I answered none of them.
On the third afternoon, while I was sitting in my attorney Claire Donovan’s office, my phone rang from an unfamiliar number.
It was the fraud department at my bank.
The woman verified my identity, then asked a question that made every muscle in my body lock.
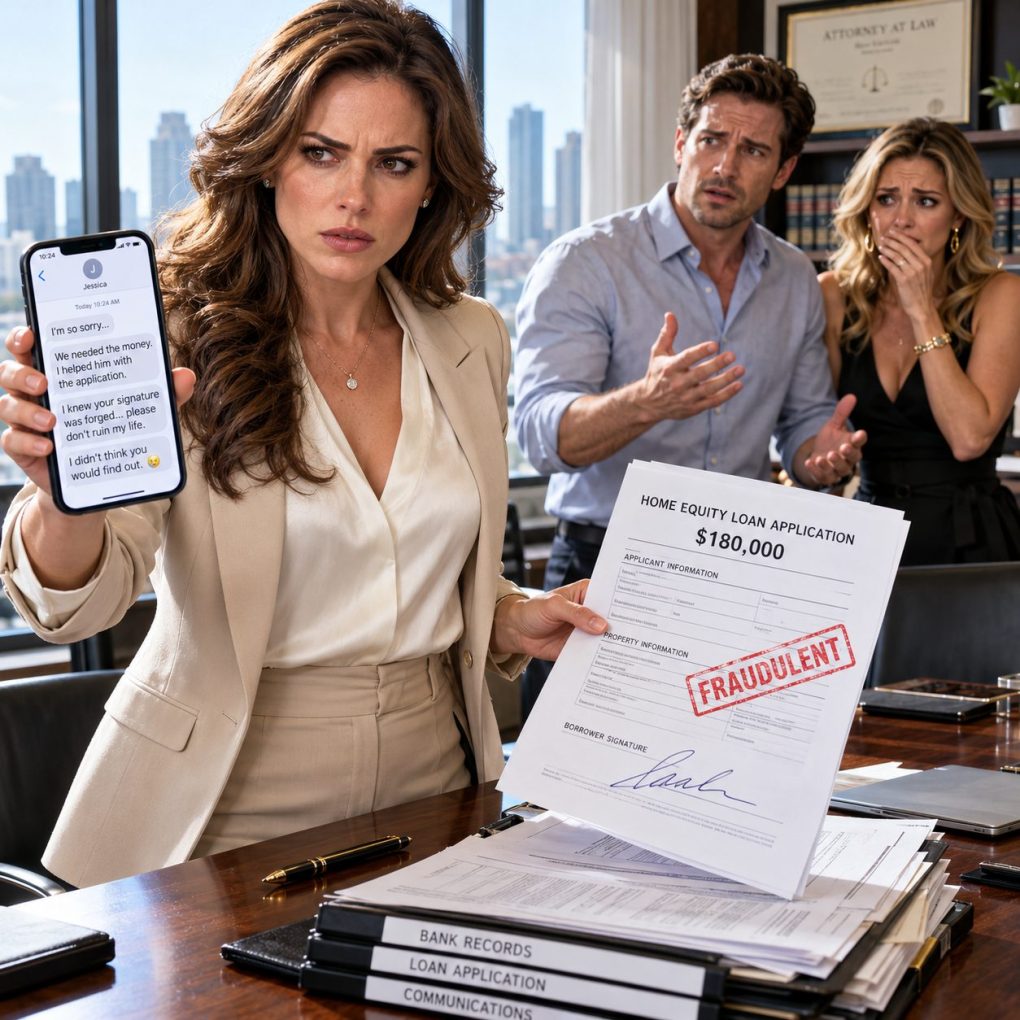
“Mrs. Carter, did you authorize a $180,000 home-equity line of credit yesterday?”
I stared at Claire.
“No.”
There was a pause.
Then the banker said, “We have an electronic application bearing your signature.”
Claire held out her hand for the phone.
Before I could pass it to her, another message appeared on my screen.
It was from Melissa.
You should have just paid the tuition. Now Evan had to fix this another way.
That message changed everything. Until that second, I thought I was dealing with an angry husband and an entitled sister-in-law. I had no idea the canceled tuition payment had exposed something they had been planning long before Evan ever said the word divorce.
Claire read Melissa’s message twice, then told me not to respond.
The bank froze the home-equity application while its fraud team reviewed the documents. According to the representative, the request had been submitted against the house Evan and I owned jointly, but the proceeds were supposed to be deposited into an account I didn’t recognize.
Claire asked for the account number.
When the banker read the last four digits, my stomach dropped.
I knew that account.
It belonged to Melissa.
Suddenly the divorce conversation made less sense, not more.
Evan had spent weeks accusing me of being controlling, but he had also insisted we should “keep things civil” and avoid attorneys. He had suggested we could work out the property division ourselves. At the time, I thought he wanted an easy exit.
Claire saw it immediately.
“He wanted access before you started looking closely.”
That evening, Evan finally left a voicemail that didn’t sound angry. It sounded scared.
He said there had been a misunderstanding. He said Melissa had filled out “some paperwork” because Tyler’s school deadline was approaching. He said no money had actually moved, so I was turning nothing into a criminal accusation.
But $180,000 was not tuition.
Claire obtained the application packet the next morning.
My name was typed beside a digital signature. My annual income was listed correctly down to the dollar. My Social Security number was correct. So was the approximate value of the house.
Someone had access to information Melissa should never have had.
Then we reached the purpose-of-funds section.
The application said the money was for home renovations.
Attached was an estimate from a construction company I had never heard of.
Claire searched the company registration.
The owner was Melissa’s boyfriend, Shane.
That was the first real twist.
The second was worse.
Buried in the bank’s activity log was the email address used to begin the application.
It wasn’t Melissa’s.
It was Evan’s.
I called him once.
He answered immediately.
“Rachel, please listen.”
“Did you start the loan application?”
Silence.
That silence told me more than any confession could.
Then he whispered, “It wasn’t supposed to happen like this.”
Claire motioned for me to say nothing else, so I ended the call.
Ten minutes later, Melissa sent another message.
This time there was no sarcasm.
If you report this, you’ll destroy your own husband. Think carefully.
I stared at the screen, furious but strangely calm.
Because she still thought Evan was the person I needed protecting.
She had no idea what Claire had found in the final attachment.
A draft separation agreement dated six weeks before Evan asked me for a divorce.
And in that draft, my husband had already promised Melissa $75,000 from “anticipated marital proceeds.”
The draft agreement was the moment my anger became focused.
For three days, I had been reacting to insults, canceled bills, and a fraudulent loan application. Now I finally had a timeline.
Six weeks before Evan asked me for a divorce, he was already planning what would happen to the money afterward.
Claire enlarged the draft on her monitor. It wasn’t signed, but the language was clear. Evan expected the house to be sold or refinanced, and he had written that $75,000 would be transferred to Melissa after the marital property was divided.
I felt sick.
Not because he wanted to leave me.
Because for six weeks he had kissed me goodbye, asked me to cover Tyler’s tuition, and acted as if our marriage was intact while discussing what he could give his sister after it ended.
Claire told me to save every message and communicate only through counsel.
The bank’s fraud team moved quickly because the loan had not funded. My signature had been inserted electronically, and the authentication trail did not match my devices. The application had been started from our home internet connection on a night I was in Chicago for work.
Evan had been home.
The contractor estimate was just as suspicious. Shane’s company had been created only months earlier, and the $180,000 proposal listed vague “structural renovations” with no plans or permits.
The bank closed the application. On Claire’s advice, I filed a police report so there was a formal record that I disputed the signature and had not authorized the debt.
That was when Evan’s tone changed.
The accusations stopped. The apologies began.
He sent an email saying Melissa panicked when Tyler’s tuition payment disappeared and pressured him to “find another solution.”
But $180,000 was not another solution to an $11,000 school bill.
And none of his explanations mentioned the $75,000.
A week later, Evan requested a meeting through his attorney.
We met in Claire’s conference room.
He looked exhausted.
He said I worked too much. He admitted he resented that I earned more. He said Melissa had spent years telling him I looked down on his family.
Then Claire slid the draft agreement across the table.
“Why did you promise your sister seventy-five thousand dollars?”
Evan stared at it for a long time.
Finally, he told the truth.
Melissa was buried in debt.
She had more than $60,000 on credit cards, unpaid taxes from a failed online boutique, and money she owed Shane after he helped cover her rent. Tyler’s tuition was only the emergency she could no longer hide.
Evan had promised to help her start over after our divorce.
He assumed he would receive enough money from the house to do it.
That assumption was much shakier than he thought. I had purchased the house before our marriage and used separate funds for the down payment. Evan had later been added to the deed during a refinance. Claire explained that the final property questions depended on the documents, contributions, and North Carolina law, not on Evan simply declaring half the equity his.
By the time he applied for the HELOC, he knew the divorce might not produce cash quickly.
So he tried to create cash first.
He insisted he had planned to account for it during the divorce.
I looked straight at him.
“You used my information and signed my name.”
He lowered his eyes. “I panicked.”
“No. You planned.”
Then came the last secret.
Evan’s attorney disclosed that Melissa had spent months convincing him I was preparing to leave first and hide money. She had shown him screenshots supposedly from messages between me and a coworker in Chicago.
They were fake.
The coworker was a married finance director nearly twice my age. Melissa had fabricated messages suggesting I planned to sell the house and move money before Evan could react.
When confronted through the attorneys, she admitted creating the screenshots.
Her goal was simple: make Evan believe I was about to cut him off financially, so he would act first.
That explained his sudden paranoia.
It did not excuse his choices.
He still started the loan application, used my personal information, and planned to give Melissa money from property we had not divided.
When I canceled Tyler’s tuition, they rushed the plan because Melissa’s finances were collapsing.
The consequences were quieter than Melissa had feared, but they were real.
Tyler’s school gave her time to arrange a temporary payment plan. I was relieved for him. He was a kid caught in adult decisions, and I never wanted him punished for that.
But I did not resume paying his tuition.
Melissa sold her SUV and moved into a smaller apartment. Shane ended their relationship after the bank contacted him about the estimate. Through his lawyer, he claimed he had prepared a generic renovation quote without knowing how it would be used.
The bank investigation and police report remained part of the record. Because no loan proceeds were disbursed, the situation did not turn into some dramatic courtroom spectacle. But it could no longer be dismissed as a family misunderstanding.
The divorce took eight months.
Everything became documented. Shared expenses. Accounts. Debts. Property records.
No more informal promises.
Near the end, Evan asked for five minutes alone after mediation.
He stood by the window and said, “Melissa didn’t ruin our marriage by herself.”
I waited.
“I let her convince me you were the enemy because it was easier than admitting how dependent we had all become on you.”
For once, he did not ask me to forgive him or stop the divorce.
He just apologized.
I believed he meant it.
But meaning an apology does not erase a forged signature.
Our final settlement was based on the documented finances and the agreement reached through our attorneys. Melissa received nothing from me. The $75,000 promise vanished because it had never been hers to receive.
On the day the divorce became final, I drove home alone.
The house did not feel empty.
It felt quiet.
For years, I had confused generosity with responsibility. If someone I loved had a financial problem and I could fix it, I did. One bill became five. A favor became an expectation.
Eventually, they stopped seeing my help as help.
They saw it as infrastructure.
The $11,000 tuition payment was never the real reason everything exploded.
Canceling it simply removed the first support beam.
Three days later, I discovered what had been built around my money without my knowledge.
I don’t celebrate Melissa’s financial problems. I don’t celebrate Tyler eventually transferring schools. And I don’t celebrate losing eleven years with a man I once trusted.
But I do not regret agreeing to the divorce.
Evan thought he was removing me from his life.
What he actually removed was my obligation to finance everyone else’s choices.
The morning after the decree, I opened my banking app.
There were no payments scheduled for Melissa’s SUV, her utilities, Tyler’s tuition, or any loan that belonged to someone else.
Just my mortgage.
My bills.
My life.
And for the first time in years, that felt like freedom.