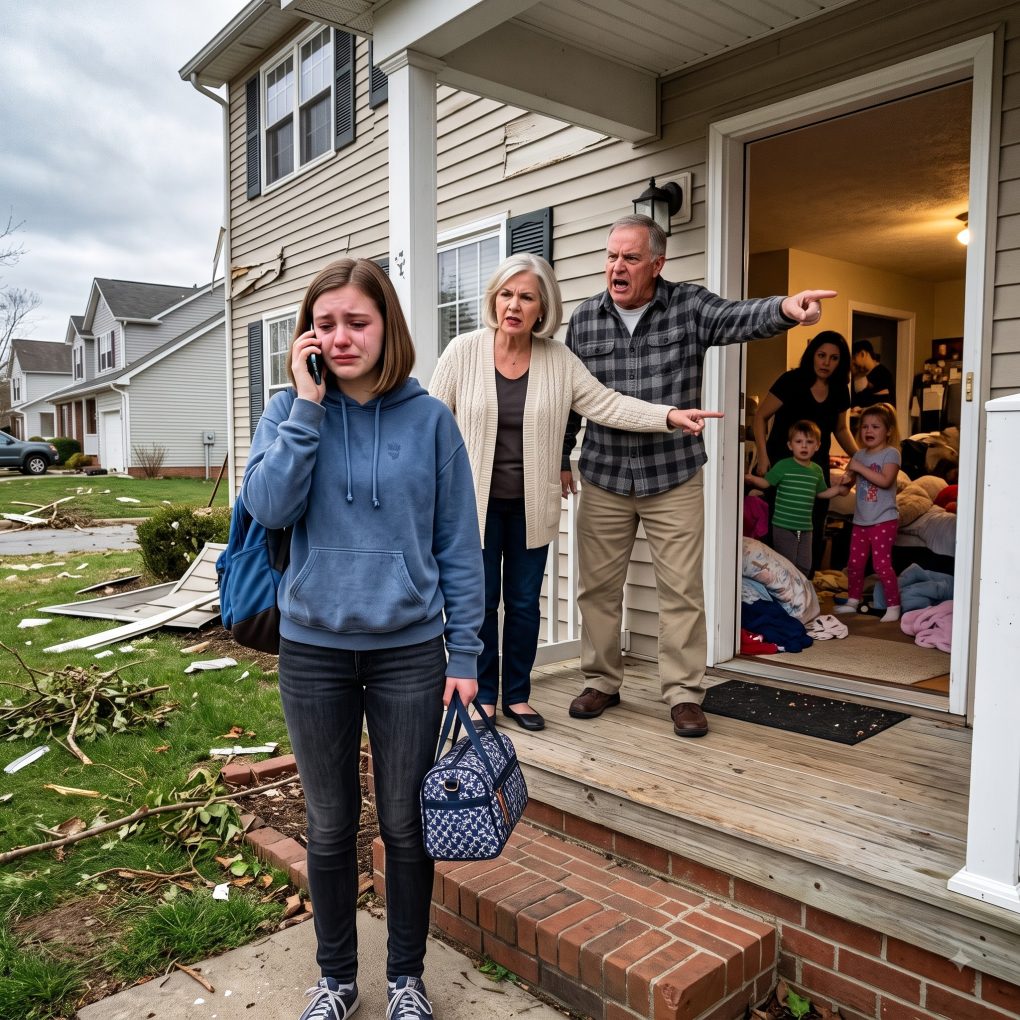
“Mom, they won’t let me inside.”
My daughter Emma’s voice broke over the phone. Behind her, someone was shouting that she needed to get off the porch.
I was in the emergency department, treating people pulled from the wreckage of a tornado. Our house had lost its roof. That morning, my parents had agreed Emma could stay with them across town until I could leave the hospital.
“Put Grandma on,” I said.
My mother took the phone. “There’s no room, Claire. Your sister and the kids are already here.”
My sister, Melissa, and her three children had lived in my parents’ four-bedroom house rent-free for nearly a year.
“You said yes this morning.”
“We thought you’d come with her. We can’t be responsible for a teenager while you play hero.”
I heard Emma say, “Grandma, I can sleep on the couch.”
“Go wait by the curb,” my father snapped.
I called my friend Nina, who lived ten minutes away. She left work, picked Emma up, and sent me a photo of her safe in the passenger seat. Only then could I breathe.
I saved my parents’ texts confirming the arrangement. I saved Emma’s messages, too. Then I called the bank about the automatic transfer I’d been making every month to help my parents keep their house. I told them to stop the next payment.
I didn’t call my parents back.
For the next two weeks, Emma stayed with Nina while I worked shifts and dealt with our damaged house. My mother sent one message: You’re overreacting. My father sent none.
On the fourteenth day, Melissa called six times in a row. I answered the seventh.
“The bank says the mortgage payment bounced,” she said. “Dad’s panicking. What did you do?”
“I stopped paying it.”
She went quiet. Then a man’s voice came through her phone, low and furious.
“Ask Claire what she knows about the second loan.”
I thought I had simply stopped paying for a house where my daughter wasn’t welcome. Then I heard about a loan nobody had ever mentioned to me—and realized my parents might have put much more than their own home at risk.
“The second loan?” I repeated.
Melissa hung up. A minute later, Dad called. I let it go to voicemail because Emma was sitting beside me, staring at the phone. She had been afraid I’d send her back if Nina grew tired of hosting us. I told her that would never happen.
Dad’s message said, “Don’t discuss family finances with your sister. Call me alone.”
That night, I opened the folder I kept after helping my parents refinance three years earlier. I had given them money for closing costs, then started covering part of their mortgage while Dad recovered from surgery. I had never signed a loan. I called the county recorder’s office the next morning and requested copies of anything recorded against their property.
Two documents arrived by email. The original mortgage was there. So was a newer home equity loan, recorded eight months earlier. My name appeared on an attached sheet labeled “family contribution acknowledgment.” I had never seen it. Beneath my typed name was a signature that looked like mine from a distance.
I took it to an attorney. She pointed to the date. On that day, I had been working a twenty-four-hour hospital shift. My badge records could prove it. But she warned me that the attachment alone didn’t show exactly what the lender had relied on. We needed the lender’s file.
Meanwhile, Mom began calling Emma directly. “Tell your mother she’s going to make us homeless,” she said in a voicemail. I saved it, blocked their numbers on Emma’s phone, and told her she didn’t owe anyone a reply.
Three days later, my attorney obtained the application packet. The loan proceeds had gone into a joint account held by my parents. Within forty-eight hours, most of the money had been transferred to a business account bearing Melissa’s name.
I drove to Nina’s after my shift and found Emma at the kitchen table. She was pale. “Aunt Melissa came here,” she said. “Nina wouldn’t let her in. She said she only wanted the envelope Grandma gave me before the tornado.”
Emma pulled it from her backpack. I hadn’t known it existed. Inside was a photocopy of my driver’s license, an old pay stub, and a handwritten note from my mother: Keep these somewhere Claire won’t look.
Before I could ask why my mother had put those things in my daughter’s bag, my attorney called.
“Claire,” she said, “the lender just sent one more page. They listed your house as additional collateral.”
I looked at Emma. The only house I owned was the one the tornado had torn open.
“Can they take our house?” Emma asked.
“I don’t know yet,” I told her. It was the hardest honest answer I had ever given her.
My attorney, Rachel, asked me to photograph the envelope exactly as Emma had found it and put the originals away. The next morning, she reviewed the lender’s entire file. The page naming my house was a proposed collateral schedule. It had my address and an estimated value, but no recorded lien against my property. Rachel checked the county records herself. There was nothing attached to my deed.
I called Emma as soon as I knew. “Our house isn’t part of their loan,” I said. She cried anyway. So did I. For one night, she had thought the place we were trying to repair could be taken because Grandma had slipped papers into her backpack.
The rest of the file explained why those papers were there. My parents had applied for a larger loan than their house alone could support. They told the lender I would join the deal later, offering my house as extra security. The forged acknowledgment and copied pay stub were meant to make that promise look credible. The lender had approved a smaller amount secured only by my parents’ home, pending further verification if they wanted more.
Melissa had already spent the smaller loan. Her business account was for a party rental company she had opened without telling me. She had paid deposits on equipment, signed a warehouse lease, and counted on another advance to keep it running. My monthly contribution had been covering the mortgage while their new loan payment came due. When I stopped my transfer, there wasn’t enough in their account for both.
Rachel helped me send a written fraud report to the lender, along with my badge records and a statement that I had never signed or authorized any use of my information. She also advised me to file a police report and place a fraud alert with the credit bureaus. The lender confirmed it would not accept me as a borrower or use my property without verified consent. It opened an investigation into the application.
That afternoon, Dad appeared outside Nina’s house. Nina kept the door shut and called me. I was at the hospital, so I asked her to call the police if he refused to leave. She did. By the time an officer arrived, he was sitting in his car at the curb. He told the officer he just wanted to speak to his granddaughter. The officer told him to go. Nina saved the doorbell video.
Emma heard none of it until I got home. I had promised to tell her what affected her, so I explained that Grandpa had come by and had left without seeing her. “You didn’t ask him to come?” she said. “No.” She nodded and asked if she could keep staying with Nina until our place was fixed. I said yes.
Two days later, Mom called from Melissa’s number. I answered with Rachel beside me on speakerphone. Mom admitted she had put the envelope in Emma’s backpack before the tornado, when Emma had visited after school. “It was just safekeeping,” she said. “Your father thought you’d lose those papers if your house was damaged.”
“You took my license copy from the refinance folder months before the tornado,” I said. “What did you need Emma to keep safe then?”
Silence. Then Dad took the phone. “We were going to tell you about the loan after Melissa got on her feet.”
Rachel asked a simple question: “Who signed Claire’s name?”
Dad said nothing. Mom began crying. Melissa shouted in the background that she hadn’t touched the paperwork. Rachel ended the call and preserved the recording. I had told them at the start that she was listening and recording.
The lender’s investigator later matched the application’s upload to the computer my parents used at home. That didn’t identify the person who wrote the signature, and I refused to guess. What mattered immediately was that the lender removed the false information from its file, denied any further advance, and sent written confirmation that I owed nothing on the loan. The police continued looking into the signature and the documents. I gave them everything I had, including the envelope and Emma’s account of when Grandma handed it to her.
My parents still owned their house, but they had to deal with the payments themselves. Melissa closed the party rental business and moved out with her children to a smaller apartment. I never asked where the equipment went. I was done solving financial emergencies they had created and hidden from me.
A week before repairs were finished, Dad mailed a letter. He wrote that turning Emma away had been wrong. He also wrote that he’d assumed I would forgive them once I understood how much pressure Melissa was under. I read it twice, looking for a sentence that said he had been worried about Emma standing outside after a tornado. There wasn’t one.
I let Emma decide whether to read it. She chose not to. “I remember what he said at the door,” she told me. “I don’t need to know what he says now.”
When our house was safe to enter again, Emma and I carried in our bags together. A contractor had patched the roof, and the living room still smelled like fresh paint. Emma set her backpack on the couch and asked whether Nina could come over for dinner.
“Of course,” I said.
Nina arrived with takeout and an extra folding chair. We ate off paper plates because most of our dishes were still boxed. Emma laughed when Nina complained about the terrible restaurant fortune cookies. It was the first easy laugh I’d heard from her since the storm.
I had spent two weeks worrying that stopping a payment would tear my family apart. But the moment that stayed with me was much smaller: my daughter setting down her bag, knowing the door would open for her.