My parents waited until Sunday dinner to tell me they had changed their estate plan. Dad pushed a folder across the table and said their $780,000 house outside Denver would go entirely to my younger brother, Kevin. I would receive nothing from the property. Mom smiled gently and said, “You’re doing fine, Amanda. Kevin needs security more than you do.”
Kevin was thirty-four, unemployed, and living in their basement. I was forty, worked as a project manager, and owned a modest condo. I didn’t argue. Their house belonged to them. If they wanted Kevin to inherit it, that was their decision.
What bothered me was the reason.
For six years, “doing fine” had meant quietly paying expenses whenever my parents couldn’t. I covered property taxes, homeowners insurance, emergency plumbing repairs, a furnace replacement, and several mortgage shortfalls before the loan was finally paid off.
Kevin contributed nothing.
Still, I closed the folder and said, “Okay.”
Less than twenty-four hours later, Mom called while I was at work. She sounded irritated. “The property tax installment is due Friday. Make sure you transfer the money before then.”
I thought I had misheard her.
“You just told me the house belongs entirely to Kevin eventually.”
“That doesn’t change the taxes,” she said. “You’ve always handled those.”
I opened my banking app.
Six years of transfers appeared on the screen. I downloaded the records and started adding them. Property taxes, insurance, repairs, mortgage assistance, utilities during Dad’s surgery, and maintenance totaled more than $71,000.
Then I opened the automatic payment scheduled for Thursday.
$6,840.
I pressed Cancel.
Mom became silent when I told her.
Finally she said, “You’re punishing us because you didn’t get the house.”
“No. I’m accepting your decision. You decided Kevin should receive the asset. He can start learning what it costs.”
She immediately told me Kevin had no money.
“That sounds like something the future homeowner needs to solve.”
That evening, Dad called me selfish.
Then Kevin texted.
Are you seriously making Mom and Dad lose the house over six grand?
I took a screenshot of the canceled payment beside six years of bank records.
Nobody had noticed how much I contributed while the money kept arriving automatically.
They noticed within one day of it stop
The house was never in immediate danger of being lost. The tax deadline was approaching, but my parents still had options, savings, and time to arrange payment. Kevin’s message was emotional exaggeration.
I explained that once.
Then I stopped defending myself.
Mom called the next morning and suggested a compromise. I could continue paying property taxes while Kevin covered utilities after he eventually found work.
I asked when he planned to find work.
She said I was being cruel.
Kevin had left three jobs in four years because he disliked management, schedules, or commuting. Every time, my parents described the unemployment as temporary.
I had quietly financed the consequences.
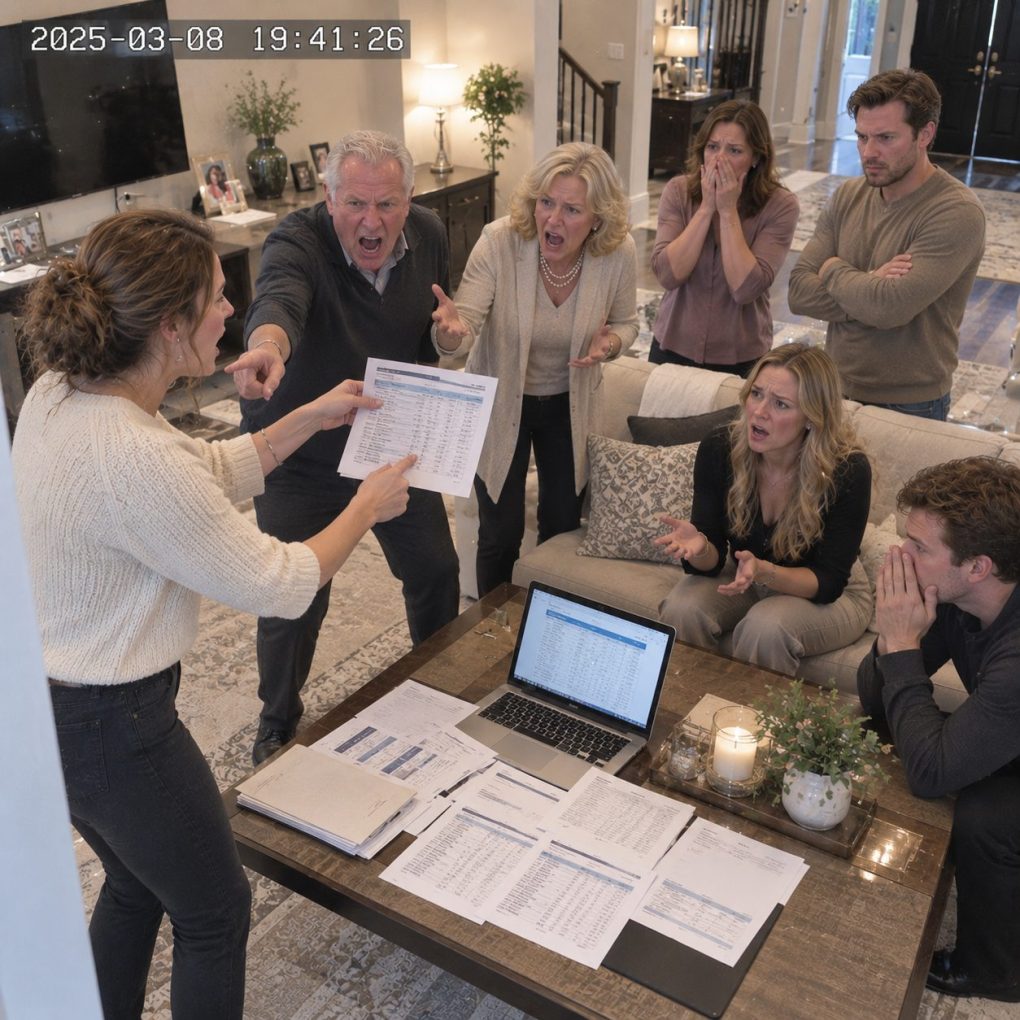
That afternoon, I created a spreadsheet covering everything I had paid since 2020.
The total was $71,438.
I sent it to my parents and Kevin with one sentence: These payments end now.
Dad called twenty minutes later.
He had never realized the amount was that high.
Mom had usually asked me privately, telling me not to worry Dad while he dealt with health problems or retirement.
Some payments had been small.
Others were not.
The $14,600 furnace and HVAC replacement was difficult to overlook.
Dad asked whether I expected repayment.
“No.”
I had given the money willingly at the time.
I wasn’t rewriting history simply because I disliked their estate decision.
But future support was different.
If Kevin was being given the entire house because he needed security, then transferring responsibility along with that security was reasonable.
Dad finally understood the distinction.
Mom did not.
She accused me of keeping score.
I told her the spreadsheet existed only because she had expected my contributions to continue indefinitely while explicitly excluding me from the asset those contributions protected.
Three days later, Kevin surprised everyone.
He applied for several jobs.
Not because he suddenly became ambitious.
Because Dad told him the family arrangement was changing.
Kevin would pay $500 monthly toward household expenses once employed, and he would gradually assume responsibility for taxes, insurance, and maintenance if the house was still intended for him.
Kevin was furious.
For the first time, being the future owner sounded less like winning.
Then he called me.
“You made everything harder.”
“No,” I said.
“I stopped making everything easy.”
My parents paid the property-tax installment from their savings.
Nothing catastrophic happened.
Nobody lost the house.
That fact alone exposed how much unnecessary guilt had been used to keep me paying.
Two months later, Kevin found a warehouse operations job.
The salary wasn’t spectacular, but it was steady.
Dad required him to contribute toward household expenses.
Mom resisted at first.
Eventually, even she admitted Kevin needed to understand the cost of maintaining the property he expected to inherit.
My relationship with my parents remained strained for several months.
I still visited.
I still called.
I simply stopped bringing my checkbook into every family emergency.
When their dishwasher failed, Mom mentioned the replacement price three times.
I recommended a reliable model.
I did not offer to buy it.
Kevin paid half.
That was new.
Six months later, Dad asked me to meet privately.
He said he and Mom had visited their estate attorney again.
I immediately told him not to change the will because of me.
I meant it.
I didn’t want an inheritance awarded as payment for refusing to subsidize them.
Dad said the attorney had raised practical questions about leaving an expensive property entirely to someone who might struggle with taxes and maintenance.
They eventually created a different plan.
I never asked for the details.
Knowing the exact percentages would only restart the argument.
What mattered was that my parents had finally separated two ideas they had treated as identical for years.
I was financially stable.
That did not make my money communal property.
Kevin needed help.
That did not make him permanently exempt from responsibility.
A year after that Sunday dinner, I checked the old spreadsheet again.
For the first time in six years, there were no new entries.
The $71,438 remained where the record ended.
I didn’t regret helping my parents.
I regretted allowing help to become expectation.
Mom believed leaving the house to Kevin was fair because I was “doing fine.”
Maybe she was right about one thing.
I was doing fine.
But the reason I was doing fine was that I worked, budgeted, saved, and accepted responsibility for my own expenses.
Canceling one $6,840 automatic payment didn’t destroy my family.
It simply forced everyone else to start doing the same.