The bank said I owed $623,000 on a mortgage I never signed. Then I discovered the house belonged to my sister. At family dinner, I quietly slid the police report across the table.
The bank employee repeated the number slowly.
“Your outstanding mortgage balance is six hundred twenty-three thousand dollars.”
I gripped my desk. “I don’t have a mortgage.”
There was a pause.
Then she read me an address in Lakewood, Colorado.
My sister Lauren’s address.
For three months, Lauren had been posting photos of her “dream house” online: white kitchen, vaulted ceilings, mountain-view deck, two-car garage. At family dinners, Mom bragged that Lauren and her husband, Kyle, had “finally made it.”
I had even brought them a housewarming gift.
Now a bank was telling me the loan was in my name.
By noon, I had frozen my credit, pulled all three reports, and spoken to the bank’s fraud department. The mortgage had been opened eight months earlier using my Social Security number, income, employer, and a scanned copy of my driver’s license.
The signature looked almost like mine.
The loan officer said the account was already sixty-two days delinquent.
“If this isn’t resolved,” she warned, “foreclosure proceedings could begin.”
My hands went cold.
That evening, I printed the credit report, fraud affidavit, mortgage summary, and the police report I had filed an hour earlier.
Then I drove to my parents’ house for Sunday dinner.
Lauren was already there, laughing over wine.
Mom smiled when I walked in. “Perfect timing. We were just talking about Lauren’s kitchen remodel.”
I sat across from my sister.
Lauren barely looked at me. “You should see the backsplash Kyle picked.”
“I’ve seen enough of the house.”
Her smile faded.
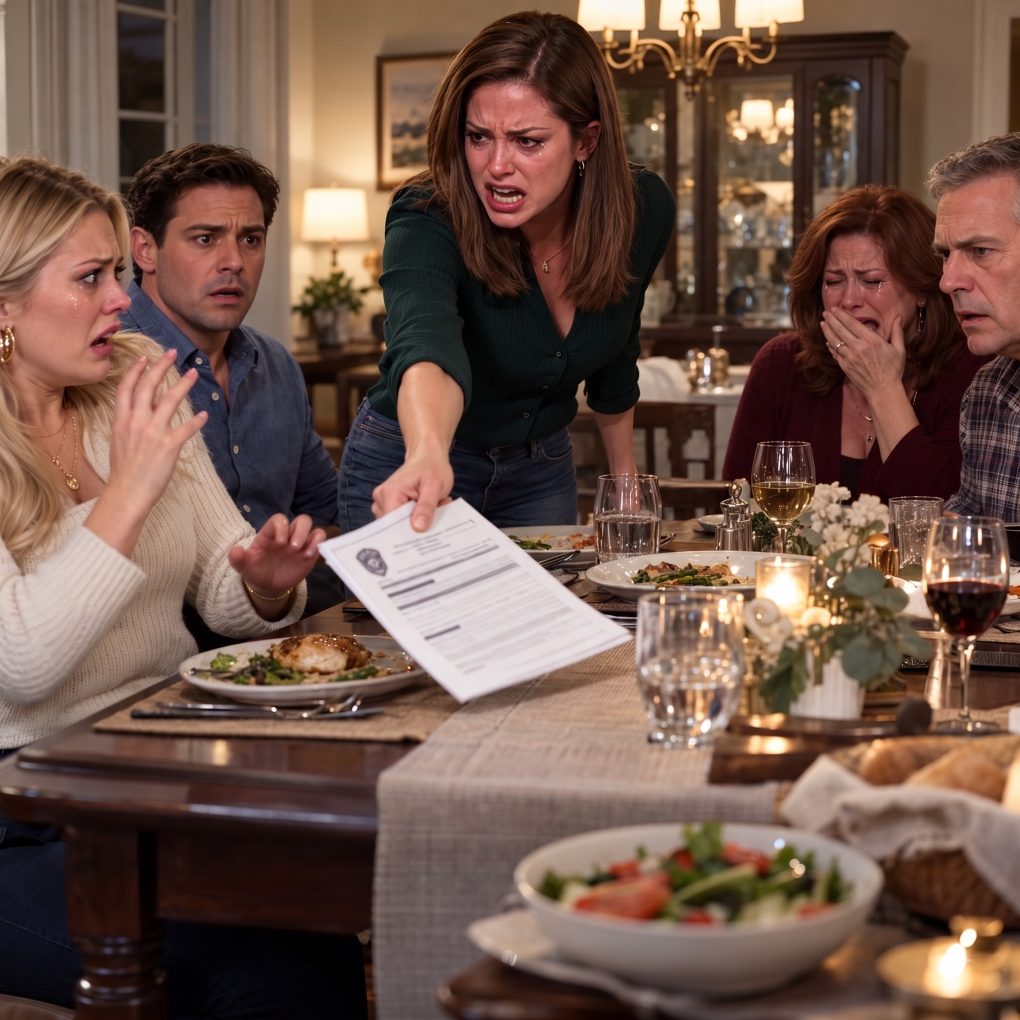
I slid the police report across the table.
The room went silent.
Lauren stared at the page.
Kyle stopped chewing.
Mom’s fork hit her plate.
Dad said, “What is this?”
I kept my eyes on my sister.
“It’s a criminal identity-theft report. Someone used my name to take out a $623,000 mortgage on Lauren’s house.”
Lauren’s face drained of color.
Then Mom whispered, “Emily, don’t do this here.”
That was the moment I knew.
I turned toward her. “You knew?”
“No,” Mom said too quickly.
Lauren pushed back from the table. “This is a misunderstanding.”
“A misunderstanding doesn’t use my Social Security number.”
Kyle muttered, “Lauren, tell her.”
She shot him a vicious look.
Dad suddenly stood.
His face had gone gray.
“Emily,” he said, staring at Mom instead of Lauren. “Before you call anyone else, there’s something you need to know.”
Mom snapped, “Richard, don’t.”
Dad swallowed.
“Your mother didn’t just know about the mortgage.”
He looked at me.
“She helped them get it.”
Mom’s face hardened. “I was trying to help your sister.”
“With my identity?”
Lauren slammed her palm on the table. “Stop saying it like I robbed a bank.”
“You impersonated me for a $623,000 loan.”
Mom started crying, but Dad kept talking.
Three weeks before Lauren closed on the house, she had told Mom her financing had collapsed because Kyle’s business income was too inconsistent. Mom knew I had excellent credit. She also had copies of my tax returns and driver’s license from paperwork I had once left in their home safe.
So she gave them to Lauren.
“I thought you were going to ask Emily first,” Dad said.
Lauren laughed bitterly. “She would’ve said no.”
“Exactly,” I said.
Kyle stared at her. “You told me she already agreed.”
Lauren froze.
The room changed.
Kyle pushed his chair back. “You said Emily was investing in the house and wanted her name kept off the family conversation because she didn’t want Dad asking questions.”
I looked at him. “I never agreed to anything.”
He stood so fast his chair tipped over.
Mom whispered, “Kyle, calm down.”
“No. She had me wire ninety-four thousand dollars from our business account for the down payment.”
Lauren grabbed her purse.
I moved away from the table and took out my phone.
“Don’t leave,” I said. “The detective assigned to the report asked me not to warn anyone, but I think that ship has sailed.”
Lauren’s eyes flashed. “You called a detective on your own sister?”
“You stole my identity.”
She stepped toward me. “If you destroy my life over paperwork, don’t expect this family to forgive you.”
Dad got between us.
Then my phone rang.
It was Melissa Hart from the bank’s fraud unit.
I put her on speaker.
“Ms. Carter,” she said, “we located the closing package. I need to confirm something. Were you physically present at Front Range Title on January nineteenth?”
“No.”
“Did you authorize a remote notarization under the email [email protected]?”
“I’ve never had that email.”
Nobody spoke.
Melissa continued. “Then we have a larger problem. The closing package contains a notarized signature, a video identity verification, and a copy of a temporary Colorado identification card issued in your name.”
My stomach dropped.
A fake ID.
But she wasn’t finished.
“There is also a home-equity line opened six weeks after closing.”
“How much?”
“Forty-eight thousand dollars. Nearly all of it has been drawn.”
Kyle slowly turned toward Lauren.
She backed toward the hallway.
I said, “Where did the money go?”
Lauren said nothing.
Melissa answered instead.
“Our preliminary review shows several transfers to a company called LKM Design Group.”
Kyle went pale.
“That’s not a design company,” he said.
Mom stared at him. “What is it?”
Kyle’s voice cracked.
“It’s Lauren’s LLC.”
Dad closed his eyes.
Lauren suddenly lunged for my phone.
I jerked back, and Dad caught her arm.
“Enough!” he shouted.
For the first time, Lauren looked scared.
Then Kyle said something that made every person at the table go still.
“Emily, you need to check your father’s credit too.”
Dad frowned. “Why?”
Kyle looked at Lauren.
“Because she tried this once before.”
Lauren whispered, “Shut up.”
Kyle shook his head.
“Last year, she asked me how hard it would be to borrow against a house if the owner didn’t know.”
Dad looked at Lauren as if he had never seen her before.
“What did you try to do?”
Lauren grabbed her coat. “Kyle is lying because he’s angry.”
Kyle pulled out his phone.
“No, I’m done covering for you.”
He opened an old message thread and handed the phone to Dad. Months earlier, Lauren had sent Kyle a photo of my parents’ property-tax statement and asked whether a lender would notice if an owner’s signature on a home-equity application was “a little different.”
Kyle had replied that it sounded illegal and refused to discuss it.
Lauren had answered with one sentence.
Forget I asked.
Dad sat down hard.
I told him to freeze his credit immediately.
Lauren started toward the front door, but two minutes later another car pulled into the driveway.
Detective Sarah Morales had arrived.
I had texted her while everyone was arguing.
Lauren’s expression changed the second she saw the badge.
Morales didn’t arrest anyone at the dinner table. She separated us, took statements, photographed the documents, and asked Lauren not to destroy or alter any financial records. Kyle gave her his phone voluntarily. Dad gave her permission to photograph the messages.
Mom kept insisting she had only provided documents because she believed Lauren would get my permission.
Morales asked a simple question.
“Then why didn’t you call Emily?”
Mom had no answer.
The next morning, Dad found a hard inquiry on his credit from the previous year.
The application had never funded. A lender had requested additional identity verification, and whoever submitted it had abandoned the process.
The requested amount was $210,000.
Lauren had tried to use Dad’s house too.
That discovery ended whatever denial remained in my family.
Over the next several weeks, the bank reconstructed the entire scheme.
Lauren had created the fake email address in my name. She used a scan of my license from Mom’s files, altered information to create a counterfeit temporary ID, and uploaded my tax documents to support the mortgage application.
For the remote closing, she positioned the camera poorly, wore glasses I never wore, and claimed the connection was unstable whenever the notary asked her to move closer.
The recording that had supposedly “verified” me became evidence that it wasn’t me.
The bank also traced the $48,000 home-equity line.
More than $31,000 had gone through LKM Design Group, Lauren’s LLC. From there, money paid for custom cabinets, furniture, landscaping, credit-card balances, and a luxury SUV lease.
The rest had covered overdue bills.
Her dream house had never been proof that she was successful.
It had been built on my credit.
Kyle cooperated with investigators after learning what she had done. He showed that Lauren had told him I was a silent investor and had agreed to handle financing. He also provided bank records showing his legitimate $94,000 contribution.
They separated within a month.
Mom called me constantly.
At first she defended herself.
Then she apologized.
Then she blamed Lauren.
Finally, I told her the part she kept trying not to hear.
“Lauren could not have done this so easily if you hadn’t decided my private documents were yours to give away.”
Mom cried.
I didn’t change the subject to make her feel better.
I changed the locks on the small fireproof cabinet where I kept important records, moved everything to a secure location, added credit monitoring, and placed extended fraud alerts where appropriate. Dad did the same.
The bank suspended collection activity against me during the investigation. After reviewing the police report, closing video, device records, fake email account, and identification documents, it formally determined that I had not authorized the mortgage or the home-equity line.
The accounts were removed from my credit reports.
I received written confirmation that I was not personally responsible for the balances.
The property itself became a legal problem for Lauren and the lender, not for me.
Lauren’s attorney eventually contacted mine and asked whether I would consider telling prosecutors that this was a “family misunderstanding.”
I refused.
It wasn’t revenge.
It was the truth.
Months later, Lauren entered a guilty plea to charges tied to identity theft, forgery, and fraudulent loan documents. The court ordered restitution and other penalties, and the house was eventually sold after the lender pursued its remedies against the property.
The white kitchen disappeared from social media.
So did the mountain-view deck.
For a while, Mom barely spoke to me because she said I had “let the system tear the family apart.”
Dad corrected her.
“No,” he said. “The fraud did that.”
That was the first time I felt someone in my family fully understood.
I didn’t celebrate what happened to Lauren. Watching your sister face criminal consequences is not satisfying in the way people imagine. Mostly, it is sad.
But sadness is not the same thing as guilt.
A year later, my credit was clean again. Dad had repaired his relationship with me, slowly and honestly. Mom and I were still distant, but she had stopped asking me to pretend nothing happened.
One Sunday, Dad came to my apartment carrying the old housewarming gift I had once given Lauren.
It was a wooden serving board engraved with the word HOME.
“She left it behind,” he said.
I stared at it for a second, then laughed.
Dad did too.
I put it in a donation box.
Because by then I had learned something expensive, painful, and permanent:
A home isn’t the house someone tricks a bank into buying.
And family isn’t the person who demands your silence after stealing your name.
Sometimes protecting your life means sliding one police report across a dinner table and refusing to pick it back up.