“Bring me coffee, intern!”
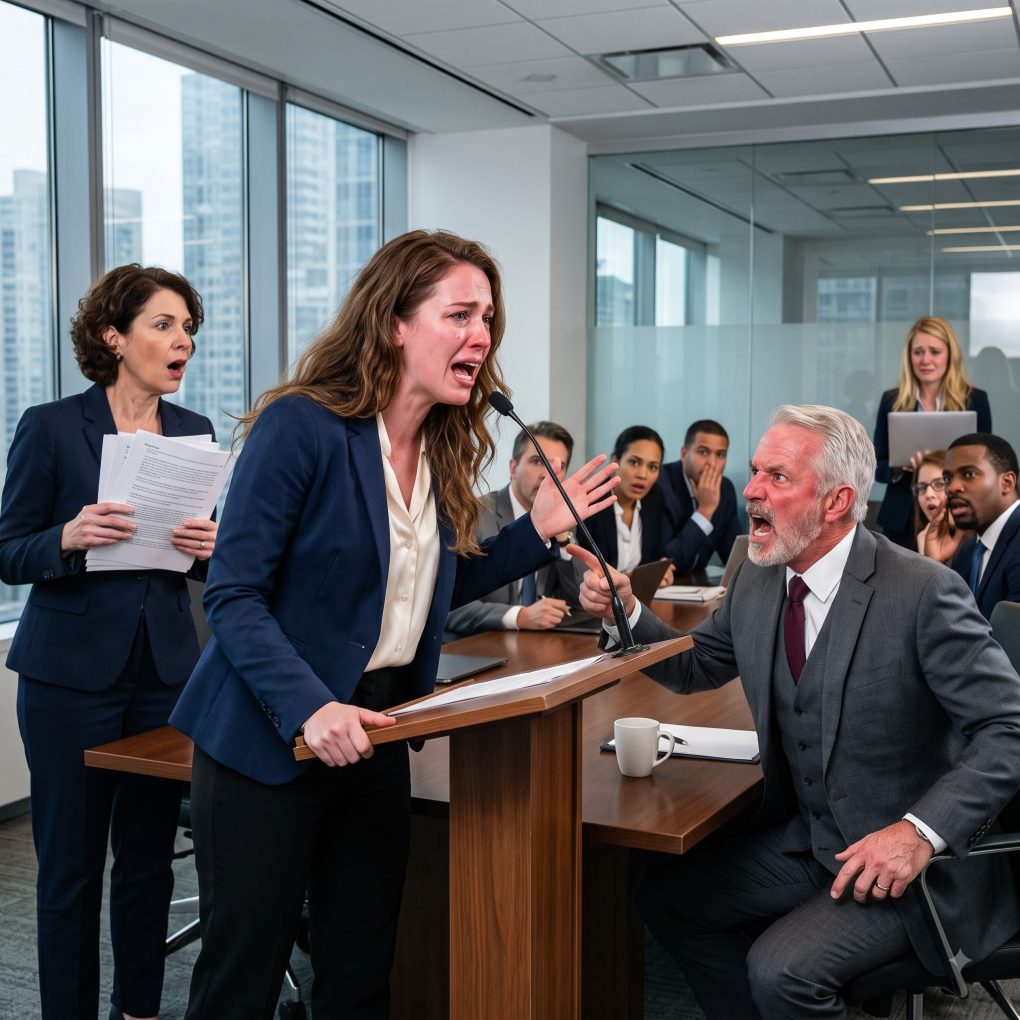
The chairman barked it across the packed conference room as I stood beside the entrance, holding the board packet in both hands.
I was 29, wearing a simple navy blazer and black trousers. Richard Cole was 61, surrounded by executives who had spent years agreeing with him.
I walked to the side table, picked up a fresh mug, and placed it beside his laptop.
“Now sit at the back,” he laughed.
A few executives chuckled.
I smiled once.
Then I walked straight past the chairs and toward the podium.
Richard’s smile vanished.
“What are you doing?”
I adjusted the microphone.
“Starting the meeting.”
“Get out!” he shouted.
The room went silent.
I looked at him, then at the board members.
“For ten years, this company has operated under one assumption: that the person controlling the majority ownership is someone you can ignore.”
Richard stood.
“Security!”
I tapped the microphone.
“Before anyone calls security, check the shareholder register.”
One director opened his laptop.
His face changed.
Another whispered, “It’s her.”
Richard stared at me.
“What are you talking about?”
I held up the board packet.
“My name is on 51% of the voting shares.”
Silence.
Richard looked around the room, waiting for someone to laugh.
Nobody did.
I opened the first page.
“Item one.”
His face went pale.
“What item?”
I looked directly at him.
“The resolution to remove the chairman.”
The room erupted.
But before anyone could vote, the CFO suddenly stood.
“Wait.”
Everyone turned.
She was holding another document.
“I found something you need to see first.”
And the expression on her face told me this meeting was about to become much bigger than a chairman losing his job.
TEASER
I thought the hardest part would be proving that I wasn’t an assistant.
I was wrong.
The document in the CFO’s hands connected Richard to a decision that could put the entire company at risk. And when the board saw it, the people who had laughed at me stopped laughing very quickly.
The CFO, Maria Bennett, walked slowly to the podium.
Richard pointed at her.
“Put that document down.”
She didn’t.
“This came from the internal audit folder,” Maria said. “And someone tried to delete it yesterday.”
The room went silent again.
Richard’s expression hardened.
“That’s nonsense.”
Maria looked at me.
“Do you know what this is?”
I shook my head.
She turned the document around.
It was an amended shareholder agreement from three years earlier.
My name appeared on the signature page.
Richard smiled.
“Exactly. She signed it.”
I stared at the page.
“I never saw this.”
Maria nodded. “That’s what I thought.”
She opened another file.
The original agreement gave me 51% of the voting shares through a private investment trust established by my late grandfather. Richard had been appointed chairman to oversee operations while I remained a non-executive majority owner.
But the amended version claimed I had transferred voting control to a management company Richard controlled.
I had never authorized that transfer.
Richard stepped forward.
“You were a teenager when those documents were created. Your family wanted me to manage the company.”
“Manage it,” I said. “Not take control of it.”
He snapped, “You don’t understand how business works.”
The CFO interrupted.
“She understands more than you think.”
Maria explained that an outside law firm had recently questioned the altered agreement during a financing review. The signature and notarization records didn’t match the firm’s archived copies.
Then she revealed the bigger problem.
The disputed amendment had been used to justify several decisions: executive appointments, major contracts, and the sale of company assets.
If the document was invalid, the board might have been operating under the wrong ownership structure for years.
The room erupted again.
One director asked, “Richard, did you know about this?”
He didn’t answer.
Then the CFO opened a second folder.
“This is why I checked the old records.”
Inside were emails showing Richard had instructed staff to present me as a temporary assistant whenever outside visitors came through headquarters.
One email literally said:
“Keep her away from the investor meetings until we finish restructuring.”
My face burned.
The insults suddenly made sense.
The coffee.
The back row.
The fake intern treatment.
It wasn’t just arrogance.
He had been deliberately hiding the majority owner.
Then came the twist.
Maria had found a transfer agreement showing that Richard planned to sell a major company subsidiary to a firm owned by his longtime business partner.
The board had never approved the deal.
The sale would have moved a valuable asset out of the company at a price far below an independent valuation.
Richard slammed his hand on the table.
“You’re all turning on me over paperwork?”
I looked at him.
“No. We’re looking at the paperwork because you’ve been making decisions as if you owned something you didn’t.”
For the first time, he had nothing to say.
The lead director stood.
“We are suspending the vote until counsel confirms the ownership records.”
Richard stared at me.
Then he leaned close enough to speak quietly.
“You have no idea what you’re walking into.”
I met his eyes.
“Neither did you, apparently.”
The meeting adjourned for ninety minutes while the board contacted outside counsel.
I stayed in the conference room.
Richard left through a side door with two attorneys following him.
For the first time since I had entered the building that morning, no one asked me to make coffee.
Maria sat beside me.
“I should have checked these records years ago,” she said.
“You didn’t know?”
“I knew something was wrong. I didn’t know how deep it went.”
The board reconvened after lunch.
Two attorneys joined by video conference. They had reviewed the company’s archived shareholder records, trust documents, notarization logs, and the original corporate filings.
The conclusion was clear.
The original agreement gave my family trust 51% of the voting shares.
The amended agreement transferring control had serious authenticity problems.
The attorneys could not determine the full legal consequences that morning, but they advised the board to treat the original ownership documents as controlling until the dispute was formally resolved.
That meant one thing.
I was still the majority voting owner.
Richard leaned back in his chair.
“This is absurd.”
The lead director answered calmly.
“What is absurd is that a chairman may have been acting under an ownership document the company cannot verify.”
Richard turned toward me.
“You were never interested in running this company.”
“That doesn’t give you the right to pretend I don’t own it.”
He looked at the other directors.
“She has no operational experience.”
I almost laughed.
“I’ve spent the last four years attending every quarterly review as a silent observer. I read the financial statements. I reviewed the audit summaries. I just wasn’t invited into the room.”
Maria looked down.
That sentence landed hard.
Because several directors knew it was true.
My grandfather had structured the trust that held the voting shares because he wanted family ownership protected while professional managers handled day-to-day operations.
I had respected that arrangement.
Until Richard decided professional management meant permanent control.
The board then addressed the second issue: the proposed subsidiary sale.
The attorneys reviewed the documents.
The transaction had not received the required approval from the board.
The buyer had already prepared financing based on the assumption that the sale would close.
That created another major problem.
Richard had been negotiating away a valuable company asset without completing the proper approval process.
He insisted it was merely an advanced draft.
Maria presented emails showing he had already instructed employees to prepare the operational transition.
The board fell silent.
One director asked, “Why were we not informed?”
Richard gave no clear answer.
Instead, he turned toward me.
“This company will collapse if you remove me.”
I answered quietly.
“Then the company is already in trouble.”
That was the moment everything changed.
The lead director requested Richard’s resignation pending an independent review.
Richard refused.
So the board voted to remove him from the chair position under the company’s governing documents.
The vote passed.
Not unanimously.
But decisively.
Richard sat completely still.
The man who had ordered me to the back of the room that morning was no longer chairman by the end of the afternoon.
Then came the harder part.
Removing him didn’t magically fix the company.
The board had to stabilize operations, review the disputed contracts, notify lenders, and protect employees from unnecessary disruption.
I didn’t suddenly become an expert in every department.
Instead, I asked a different question.
“What do the employees need right now?”
That became our first priority.
The board appointed Maria as interim chief financial officer with expanded oversight, brought in independent counsel, and commissioned a forensic review of the disputed ownership and asset-transfer documents.
The review took months.
It uncovered a pattern of poor governance: approvals bypassed, records inconsistently maintained, and important decisions concentrated around a small group of executives.
It also confirmed that the attempted subsidiary sale had not been properly authorized.
The transaction was canceled.
The company avoided the immediate loss of the asset, although attorneys continued handling the remaining contractual issues.
As for the altered shareholder agreement, the matter moved into formal legal review.
I had never expected my name to become part of a corporate dispute.
I had also never expected to sit across from attorneys discussing the history of my grandfather’s investment.
But I learned quickly.
I asked questions.
I read every report.
And I refused to pretend I understood something when I didn’t.
That difference mattered.
Richard eventually resigned from all remaining executive responsibilities.
He maintained that he had acted to protect the company.
That was his explanation.
The board’s independent review reached different conclusions about several of his decisions, but I didn’t need to turn the story into a personal victory.
The facts were enough.
Months later, the company held a town-hall meeting.
Hundreds of employees gathered in the main auditorium.
I stood at the front with Maria and the new executive team.
I didn’t introduce myself as “the owner.”
I started with something else.
“I owe you transparency.”
The room became quiet.
I explained that the company had identified governance failures and that an independent review was underway. I told them employees shouldn’t have to wonder whether a payroll decision, a contract, or an operational change was being made without proper approval.
Then a production supervisor raised his hand.
“Are we safe?”
It was the only question that mattered.
I answered honestly.
“We’re working hard to make sure you are. We are reviewing the systems, the contracts, and the controls that should have protected this company in the first place.”
It wasn’t a dramatic promise.
It was a real one.
After the meeting, Maria walked beside me toward the elevator.
“You realize everyone knows what happened now.”
“I know.”
“You’re still the majority owner.”
“I know that too.”
She smiled.
“You could have walked in here demanding everything.”
“I almost did.”
“What changed your mind?”
I thought about Richard’s coffee mug.
The back row.
The laughter.
Then I thought about the employees whose names I didn’t know yet.
“I realized owning the company doesn’t mean I need to act like I know everything.”
Maria nodded.
“That might be the first good thing that’s happened here.”
Over the next year, the company changed significantly.
We established clearer approval procedures.
We required independent review for major asset sales.
We strengthened audit controls.
We separated ownership oversight from operational management.
And I made one decision that surprised everyone.
I did not become chairman.
I remained the majority voting owner while the board selected an experienced executive to oversee daily operations.
The role wasn’t about proving that I could replace Richard.
It was about making sure no single person could ever again blur the line between managing the company and controlling it.
I also stopped dressing like someone trying not to be noticed.
Not because I needed to look powerful.
Because I had finally understood that I had spent years making myself smaller to make other people comfortable.
One afternoon, nearly a year after that infamous meeting, I walked into headquarters for another board session.
A new receptionist greeted me.
“Good morning. Are you here for the board meeting?”
“Yes.”
She checked the schedule.
“Conference room A.”
No one asked me to deliver coffee.
No one pointed me toward the back.
No one called me an intern.
I walked into the room and took my seat at the front table.
For a second, I remembered the day Richard had laughed and ordered me to sit behind everyone else.
It seemed like a lifetime ago.
Before the meeting started, the new chairman leaned over.
“Item one?”
I looked at the agenda.
“Governance review.”
He nodded.
“Good place to start.”
And it was.
Because the real lesson wasn’t that I owned 51%.
That was always true.
The real lesson was that ownership only means something when people respect the structure that protects it.
Richard had mistaken silence for permission.
He had mistaken my age for weakness.
He had mistaken my quiet personality for ignorance.
And he had mistaken an assistant’s coffee run for the identity of the person sitting across from him.
I never needed to humiliate him.
I never needed to shout louder.
I simply needed the records to be checked.
The shareholder register answered one question.
The original agreements answered another.
The audit answered the rest.
And when everything was finally on the table, the person who had told me to leave the room was the one who no longer had a seat at it.
That morning, I had carried a coffee mug to the chairman.
By the end of the day, I had carried something much more important into that room:
the truth about who actually owned the company.