The mortgage payment was due in six hours when I found out my husband had emptied our joint account.
I was at the bank with our two kids, eight-year-old Lily and five-year-old Ben, because my card had been declined buying groceries. The teller turned her screen away and lowered her voice. “The withdrawal was made yesterday. By your husband.”
I called Jason from the parking lot. He answered on the fourth ring.
“I took what was mine,” he said. “I’m staying with my brother. Figure out the house yourself.”
“You left us sixty-three dollars.”
“You’ll never make it on your own.” Then he hung up.
I made the payment with what I could borrow from my mother and spent that night checking every account. Jason had stopped contributing to the mortgage two months earlier. He’d told me his paychecks were late, so I’d used my savings to cover the gap. The account history showed deposits going straight to an account I couldn’t access.
The next morning, a letter arrived from my aunt’s insurance company. Aunt June had died in January. She had raised me after my parents divorced, and losing her still hurt too much to discuss. The letter said my claim was incomplete and included a copy of a form I had never signed.
At the bottom, beside my name, someone had written a new address for the payment.
It was Jason’s brother’s address.
I took the letter to attorney Rachel Kim. She read it twice, then asked me to request the complete claim file. For three months, I worked extra shifts, kept the kids in school, and answered Jason’s texts as briefly as I could. He kept asking if the insurance company had called. I never told him what Rachel found.
At our first court hearing, Jason grinned when he saw me beside her. “Did you borrow money for a lawyer, too?”
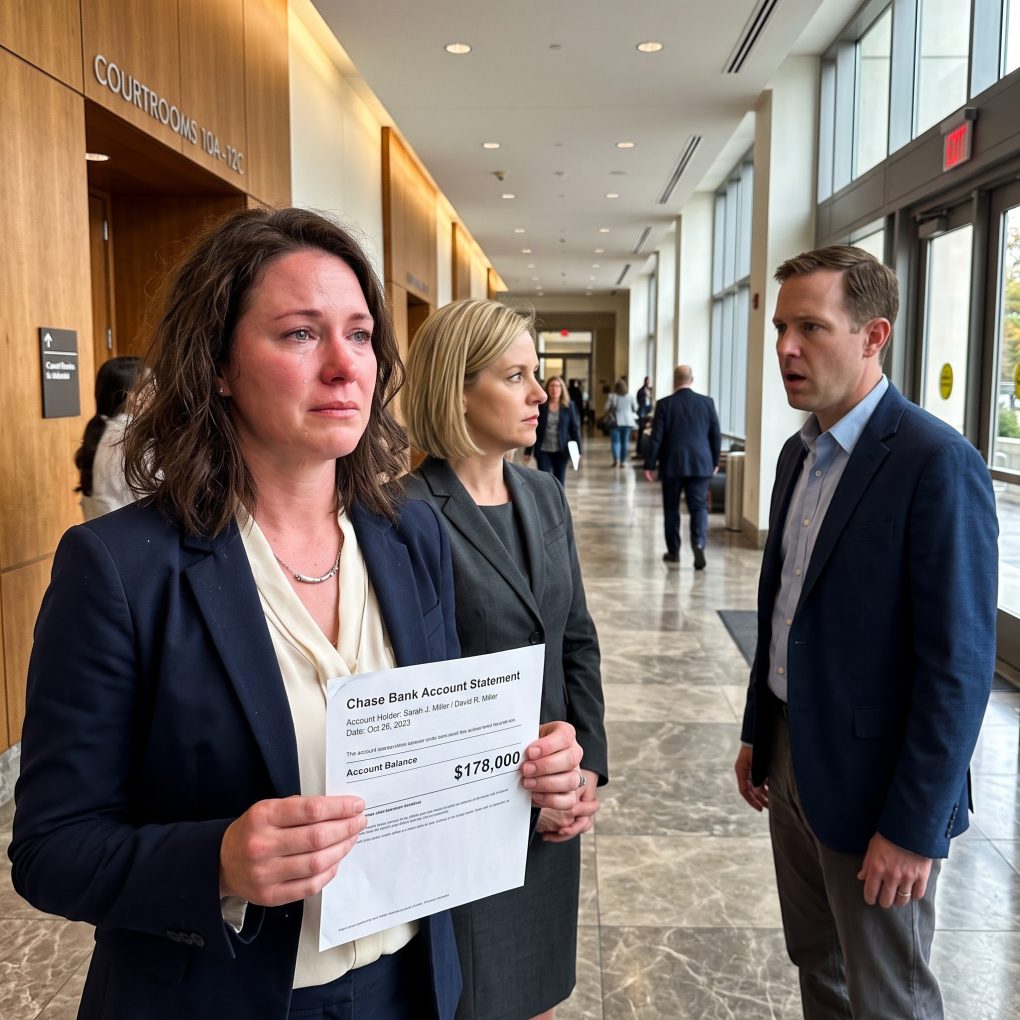
Rachel placed my bank statement on the table. The available balance read $178,000.
Jason’s grin vanished. Then she opened the second folder and said, “Now, let’s discuss the signature.”
He thought the money was the surprise. The document my lawyer placed beside it was the reason he suddenly stopped looking at me.
Jason stared at the page Rachel slid across the table. It was the beneficiary-change request from Aunt June’s insurance file. Someone had tried to replace me with him eight days after June died. The company had rejected it because June’s signature didn’t match the one on her policy.
The judge asked Jason whether he had submitted the request. He said no. Rachel produced the envelope it had arrived in, postmarked near his brother’s house, and the email address used to request a status update. Jason’s email address.
“That proves nothing,” his attorney said. Rachel agreed that the court would need more evidence. Then she showed the judge the payment-redirection form bearing my forged signature and the same address. The insurer had refused that form too, contacted me directly, and completed its review. June had left me $180,000. I’d put $2,000 aside for immediate bills and moved the remaining $178,000 into an account in my name alone.
Jason leaned close as we left the courtroom. “You owe me half of that,” he whispered. “And you still owe the bank for the house.”
Rachel stepped between us. She had asked the court to preserve the marital accounts and order temporary support. The judge set another hearing after Jason supplied his financial records. Outside, Rachel reminded me that the insurance payout and the divorce finances were separate questions for the court to review. I kept the bank statement in my bag and went to pick up the kids.
That evening, my mortgage lender called. Someone had applied for a home-equity line of credit against our house six weeks earlier. The application listed Jason’s phone number and an electronic signature under my name. Its requested amount was $92,000.
I said I had never applied. The lender put the request on hold and gave me a case number. My hands shook so badly I had to write it down twice.
I called Rachel. “If they haven’t paid anything out, can we stop it?”
“We’re going to find out exactly what happened,” she said. “Save every message from him.”
Before I could answer, Jason texted: You made me look like a criminal today. Tell them you approved the loan, and I’ll stop asking about June’s money.
A second message arrived while I was taking screenshots.
I’m outside. Open the door before the kids see me like this.
I looked through the front window. His car was at the curb. Lily was in the living room behind me, holding Ben’s hand, when Jason got out and started toward the porch.
I moved the kids away from the window and called 911. Jason knocked hard enough to make Ben cry. I told the dispatcher my husband was outside, that he had demanded I change my account of a loan application, and that I did not want to open the door. She stayed on the line while Jason shouted my name through the wood.
“Tell them you signed it,” he called. “We can settle everything tonight.”
I did not answer. When officers arrived, Jason was still on the porch. I showed them his texts and explained that the lender had put the loan application on hold. They spoke with him in the driveway. He left without coming inside. One officer gave me a report number and told me to call again if he returned or threatened us. Lily heard me thank them. Only after the patrol car pulled away did she ask if her dad was going to take our house.
“I’m working on keeping us here,” I said. It was the most honest promise I could make.
The next morning, Rachel helped me send the lender a written dispute and a copy of the police report. I froze my credit and requested my credit reports. The lender confirmed that no money had been advanced. It also sent us the application records through its investigation process. They showed Jason’s phone number, his email, and a bank account for the proposed deposit that belonged only to him. The electronic signature was marked with my name, but I had never received the verification message the lender claimed to have sent. Jason had listed his own phone as mine.
The insurance company sent its complete file as well. The first change request had come after Aunt June’s death, when no one could legally change her choice. It named Jason as beneficiary and carried a copied version of June’s signature. The second form tried to move the payment to an address I had never used. Its signature looked like mine until Rachel placed it beside the mortgage papers I had signed years earlier. The first letter of my last name was wrong in exactly the same way on both suspect forms.
I wanted to believe Jason had simply panicked after leaving. Then I found the oldest message in a backup of our shared tablet. It was from two months before he moved out, sent to his brother: June’s policy is still in the desk. If the check comes to her, we need to know before she deposits it.
His brother had replied: I don’t want my address on anything.
I sat at the kitchen table for a long time with that message on the screen. Jason had told me his paycheck was delayed while moving money out of our shared account. He had watched me borrow from my mother for the mortgage. He had asked whether the insurance company had called, knowing exactly why it might. The marriage had been ending around me while I was still trying to pay for it.
Rachel forwarded the records to the insurer’s fraud team and made a report about the loan application. She also gave the family court Jason’s texts, the bank statements, and the lender’s confirmation that the loan had never funded. We did not ask the divorce judge to decide a criminal case. We asked for support, clear rules about the house, and an accounting of the money Jason had taken from the joint account.
At the next hearing, Jason claimed the withdrawal was for living expenses. His bank records showed that much of it had gone into his separate account, while I had paid the mortgage and the children’s expenses. His lawyer argued about how the funds should be divided. Rachel showed the dates and the balances, one by one. The judge ordered temporary child support, required both of us to keep paying our assigned household expenses while the case continued, and barred either of us from opening new debt against the house during the proceedings. Jason would see Lily and Ben under the temporary parenting schedule, with exchanges away from my front door.
Outside court, he tried once more. “June liked me,” he said. “She would have wanted us to share.”
“She wrote down what she wanted,” I answered. “You tried to change it.”
That was the last conversation we had without our attorneys. The fraud investigation took longer than the divorce. Investigators requested the original forms and interviewed Jason. Months later, his attorney told Rachel he would not contest the document evidence. The insurer kept its payment to me in place. The lender closed the disputed application and confirmed in writing that I owed nothing on it. Whether prosecutors would file charges was still their decision; I stopped measuring my safety by how quickly they made it.
The divorce settlement came after financial disclosures and mediation. Jason repaid part of what he had removed from the joint account through the property division. I kept the house and refinanced the mortgage in my name after the settlement was signed. The refinance was possible because I had steady work, a smaller balance after using some of June’s gift, and no home-equity loan hanging over the property. We agreed on a parenting schedule, child support, and a way to handle school and medical costs. Jason signed. I waited for the court’s final order before I believed any of it.
The $178,000 had never been a trick I pulled in three months. It was money June chose to leave me before she died. I had used only what I needed to keep the lights on and get help, then protected the rest while the court sorted out our finances. There was less of it by the time the divorce was final. There was also a roof over the children’s heads and a budget I could understand without asking Jason what he had done with his paycheck.
One Friday, Lily helped me put a new payment calendar on the refrigerator. Ben drew a crooked blue house beneath it. “That’s ours,” he said.
I thought of the day Jason left us with sixty-three dollars and said I would never make it on my own. I had been frightened. I had needed my mother, Rachel, extra hours at work, and a woman who had loved me enough to plan for a future she would never see. I had not done it alone. I had made it anyway.