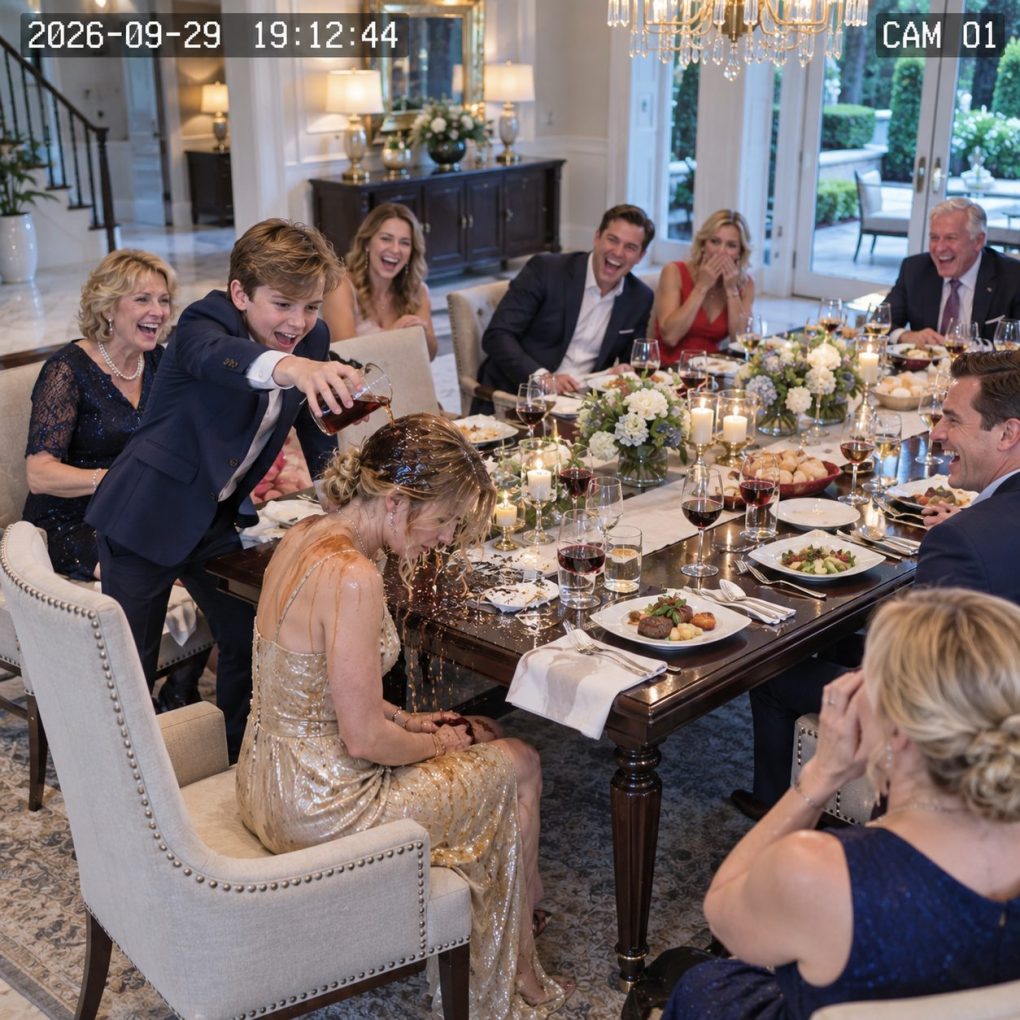
My brother’s son poured his drink over me at dinner and repeated the words my mother had apparently taught him: “You don’t belong here.” Everyone laughed like humiliating me was part of the birthday entertainment. I didn’t argue. I just started wondering how funny they would find it when the bank called about the guarantee tied to my name.
My name is Claire Donovan. I was thirty-six when I finally understood that being the reliable one in a family can become its own kind of trap.
The dinner was for my mother’s sixty-fifth birthday at my brother Mark’s house outside Indianapolis.
I almost didn’t go.
For years, my family had treated me like the strange one because I moved away, built a career in commercial lending, and stopped asking permission before making decisions.
Mark stayed close to home.
That made him the favorite.
His wife, Jenna, knew it.
Their twelve-year-old son, Tyler, had apparently learned it too.
Halfway through dinner, Tyler lifted his soda and dumped it across my lap.
The table went quiet for half a second.
Then he grinned.
“Grandma says you don’t belong here.”
My mother laughed first.
Then Mark.
Then Jenna.
Even my father smiled awkwardly and looked down at his plate.
I sat there with cola running down my dress.
Nobody corrected Tyler.
Nobody told him to apologize.
My mother actually said, “Well, children repeat what they hear.”
That was when I realized the cruelty was not accidental.
It had been rehearsed.
I stood, folded my napkin, and placed it on the table.
Mark leaned back.
“What, no speech?”
“No.”
Mom smirked.
“Good. Maybe you finally learned when to leave.”
I picked up my purse.
Then I looked around the room.
The granite kitchen.
The renovated basement.
The new SUV in the driveway.
The private-school brochures stacked near the refrigerator.
All of it existed partly because three years earlier, Mark’s construction company had nearly collapsed.
The bank refused to extend his line of credit without an outside guarantor.
I signed.
Not because I wanted anything from him.
Because Mom cried and Dad said the company employed eighteen people who might lose their jobs.
The guarantee covered up to $480,000.
Mark promised it would be temporary.
It wasn’t.
For the last eighteen months, his company had repeatedly violated financial covenants, and the bank had contacted me twice asking for updated documentation.
I had been protecting Mark without telling the family how bad things had become.
That ended at dinner.
From my car, I called my attorney.
Then I called the bank officer managing the loan.
“I’m no longer willing to consent to any extension, renewal, or restructuring that increases my exposure.”
There was a pause.
“Claire, that could trigger a review.”
“I know.”
The next morning, Mark called at 7:14.
His voice was shaking.
“What did you tell the bank?”
I looked out my apartment window.
Then I answered calmly.
“The truth.”
Mark called six more times before I answered again. By then, I had already spoken with my attorney, Laura Finch, and reviewed the original guarantee. I could not simply erase an existing obligation by changing my mind, and I knew that. What I could do was refuse to approve any renewal, expansion, or amendment that increased my risk. The bank had been counting on my cooperation to extend Mark’s line of credit for another year.
That extension was now uncertain.
Mark did not understand the distinction. He kept saying, “You canceled the loan.” I corrected him. “No. I stopped volunteering for more.” That made him angrier because the truth was harder to argue with.
His company, Donovan Residential Group, had once been solid. Then Mark took on three large developments at the same time, assuming sales would remain strong. Costs rose. Buyers delayed closings. Cash flow tightened. Instead of slowing down, he borrowed more.
The bank had already noticed.
My guarantee was one reason they had tolerated the risk as long as they had.
What my family did not know was that I had personally covered two covenant shortfalls by supplying additional financial information and agreeing not to challenge temporary extensions.
I had never been required to do that.
I did it because I thought family loyalty meant preventing disaster.
The birthday dinner changed how I understood loyalty.
The bank scheduled a formal review.
That did not mean foreclosure.
It meant Mark had to provide updated statements, disclose current debts, and explain why projected sales had missed targets three quarters in a row.
He panicked.
Mom called next.
“You’re destroying your brother over a joke.”
I asked, “Was it a joke when Tyler said I didn’t belong there?”
She sighed.
“You’re too sensitive.”
“Then why do you need someone so sensitive to guarantee Mark’s debt?”
She hung up.
Laura later told me not to confuse emotional satisfaction with financial wisdom. If Mark defaulted completely, I could still be exposed under the existing guarantee. The best outcome was not revenge. It was a controlled restructuring that reduced risk without pushing the company into collapse.
So I agreed to one meeting.
Mark arrived with his accountant and looked exhausted.
The numbers were worse than I expected.
He owed the bank $392,000 under the guaranteed line and another $210,000 to suppliers. Two developments were still viable, but a third was draining cash.
I asked why he had not told me.
He replied, “Because you always act like you know better.”
His accountant looked embarrassed.
I leaned back.
“I signed a guarantee for almost half a million dollars. I had the right to know.”
He had no answer.
Then the banker proposed a solution: sell the weakest development, reduce the line, and replace my guarantee over time with property collateral from Mark’s company.
Mark hated it because it meant admitting failure.
I liked it because it meant eventually getting my name off the debt.
The bank gave him thirty days.
That evening, Dad came to see me alone.
He apologized for laughing at dinner.
Not dramatically.
He simply said, “I should have stopped it.”
I asked why he didn’t.
He looked down.
“Your mother sets the tone. We all go along because it’s easier.”
That sentence explained more than he intended.
Then he told me something else.
Mom had apparently been telling the family for months that I only helped Mark because I liked controlling him financially.
I laughed.
“Did Mark believe that?”
Dad hesitated.
“Yes.”
That hurt more than Tyler’s soda.
The brother I had protected for three years had rewritten my help into something shameful because admitting dependence was harder.
The next morning, I sent Mark one email.
I will cooperate with the bank’s exit plan. After that, I am done being your financial safety net.
His reply came two minutes later.
Fine. But don’t expect to be part of this family anymore.
I stared at the sentence.
Then I forwarded it to Laura.
Because for once, exclusion sounded less like a threat and more like freedom.
Mark sold the weakest development forty-three days later. The sale was not pretty, but it was enough to reduce the bank balance substantially. He hated the loss, yet his accountant later admitted that keeping the project would likely have damaged the company far more. Sometimes the decision that feels like failure is actually the one that keeps everything else alive.
The bank restructured the remaining debt using equipment and property owned by Donovan Residential Group as collateral. My guarantee was reduced in stages and fully released eight months later. The day I received the final written release, I printed it and placed it in a drawer beside the birthday card Mom had given me.
I did not celebrate Mark’s difficulties.
He had eighteen employees and families depending on his company.
I wanted the business to survive.
I just no longer believed survival required me to stand underneath every falling piece.
Mark’s company stabilized within a year. Smaller projects replaced the oversized developments. He sold the SUV and stopped pretending success had to look expensive from the driveway.
Jenna returned to work part-time.
Tyler transferred from private school to a public school with an excellent academic program.
Nothing terrible happened.
They adjusted.
Mom did not.
For months, she told relatives I had “nearly bankrupted Mark” because I was offended by a child.
I stopped defending myself.
People who wanted the actual facts asked.
People who preferred her version were unlikely to change because of another explanation.
Then something shifted.
At Thanksgiving, Dad refused to attend unless I was invited.
That surprised everyone, including me.
Mom eventually called.
“You can come if you want.”
I almost laughed.
“That isn’t an invitation.”
She went quiet.
Then she tried again.
“Claire, I would like you to come.”
I asked whether Tyler had apologized.
Another silence.
“No.”
“Then I won’t.”
That was the first holiday I spent completely outside my family.
It was also one of the most peaceful.
I had dinner with friends.
Nobody humiliated anyone for entertainment.
Nobody measured love through money.
Nobody needed me to guarantee anything.
Three weeks later, Mark came to my office alone.
He looked uncomfortable.
“I owe you an apology.”
I waited.
He admitted that Mom had spent years telling him I helped because I wanted to feel superior. Believing her allowed him to accept my money without feeling indebted.
Then he said, “I should have stopped Tyler.”
“Yes.”
“I should have thanked you years ago.”
“Yes.”
He nodded.
“I know.”
That mattered.
Not because it erased the past.
Because he finally stopped arguing with it.
Tyler apologized later too. Mark made him do it in person.
I told him I accepted the apology but explained why the joke had been wrong.
He looked embarrassed and said, “Grandma says stuff about you all the time.”
That sentence became the final turning point.
Mark confronted Mom.
Dad backed him.
For the first time, the family stopped treating her insults as harmless personality.
Mom did not change overnight.
But she became quieter when nobody laughed.
Two years later, we had dinner together again.
Same family.
Different table.
Tyler was taller.
Mark looked older.
Mom watched her words.
Nobody poured anything on anyone.
After dessert, Mark asked me whether I regretted signing the guarantee in the first place.
I thought about it.
“No.”
He looked surprised.
I explained that the guarantee had protected eighteen jobs during a real crisis. Helping had not been the mistake.
The mistake was allowing help to become invisible.
Allowing gratitude to turn into entitlement.
Allowing people to believe that because I was capable, I would always absorb more.
That was the lesson I kept.
Generosity should never require humiliation as its price.
Family support should not mean permanent financial exposure.
And being the reliable person does not mean becoming the person everyone is allowed to disrespect.
My family thought the funniest part of that birthday dinner was watching me sit there soaked and silent.
They were wrong.
The silence was not humiliation.
It was the moment I stopped explaining my value to people benefiting from it.
And once my name finally came off that guarantee, something else came off too.
The obligation to keep proving I belonged.