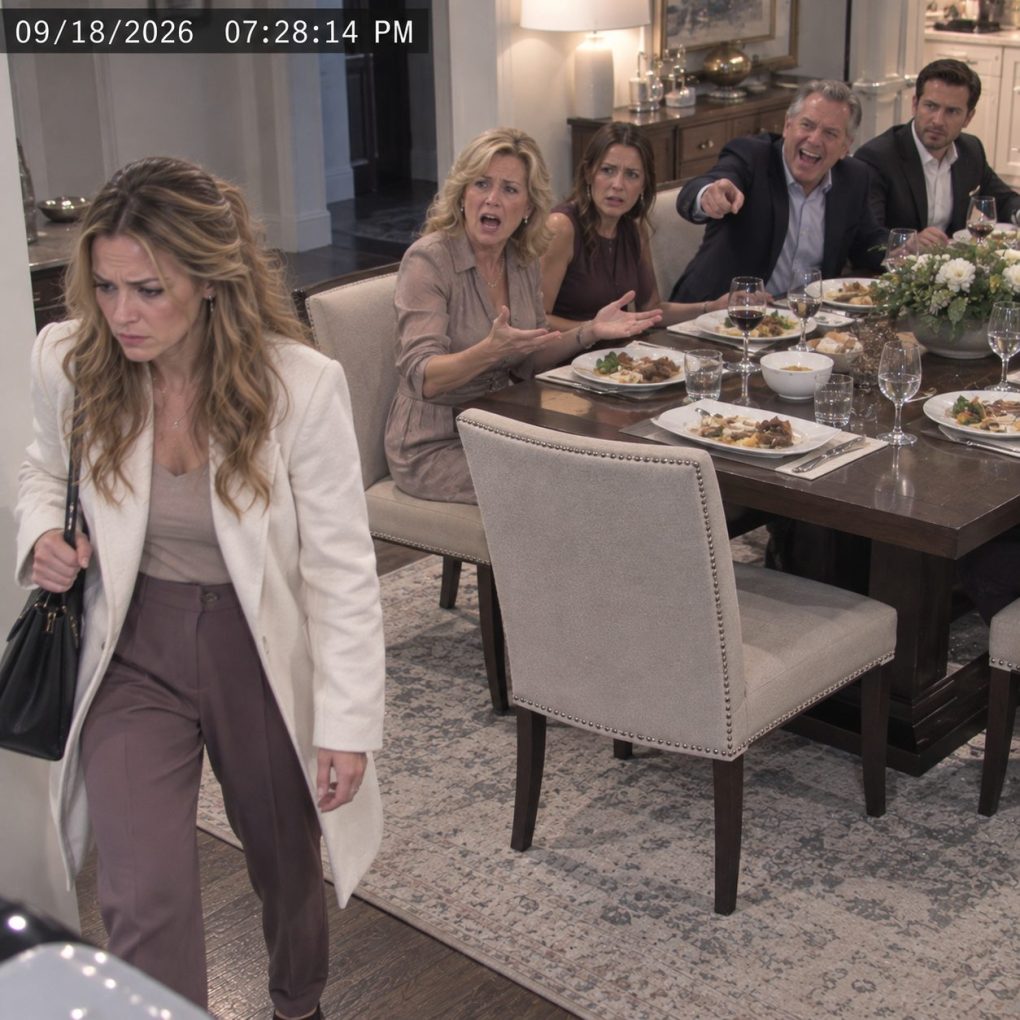
Dad’s fork hit his plate hard enough to silence the entire table. “You are the most useless child in this family,” he said. Mom looked away, pretending embarrassment, while my younger sister Jenna folded her arms. I was thirty-four, sitting in my parents’ dining room outside Raleigh, North Carolina, being attacked because I wouldn’t give Jenna $65,000.
Her latest dream was turning an abandoned event space into a luxury wedding venue. She had no hospitality experience, no completed business plan, and less than $4,000 in savings. Her fiancé, Logan, claimed the property would make them rich within two years.
Dad had apparently promised them I would provide the startup money.
Nobody had asked me.
When I said no, Mom called me selfish. Jenna reminded everyone that my financial investigation firm was doing well and said $65,000 was “nothing” to me. Dad delivered his useless-child speech while Logan stared at his plate.
Then my phone vibrated.
I glanced down.
A commercial credit-monitoring alert showed a new financing application associated with my Social Security number and business profile.
Requested credit: $82,000.
Applicant business: Everly Ridge Events LLC.
Jenna’s proposed wedding venue was called Everly Ridge.
I felt my heartbeat slow rather than accelerate.
Two weeks earlier, Jenna had casually asked me to review a vendor application on her laptop. Three days later, Mom had called asking for my current address because she was “updating emergency paperwork.”
Now I understood why both conversations had felt strange.
I didn’t accuse anyone.
I took a screenshot, locked my phone, and stood.
Dad laughed. “Running away because you can’t handle the truth?”
I picked up my coat.
“No. I have work tomorrow.”
Jenna smirked.
I drove home and opened my secure laptop. I didn’t attempt to access Jenna’s accounts or anything that wasn’t mine. I pulled my own credit records and checked the alert details available to me.
The application listed an email address I didn’t recognize.
But the contact phone number was familiar.
It belonged to Logan.
I immediately froze my personal credit, contacted the lender’s fraud department, and documented the alert.
Then I opened the business registration database.
Everly Ridge Events had been formed nine days earlier.
Its organizer wasn’t Jenna.
It was my father.
By eight the next morning, I had spoken with an attorney and filed an identity-theft report. The lender suspended the application while its fraud team reviewed the documents.
I gave them one simple statement.
I had never applied for the credit.
I had never authorized anyone to use my personal information.
The lender wouldn’t show me every internal document immediately, but it confirmed enough to make my stomach turn. The application represented me as a financial guarantor connected to Everly Ridge Events.
I wasn’t.
Dad called before lunch.
His tone was completely different from the night before.
“Did you contact the lender?”
I asked how he knew there was a lender.
Silence.
Then he said Jenna’s business financing had suddenly been frozen and accused me of sabotaging her.
I recorded the time of the call in my notes.
“I didn’t sabotage anything. I reported an application using my identity.”
Dad became angry.
He insisted nobody was stealing from me because the family intended to repay everything after the venue became profitable.
That sentence answered more than he realized.
I told him future communication about the financing needed to be in writing.
Then I hung up.
Later that afternoon, Logan emailed me.
He claimed Dad had told him I had agreed to guarantee the loan after “thinking it over.” Logan admitted entering some information into the application but said he believed Dad had permission.
Attached was a draft business plan.
Page seventeen listed me as an investor contributing $65,000.
Page eighteen listed my financial profile as additional security for commercial financing.
I had approved neither.
Jenna arrived at my office around four.
She was crying.
She said Dad had convinced her I would eventually agree because I had rescued the family financially before. She knew they were using my name in the business plan, but she claimed she did not know my personal information had been entered into an actual credit application.
I asked whether she had told Dad to stop.
She looked down.
“No.”
That mattered to me.
Maybe she hadn’t completed the application herself, but she had been perfectly comfortable building her dream around money I had refused to provide.
Before leaving, Jenna whispered something unexpected.
“Check Dad’s desk.”
I frowned.
“Why?”
She wiped her eyes.
“Because Everly Ridge isn’t the first time he’s used your information.”
I didn’t search Dad’s desk.
Instead, I gave Jenna’s statement to my attorney and let the proper investigation determine whether there were other accounts connected to my identity.
There were.
One was an old business credit card opened eighteen months earlier. The balance was only $6,700, but I had never applied for it. Statements had been sent electronically to an address controlled by Dad.
The purchases were mostly family expenses.
A refrigerator.
Property taxes.
A transmission repair.
Nothing luxurious.
That somehow made the situation sadder.
Dad hadn’t created some elaborate criminal empire. He had simply convinced himself that because I earned more money than everyone else, my financial identity was another family resource.
The commercial lender permanently rejected the Everly Ridge application after confirming I had not authorized the guarantee.
The earlier credit account was closed and disputed through the appropriate process. I cooperated with investigators and provided documents without exaggerating what I knew.
Logan withdrew from the wedding-venue project.
Then he withdrew from his engagement to Jenna.
She blamed Dad at first.
Eventually, she admitted she had ignored too many warning signs because she wanted the business badly enough to believe permission would come later.
My relationship with my parents changed completely.
I stopped paying their occasional bills. I removed Dad from every emergency financial document where he still appeared and placed additional security protections on my accounts.
Months later, Dad asked to meet.
He looked older.
He apologized, although he still tried to explain that he had always intended to repay everything.
I told him repayment had never been the central issue.
“You heard me say no,” I said. “Then you decided my no didn’t count.”
He had no answer.
Jenna never opened Everly Ridge.
Instead, she took a job with an established wedding venue and spent the next year learning the business she had originally expected me to finance.
Strangely, that was probably the best thing that happened to her.
As for me, I still remember Dad calling me useless across that dinner table.
At the exact moment he was insulting me for refusing to provide $65,000, my phone was warning me that someone had decided to take my financial consent instead.
I said nothing that night because anger wouldn’t tell me who had done what.
Records would.
And once I started following those records, I discovered something more expensive than any loan.
My family hadn’t misunderstood my generosity.
They had mistaken it for permission.