I thought losing the family house to my younger sister was the worst betrayal my parents could pull on me, but three days later, a phone call proved I had underestimated them completely. I was finishing lunch at my office in Boston when a woman from Harbor Federal Bank calmly asked when I planned to make the overdue payment on a $286,000 loan secured against my parents’ Connecticut house.
I laughed at first because the question sounded absurd, but the woman did not laugh with me. She verified my full name, date of birth, and the last four digits of my Social Security number before sending me a copy of the application, and when I opened the attachment, my stomach tightened because there, beneath a declaration saying I had personally appeared at the closing, was something that looked disturbingly like my signature.
“I never signed this,” I said. The banker hesitated before telling me the documents showed I had appeared in Connecticut on May 14, so I pulled up my calendar and felt my pulse begin hammering. “I wasn’t even in the state,” I told her. “I was presenting at a medical conference in Chicago that entire week.”
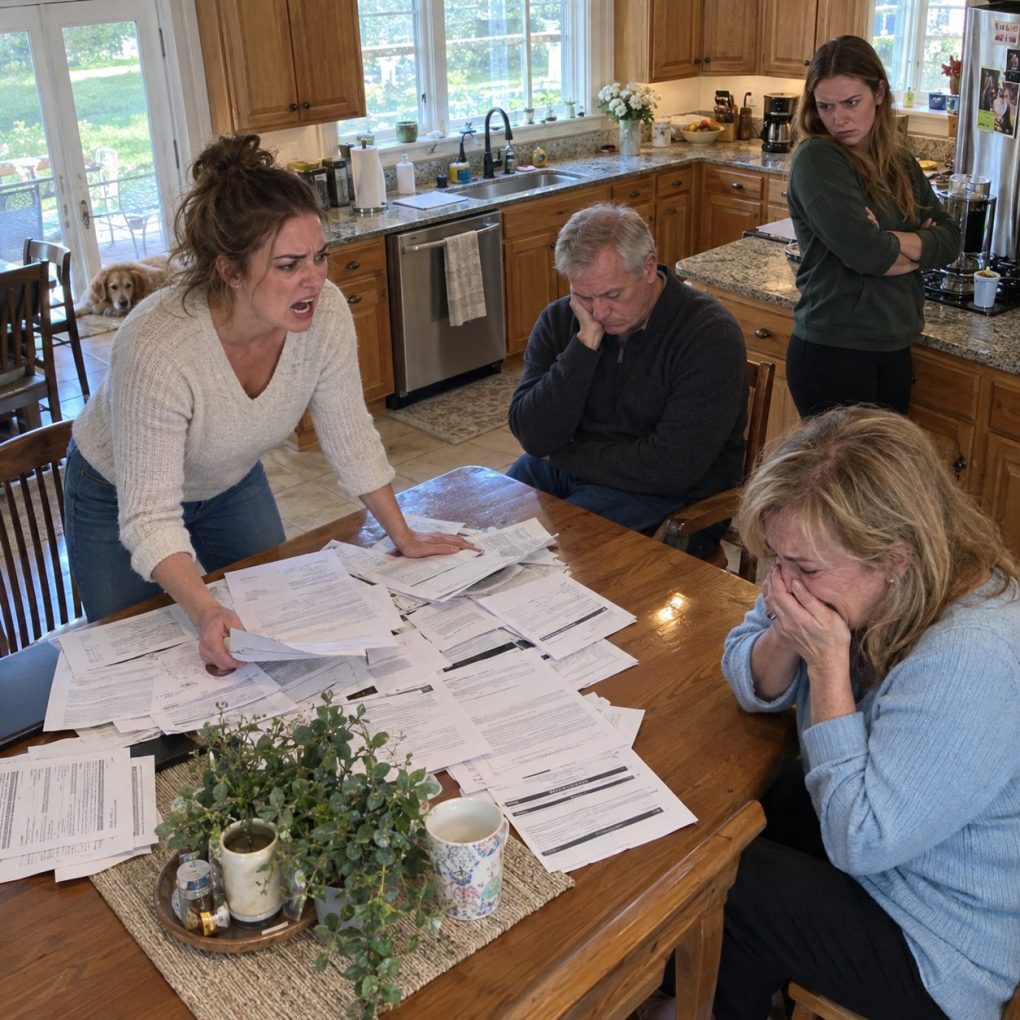
By the following morning, I was standing in my parents’ kitchen with the loan papers spread across the same oak table where we had celebrated birthdays for twenty years. Dad, Richard, stared at the documents without touching them, Mom’s face drained white, and my sister Lauren folded her arms as though I were the one who had arrived to cause trouble. “Someone borrowed almost three hundred thousand dollars using my name,” I said. “I’m giving you one chance to tell me why.”
Mom whispered, “Claire, please don’t make this bigger than it needs to be,” and that sentence frightened me more than a denial would have. Dad finally muttered that the house had needed expensive repairs and that the bank would not lend him enough money after his business started failing, but when I demanded to know how my signature had appeared on a loan I had never seen, he refused to answer.
Then Lauren slammed her palm against the counter. “They were trying to save the house,” she snapped. “The same house you barely visited after you moved away.”
I stared at her because something about the way she said it sounded rehearsed. “You knew about this?”
Her expression changed for less than a second, but it was enough.
Dad immediately told her to stop talking.
That was when I realized the $286,000 loan was not the whole secret. I gathered the papers, looked directly at my father, and said, “If you forged my signature, I’m going to the bank.”
For the first time that morning, he looked genuinely terrified.
Then Mom began crying and whispered, “Richard, she’s going to find out where the rest of the money went.”
I stopped with my hand on the kitchen door. Until that moment, I had assumed the money had gone into the house, but when I asked Mom what she meant by “the rest,” Dad stood so quickly his chair scraped across the floor. “Enough,” he said sharply. “Nothing else needs to be discussed until everybody calms down.”
That was exactly why I left.
Within hours, my attorney, Daniel Mercer, had advised me to freeze my credit, formally dispute the loan, preserve every message from my family, and provide Harbor Federal with proof that I had been in Chicago on the date of the supposed closing. My hotel receipt, airline records, conference photographs, and employer travel authorization all placed me nearly eight hundred miles away when a notary claimed to have watched me sign those papers.
Two nights later, Lauren appeared outside my apartment. Her mascara was smudged, anger barely hiding underneath the panic in her face, and before I could invite her inside, she said, “If you report Dad, they could lose everything.”
“You mean the house they just gave you?”
“That isn’t fair.”
“No,” I said quietly. “Putting $286,000 in my name without asking me wasn’t fair.”
Lauren’s eyes dropped, and when I asked again whether she had known about the loan, she finally admitted Dad had told her months earlier. He had described my signature as a technical shortcut because my name had once been added to the property for estate-planning purposes, and Lauren claimed she had believed our parents would refinance before I ever became responsible for anything.
Then I asked the question Mom had accidentally put into my head. “How much of that money actually went into the house?”
Lauren began crying.
Only about $160,000 had been used for repairs, taxes, and existing household debts. Nearly $90,000 had gone into keeping Lauren’s failing clothing boutique alive, while the remainder had covered credit cards and other expenses Dad had been hiding from everyone.
I could barely speak. My parents had not simply forged my name to save their home; they had secretly put my credit and financial future at risk to rescue the same sister they had just rewarded with the house.
Harbor Federal froze collection activity while its fraud department investigated, and several days later Daniel called with another development. The title agent who had supposedly verified my identity could not produce surveillance footage, a valid copy of the identification used at closing, or a convincing explanation for why the signature in the file differed from signatures on my recent documents.
Then Daniel went quiet.
“There’s something else,” he said.
The bank had traced the loan disbursements.
One transfer had not gone to Lauren’s business, the house, or my parents’ creditors.
Forty-seven thousand dollars had been wired to an account none of us had mentioned—and the account was in my mother’s name.
Mom asked to meet me alone after I confronted her about the $47,000 transfer. We sat in a quiet diner outside Hartford, and for several minutes she only stirred coffee she never drank before admitting that the account had been hers, but the money was no longer there. Dad had transferred it to her because he was afraid his business creditors would seize everything he controlled directly, and over the following year they had used most of it for mortgage payments, medical insurance, groceries, and bills they had been too ashamed to admit they could no longer afford.
“You could have asked me for help,” I said.
Mom’s eyes filled with tears. “Your father couldn’t bear asking.”
“So he decided stealing my signature was less humiliating?”
She flinched, and for once, I did not soften the sentence.
The bank’s investigation eventually confirmed what my documents had already shown: I could not have attended the loan closing, and the signature attributed to me could not be treated as valid authorization. Harbor Federal removed the disputed obligation from my personal credit reporting while its lawyers dealt separately with the property, the title company, and the people who had participated in the closing.
That did not magically erase the debt attached to the house. Because my parents and Lauren could not qualify to refinance the legitimate obligations remaining against the property, the house had to be sold, and the proceeds were used to satisfy the mortgage, disputed loan settlement, taxes, fees, and other secured expenses. By the time everything was resolved, the inheritance Lauren had been so proud to receive was effectively gone.
She blamed me at first.
“You could have handled this privately,” she said during one miserable phone call. “You didn’t have to destroy everything.”
I had spent my entire childhood being the reasonable daughter, the one who earned scholarships, solved her own problems, lent money without asking when it would come back, and listened whenever Mom said Lauren “needed a little more help.” For years, being dependable had sounded like praise; only now did I understand that my family had gradually turned it into permission.
“I didn’t destroy the house,” I told her. “I refused to let you save it by destroying me.”
She hung up.
Dad took longer to accept what he had done. When we eventually met in Daniel’s office, he brought a folder filled with financial statements and admitted he had convinced himself that because I was successful, I would survive the damage if anything went wrong. He believed he would refinance before I discovered the loan, repair the family finances, and somehow return everything to normal without ever having to confess.
“You were always the strong one,” he said.
I looked at him for a long moment. “Being strong did not mean you were allowed to hurt me more.”
That was the first time Dad cried in front of me.
The title agent later faced professional disciplinary action, my parents agreed to cooperate with the bank and repay what remained through a structured settlement, and Lauren closed her boutique rather than continue pouring borrowed money into it. None of it was dramatic enough to undo what had happened, but it was real accountability, which mattered more to me than watching anyone suffer.
Several months later, I returned to the Connecticut house on the morning the new owners were scheduled to receive the keys. The rooms were empty, the family photographs had been taken down, and faint pencil marks still climbed the hallway wall where Dad had measured Lauren and me every birthday when we were children.
Mom found me standing there.
“I thought keeping this house meant keeping the family together,” she said.
I ran my fingers over the mark beside my name from when I was twelve. “The house never held us together, Mom. Trust did.”
She lowered her eyes because there was nothing left to argue with.
I did not permanently disappear from my parents’ lives, but I stopped confusing forgiveness with access. They had to rebuild their relationship with me slowly, without financial favors, guilt, or expectations that I would rescue everyone whenever something went wrong, and Lauren and I did not speak normally again until almost a year later, when she finally apologized without adding a single excuse afterward.
In the end, my parents lost the house they had committed fraud trying to preserve, Lauren lost the inheritance she thought had made her the chosen daughter, and I lost the comforting belief that family automatically meant safety.
But I kept something they had almost taken from me without permission.
My name.
And this time, no one in my family would ever sign it for me again.