I heard my husband planning to take control of my company before I knew he had forged my signature.
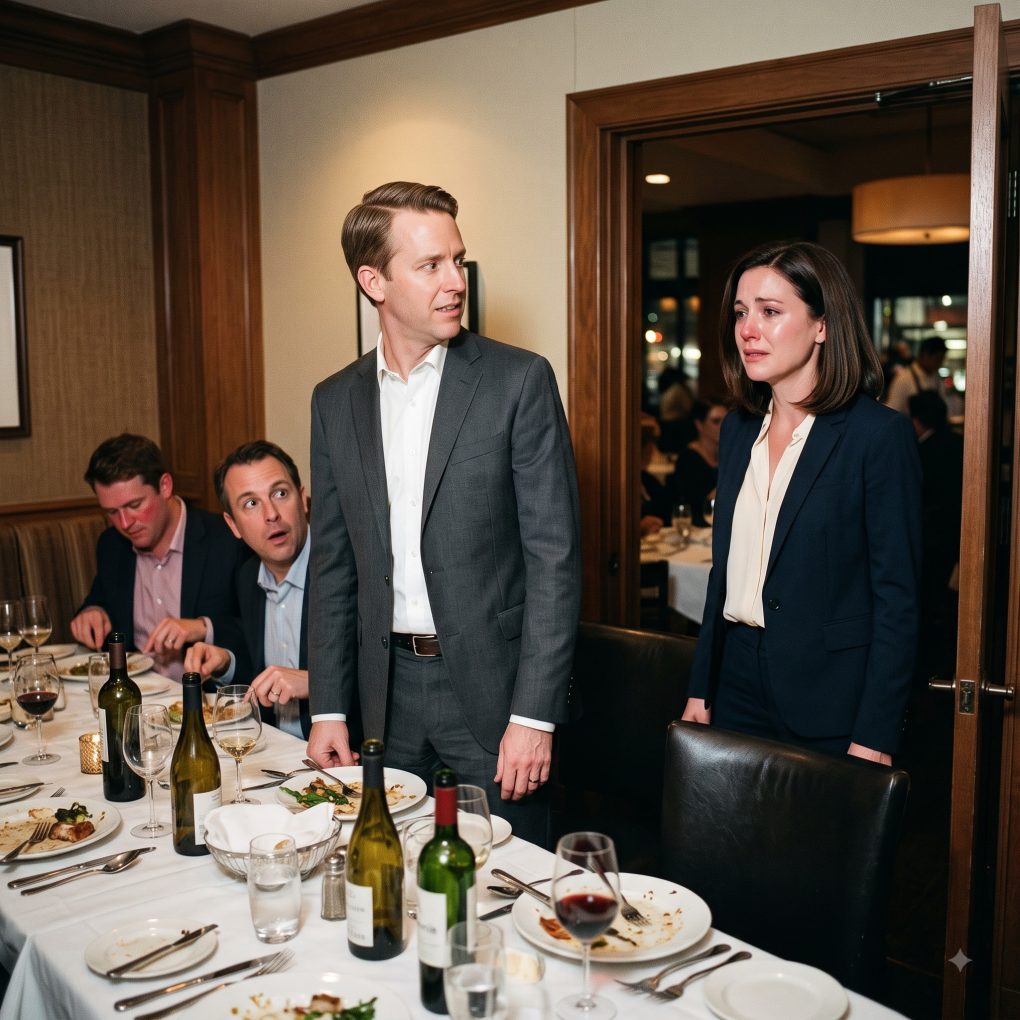
His colleague had just texted, You need to hear what he’s saying. I was at a restaurant for a client dinner, ten feet from the private room where Aaron was entertaining people from his consulting firm. I stepped into the hallway and heard my business name.
“She runs that company on fumes,” Aaron said. “I need to formalize my involvement before she destroys it.”
Three men laughed. One asked whether I would sign anything if Aaron called it a favor. Aaron said, “She trusts me.”
I built Vale & Co. from a folding table into a design studio with fourteen employees. Aaron had never made a sales call or met our accountant. His only connection to the company was our marriage, and apparently he thought that gave him a title.
I walked back into the room. The laughter stopped.
“If you’d like to help,” I said, “I’ll have my office send you a junior consulting rate.”
Aaron’s smile froze. He followed me into the hall and grabbed my elbow. “You embarrassed me in front of my team.”
“You told them I couldn’t run my own company.”
“It was a joke.” He let go when a server came through the door. “We’ll talk at home.”
I left. On the drive, my operations manager texted that someone had asked her for a copy of our operating agreement. She assumed it was me. I pulled over and called her. Before she could tell me who had asked, another call flashed across my screen: Ben Carter, Aaron’s friend at the firm.
Ben never called me. He sounded breathless when I answered.
“I’m sending you a file,” he said. “Open the last page first. I helped him put the packet together because he told me you approved it.”
My phone chimed. I opened the attachment and scrolled to the end. There, above a line marked AUTHORIZED OWNER, was my signature.
I had never signed it.
I thought Aaron wanted credit for a company he hadn’t built. The file in Ben’s email showed that he had already moved far beyond bragging.
I zoomed in on the signature until the letters blurred. It was copied from a holiday card I’d written Aaron years earlier, right down to the loop I no longer put in my name.
“What is this?” I asked Ben.
“A lender packet. Aaron said you wanted his firm to arrange emergency financing.”
We didn’t need financing. Our payroll account had enough to cover six months. Ben said the packet requested a $900,000 line of credit, secured by my company’s receivables. Attached was a resolution naming Aaron an authorized manager. Vale & Co. was a single-member LLC. I was the member, and I had never authorized any manager.
Then I saw the date: tomorrow.
The lender’s verification call was scheduled for 9 a.m. Aaron had listed our office number, but the contact name and mobile number belonged to him. Ben admitted he’d drafted the business summary and collected the exhibits. When he noticed that my signature on the resolution looked pasted in, he’d asked Aaron about it. Aaron told him to mind his job.
“Why tell me now?” I asked.
“Because I found this.”
He sent a second page: an email Aaron had forwarded to his personal account. The subject line read TRANSITION PLAN. The sender was Natalie, my director of operations—the person who had texted me about the operating agreement.
Her message listed our three largest clients and a timeline for moving their contracts to a new company after the loan funded. At the bottom, she wrote, “Once Claire is removed from day-to-day approvals, I can bring the team over.”
I called Natalie. She answered on the first ring and swore she’d never written it. I wanted to believe her, but the email carried her name and a familiar signature block. She said someone had used a shared office computer that afternoon. When I asked who had been there, she went quiet.
“Aaron,” she whispered. “I let him into the conference room. He said you asked him to pick up tax records.”
My stomach tightened. The lender packet included our tax returns.
Natalie offered to come back to the office, but I told her to stay home and send me the access logs. I called our bank’s fraud line and left a message for our business attorney. Then Ben sent one more attachment: an invoice from Aaron’s firm to the proposed new company. It showed a success fee due when the loan closed, with Ben’s name in the approval field.
“Did you sign off on this?” I asked.
“No. That isn’t my approval.”
Before I could answer, my office security app alerted me that the alarm had been disarmed with Natalie’s code. The camera feed loaded. Aaron was inside, standing at her desk with a cardboard box.
I watched Aaron pull a binder from Natalie’s bottom drawer and slide it into the box. The timestamp was 11:42 p.m. Behind him, the conference room door was open, and our shared computer was still lit.
I called the police nonemergency line and reported that someone was taking company records from my office without permission. I stayed on the camera feed. Aaron had a key to our house, but he did not have a key or an access code to the office.
Then I called Natalie. “Did you give him your code?”
“No. I used it while he was there this afternoon. He stood behind me.” Her voice shook. “Claire, I’m sorry.”
“Send me what you remember about that visit. Don’t go to the building.”
On the camera, Aaron opened a filing cabinet and photographed a stack of signed client agreements. I saved the clip and sent it to my attorney, Rachel Kim. She called back.
“Do not confront him,” she said. “The lender has to hear directly from the company’s owner that those documents are disputed. I’ll join that call first thing.”
Two officers arrived while Aaron was loading the box into his car. They called me to confirm I had not authorized him to remove company files. Aaron told them he was my husband and was helping with a loan. I explained that the loan application used a signature I had not provided. The officers documented what they saw, asked him to leave the box at the office, and gave me a report number. They didn’t promise an arrest. They told me to preserve the video and speak with an investigator.
Aaron called before I had hung up. “You sent cops to my job?”
“You went into my office.”
“You’re overreacting. I was trying to save us.”
“From what?”
He paused. “From your pride.”
I stayed with my sister that night. At 7 a.m., Rachel and I met Natalie at the office. The binder held signed contracts and our client contact list. Aaron had spent nine minutes photographing pages. Natalie handed over the computer access logs and a written account of his visit. Rachel had our IT provider preserve the computer, footage, and login records. We changed the alarm code and revoked the temporary guest account Aaron had persuaded Natalie to create.
At 9 a.m., Rachel and I joined the lender’s verification call. I identified myself as Vale & Co.’s sole member, said the resolution and signature were unauthorized, and asked the lender to stop reviewing the application. Its fraud team opened a case and requested copies of my operating agreement and the police report. Rachel sent both through the lender’s secure portal. The proposed line of credit never funded.
Ben came to Rachel’s office that afternoon with his laptop. He showed us the original versions of the packet, Aaron’s messages, and an email from his firm’s billing system. The invoice he’d sent me was real, but the approval field was filled automatically with the project lead’s name. Ben was the project lead because Aaron had assigned him the work. He had not approved the success fee.
“That doesn’t excuse me for not calling Claire sooner,” Ben said. “I saw the signature and wanted to believe him.”
Then he opened a spreadsheet he’d recovered from the project folder. It was titled SIX-MONTH RUNWAY. I expected a plan to move our clients. Instead, it listed Aaron’s personal debts: overdue payments, a private loan, and money owed after an investment he’d concealed from me. The total was just over $700,000. A column marked FIRST DRAW divided the proposed loan among those creditors. The rest was labeled “transition costs.” I stared at the numbers. Aaron hadn’t been rescuing a struggling company. He was using mine to cover his losses, then planning to take its clients when the debt came due.
The final piece came from Natalie. She had found the original email behind the TRANSITION PLAN page. Aaron had created it on the shared computer while logged in as a guest. He had copied her signature block from an old client email and sent the message to himself, making it look as if she had offered to help him move the team. The access logs and message headers lined up with the afternoon she’d let him in. Natalie hadn’t been his partner. She’d been his cover.
I apologized to her for the suspicion in my voice the night before. She shook her head. “I should have checked with you before I opened the door.” We revised our office access rules together. She also called our three largest clients personally, with me beside her, to warn them that anyone claiming to represent a successor company did not speak for Vale & Co. All three stayed.
Ben reported the matter to his firm’s compliance counsel. A week later, the firm told Rachel it had removed Aaron from client work and was cooperating with the lender’s investigation. I handed the investigator the camera footage, loan packet, original email records, and Ben’s messages. I don’t know whether charges will result, but the evidence is with the investigator.
Aaron sent me one long text. He said he’d intended to repay the loan before I noticed it. He said I should remember all the years he’d supported me while I built the company. Then he asked if we could talk before I “ruined both our lives.”
I read it once and forwarded it to Rachel. Through her, I told him to direct all business questions to counsel. I filed for divorce. I could decide who spoke for my business and who entered my life.
On Friday, I gathered my fourteen employees and told them the loan had been stopped, their paychecks were secure, and our clients were staying. I didn’t share Aaron’s debts or make Natalie defend herself in front of the team. Afterward, she brought me a signed renewal from our oldest client.
I thought about Aaron’s colleagues laughing when he called my company a wreck. For one terrible night, I feared he might make that claim true. But when the doors opened Monday, my team came in, the phones rang, and we kept doing the work that built Vale & Co. in the first place. Aaron had wanted my signature to give him a company. The real one was on that renewal, beside a client’s decision to stay.