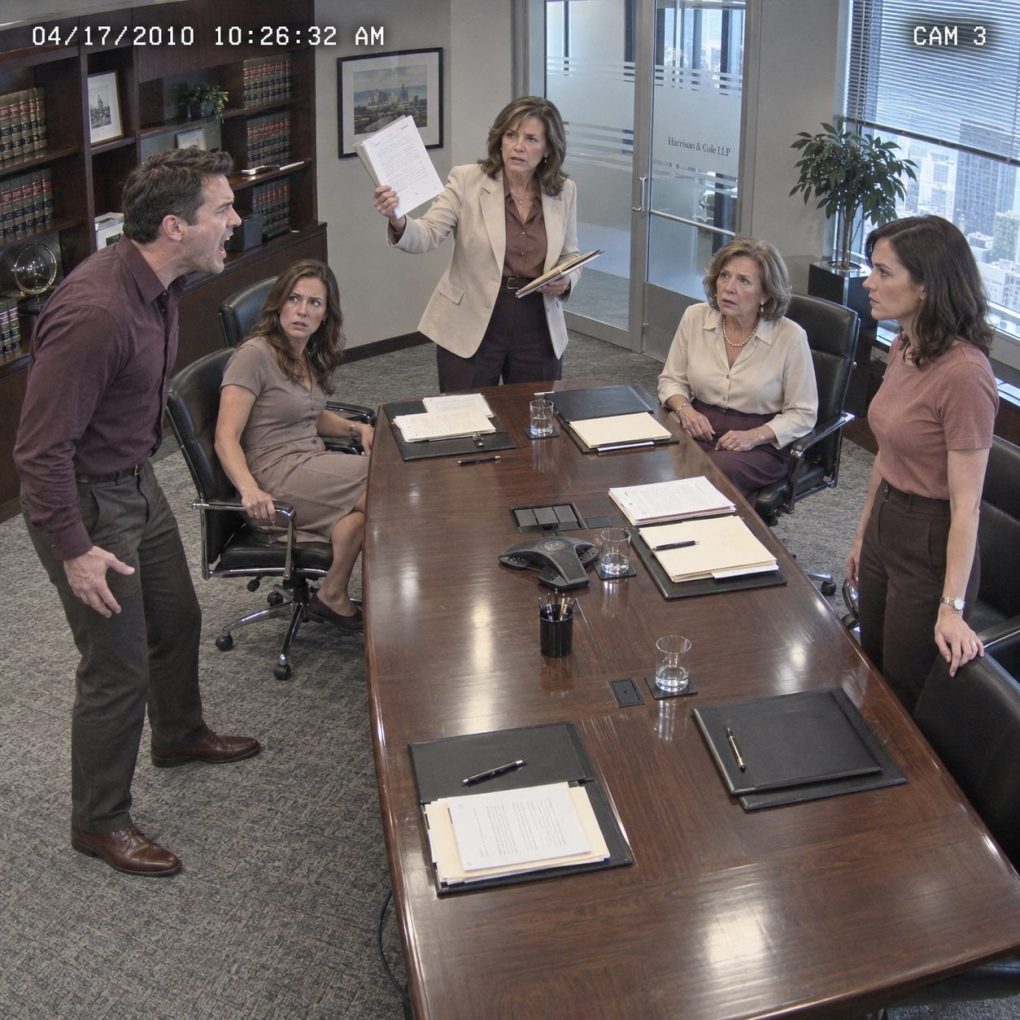
“Nothing to say as usual?” my brother Mason mocked when I took the last empty chair in our grandfather’s attorney’s conference room. My sister Olivia laughed under her breath and whispered that I had always been good at letting “real adults” handle money. I folded my hands in my lap and said nothing.
Grandfather had died three weeks earlier at eighty-seven. He founded Halbrook Industrial Supply in Ohio, a company that now operated warehouses across six states and employed more than nine hundred people. My siblings assumed the meeting was about dividing his estate.
Mason had already been discussing what he would do with “his third.” Olivia told our mother she planned to sell Grandfather’s lake property immediately. Neither of them asked why I had arrived with the company’s general counsel.
Attorney Margaret Sloan opened a thick folder. “Before we discuss the remaining personal estate,” she said, “there is something all beneficiaries need to understand about Halbrook Industrial.”
Mason smiled at me. “Finally, the interesting part.” Margaret looked over her glasses and replied, “Your sister already owns controlling interest in the company.”
Nobody moved. Olivia’s smile remained frozen for a second too long.
Margaret explained that five years earlier, Grandfather transferred fifty-two percent of Halbrook Industrial’s voting shares into a holding company legally owned by me. The transfer had been documented, taxed, reviewed by outside counsel, and disclosed in corporate filings available to shareholders.
Mason laughed once. “That’s impossible. She works in consulting.” I finally looked at him and said, “No. That’s what I told people who weren’t involved in the company.”
Margaret placed another document on the table. I had been Halbrook Industrial’s chief executive officer for five years, operating publicly inside the business under my married surname, Caroline Reed, while most extended relatives still knew me as Caroline Halbrook.
Then came the part that erased every trace of amusement from the room. Grandfather’s will left me his remaining non-voting company shares, investment portfolio, commercial real estate interests, and controlling stake in the family holding trust.
The approximate value was $46.8 million. Mason received Grandfather’s restored 1967 Mustang and $250,000. Olivia received $250,000 and a collection of jewelry Grandmother had asked her to have.
Mason stood so quickly his chair rolled backward into the wall. “You knew about this?” he demanded. I told him I knew about the company structure, but not the final distribution of Grandfather’s personal estate.
Olivia turned toward Margaret. “He would never leave almost everything to her.” Margaret calmly slid copies of the signed will, trust amendments, medical capacity assessment, and witness statements across the table.
Grandfather had anticipated the accusation. Eighteen months before his death, he voluntarily underwent an independent cognitive evaluation before updating the estate plan. The physician found no impairment affecting his ability to make financial decisions.
Mason asked why Grandfather would “punish” them. Margaret corrected him. “The will does not describe this as punishment.”
Then she read a letter Grandfather had instructed her to share. He wrote that ownership of the company should follow responsibility, not blood alone. For twenty years, he had watched which grandchildren treated Halbrook Industrial as a source of work and which treated it as an eventual payout.
I started there at twenty-three as a procurement analyst. Nobody gave me an executive office. I spent years in warehouses, supplier meetings, inventory audits, and regional operations before Grandfather ever discussed succession with me.
Mason had briefly worked in sales after college. He quit after eight months because he hated travel and later asked Grandfather three times to buy into business ideas that never produced revenue.
Olivia had never worked at Halbrook. She was successful in real estate marketing, but whenever Grandfather discussed the company, she openly called manufacturing “boring old-money stuff.”
Five years earlier, when Grandfather stepped back after heart surgery, the board interviewed four CEO candidates. I was one of them. The directors—not Grandfather alone—voted to appoint me.
We did not announce it to the family because there was nothing secret about it inside the industry. My executive biography, trade interviews, and annual reports all used Caroline Reed, the name I had taken after marriage.
Mason stared at me as though I had committed fraud by not advertising my career at Christmas dinner. “You let us think you were just some consultant.”
I reminded him that every time he asked about my work, he interrupted within thirty seconds. Olivia once told me supply-chain discussions made her “want to fall asleep.”
Our mother finally spoke. “Caroline, why didn’t you tell me?” I said, “I tried. You told me Mason needed more encouragement because I had always been independent.”
The estate meeting lasted another two hours. Nobody stormed out with millions, and nobody overturned a table. Real wealth transfers involve signatures, valuations, tax counsel, trustees, and months of administration.
Mason hired his own attorney within a week. He challenged nothing after that attorney reviewed the documents and explained how difficult it would be to contest a plan created over several years with independent legal and medical safeguards.
Olivia called me repeatedly. Her first messages were angry, then wounded, then strangely practical. By the sixth call, she asked whether I intended to “cut everyone out forever.”
I told her there was nothing to cut her out of. The company was not a family checking account. It had employees, lenders, customers, pension obligations, and a board that expected me to run it responsibly.
The $46.8 million figure also sounded simpler than reality. Much of it was tied to company equity, commercial property, and long-term investments. I did not suddenly have forty-six million dollars sitting in cash.
That distinction mattered to Grandfather. He had spent decades watching relatives confuse ownership with spending money. His final letter said, “Protect the engine before anyone argues over the fuel.”
Mason eventually apologized, though not elegantly. He said he had mistaken my silence for lack of ambition. I told him silence and ignorance are not the same thing.
Olivia’s apology took longer. She admitted that she and Mason had spent years defining me as “the quiet one” because it made their own personalities feel bigger. I appreciated that more than any polished speech.
I kept both of their inheritances exactly as Grandfather wrote them. I did not increase them out of guilt, and I did not reduce anything out of anger. His decisions remained his.
Six months later, Halbrook Industrial acquired a smaller distribution company in Indiana. The deal added eighty-seven employees and expanded our medical-equipment division. At the closing dinner, nobody cared who my siblings thought I was.
A year after Grandfather’s death, Mason visited headquarters for the first time since college. He stood outside the executive conference room and stared at the wall displaying photographs of company presidents.
My photograph had been there for five years. Under it were five annual reports, three industry awards, and a brass plaque with my full title: Caroline Reed, Chief Executive Officer.
Mason looked at the wall and gave a short, embarrassed laugh. “So everyone knew except us.”
I said, “Everyone who ever bothered to ask.”
Grandfather did not leave me his fortune because I was his favorite. He left me control because for five years before his death, I had already been carrying the thing everyone else was waiting to inherit.