My parents skipped my son’s first birthday and calmly told me, “We don’t recognize him as our grandson.” I told them never to ask me to pay another bill. Dad laughed—until an email exposed the $148,000 secret they never expected me to discover.
I was carrying my son’s first birthday cake toward the table when my phone buzzed with a message from my mother.
We’re not coming.
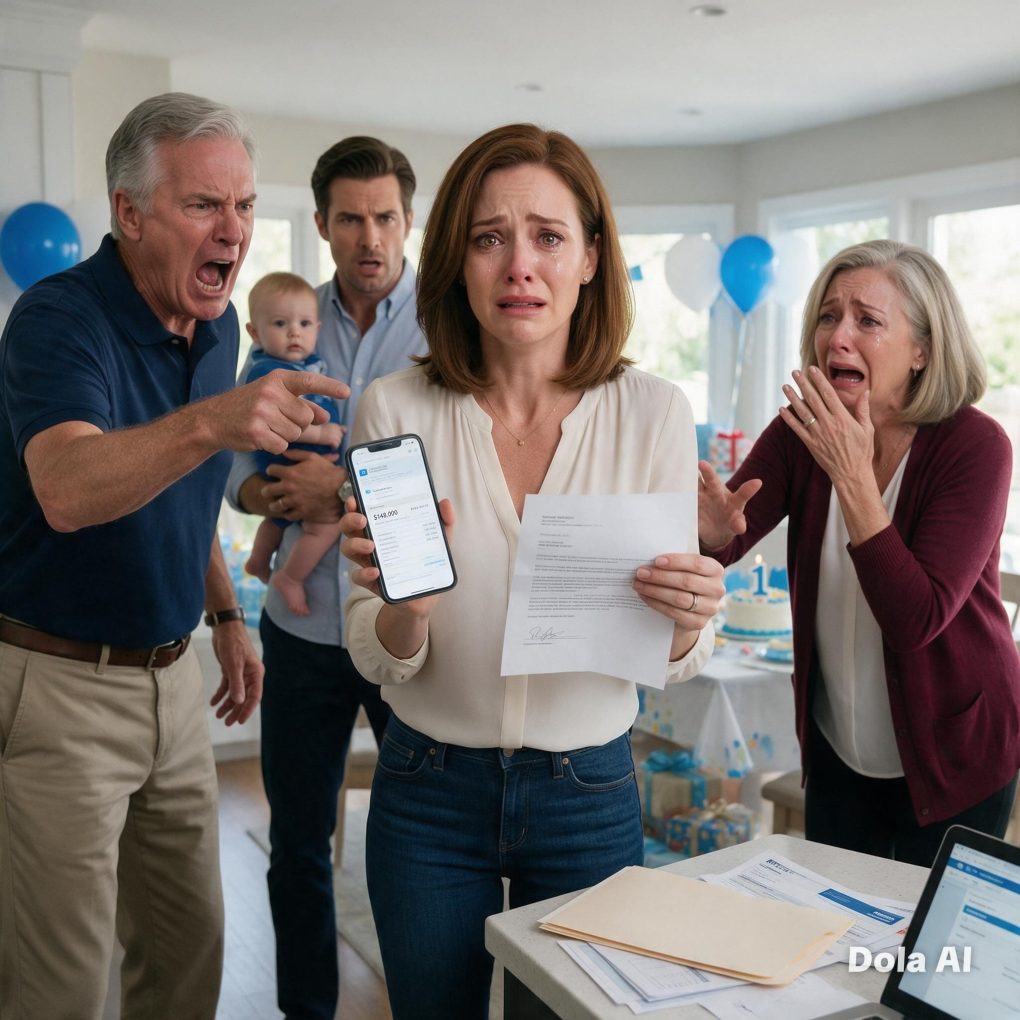
I stared at the screen, then called her immediately. Twenty relatives and friends were already in my backyard in Columbus, Ohio. Blue balloons covered the fence. My husband, Mark, was helping our one-year-old son Noah tear wrapping paper off a toy truck.
Mom answered on the fourth ring.
“Is Dad sick?” I asked.
“No,” she said flatly. “We talked about it. Honestly, we just don’t need this.”
“Don’t need what?”
“This whole grandparent thing with Noah,” she replied. “We don’t recognize him as our grandson. It’s better if everyone stops pretending.”
For a second, I couldn’t speak.
My father took the phone from her.
“You heard your mother,” he said. “Don’t make a scene on the kid’s birthday.”
The cruelty of that sentence almost made me laugh.
For three years, I had paid their property taxes when Dad fell behind. I covered Mom’s dental work, their car insurance, their electric bill, and the $1,850 monthly mortgage payment they kept calling “temporary help.” Whenever they were short, I transferred money. Whenever Dad said family took care of family, I believed him.
But apparently family had a limit, and that limit was my son.
I looked through the patio doors at Noah clapping while Mark lit one tiny candle.
“Okay,” I said.
Dad sounded surprised. “Okay?”
“Yes. You don’t recognize my son as family. I’m not going to argue with you. But don’t come asking me for money for your debts, bills, repairs, taxes, or emergencies anymore.”
Dad actually laughed.
“You’ll calm down tomorrow.”
“No,” I said. “I won’t.”
“You always say that when you’re upset.”
“I’ve never said it before.”
He chuckled again. “Emily, who do you think you’re punishing? We managed before you started playing banker.”
That was another lie, but I didn’t correct him.
I ended the call, opened my banking app, and canceled every automatic payment connected to their household. Then I forwarded one short instruction to my accountant, Rachel Kim: End all family support transfers today. Revoke every authorization connected to Robert and Diane Harper. Send written confirmation.
Ten minutes later, as everyone sang “Happy Birthday,” my father called three times.
I ignored him.
Then a new email appeared on my phone.
It wasn’t from Dad.
It was from First Franklin Bank’s fraud department.
Subject: Immediate verification required — Robert and Diane Harper refinance.
The first line made my stomach drop.
Ms. Harper, before tomorrow’s funding, we need you to confirm the personal guaranty bearing your electronic signature.
I had never signed a guaranty.
And the amount underneath it was $148,000.
I stepped away from the birthday table and called the number in the email.
A fraud specialist named Marcus Lee answered after verifying my identity.
“You’re listed as a non-occupant guarantor on a cash-out refinance for your parents’ home,” he said. “The application says you agreed to guarantee $148,000.”
“I did not.”
“Then I’m freezing the funding.”
Marcus sent me a secure copy of the file. My name was everywhere. My address. My income. My consulting company. Even an old tax return I had given my parents two years earlier.
At the bottom was an electronic signature that looked almost like mine.
Almost.
I never signed my middle initial that way.
Mark found me outside staring at the screen.
“My parents tried to put me on a loan,” I said.
His face changed immediately.
I called my accountant, Rachel Kim, then an attorney she trusted, Daniel Price. Daniel told me to freeze my credit, preserve every email, and file an identity-theft report before speaking to my parents again.
At 7:16 p.m., Dad left a voicemail.
“What did you do to the bank? They suspended the refinance. Call me now.”
No apology about Noah.
Only panic about money.
The next morning, Marcus called again.
The application claimed my parents needed the cash for medical debt and roof repairs—the same emergencies they had used to ask me for money all year.
Except the attached statements told a different story.
There was no major medical balance.
No roofing contract.
Their mortgage was only $61,000.
“So where was the rest going?” I asked.
“To a title company in Florida.”
My parents were under contract to buy a condo near Sarasota. They had already wired a $32,000 deposit.
Then Rachel called with something worse.
For thirty-four months, I had transferred money into their household account for “necessities.” Total: $126,400.
But much of it had been moved into a separate savings account.
Current balance: $93,700.
They had not been drowning.
They had been building a retirement fund with my money while telling me they were one missed payment from losing the house.
I called Dad.
“You forged my signature.”
“We were going to pay everything back after the house sold,” he shouted.
“So you admit it?”
Silence.
Then Mom grabbed the phone.
“You owed us. Do you know what raising a child costs?”
I looked at Noah sleeping against Mark’s chest.
“You just said my child wasn’t your family.”
“That has nothing to do with this.”
“It has everything to do with this.”
Her voice dropped. “If you report this, your father could be charged.”
Before I answered, Marcus called again.
“We found a second document,” he said. “A notarized affidavit saying you appeared in person and confirmed the guaranty.”
“I never did.”
“The notary’s log says you were there last Tuesday at 2:40 p.m.”
I went cold.
Last Tuesday at 2:40 p.m., I had been at Noah’s pediatrician appointment.
And I had video proving it.
The clinic also had a timestamped check-in record, a credit-card receipt, and security cameras at the front desk.
For the first time, this was no longer just my word against theirs.
That video became the piece my parents had not expected.
By noon, Daniel had sent the pediatrician records and timestamped clinic footage to First Franklin Bank’s fraud team. The bank permanently canceled the refinance and referred the forged affidavit for investigation.
The notary was Carol Jensen, my mother’s friend of almost fifteen years.
When an investigator contacted Carol, she first insisted that I had appeared before her. Then she was shown a still image from the pediatrician’s office with the exact timestamp.
Her story collapsed.
Two days later, Carol admitted Dad had brought her the affidavit already completed, along with a photocopy of my driver’s license. He told her I was “too busy with the baby” to come in and claimed I had approved everything. Mom was sitting beside him.
Carol notarized it anyway.
That confession changed everything.
Dad stopped calling me angry and started calling me desperate.
“Emily, please,” he said in one voicemail. “We can fix this privately.”
Mom sent message after message.
Think about your father.
We are still your parents.
Families do not call police on each other.
You are destroying our retirement.
Their retirement.
That was what Noah’s birthday had exposed.
For years, they had treated my love like an unlimited line of credit. Every crisis sounded urgent. A tax bill. A broken water heater. Dental work. A late mortgage payment. I never demanded receipts because I thought helping them was what a good daughter did.
Meanwhile, they were saving part of my money and preparing to move to Florida.
Daniel helped me organize every transfer, text, and email. Some payments truly covered household expenses. Others had been requested with claims that were clearly false.
One email from Dad said the bank would “take the house by Friday” unless I sent $6,000.
Their mortgage statement showed they had been current.
Another message from Mom said she needed $4,800 for emergency dental surgery.
The actual out-of-pocket cost had been under $900.
I felt stupid until Daniel said, “Trusting your parents is not the same as authorizing fraud.”
That sentence stayed with me.
The Florida condo deal collapsed when my parents could not complete financing. Their lender froze the application, and they lost part of their deposit.
Then Dad tried to control the story.
He told my aunt and several relatives that I had cut off my “elderly parents” over a birthday invitation.
My aunt called me crying.
“How can you do this over one party?”
I answered, “They forged my signature on a $148,000 financial document. The bank is investigating. This is not about cake.”
The family pressure stopped that evening.
Three weeks later, my parents sat across from me in Daniel’s conference room.
Their attorney did most of the talking.
The criminal investigation would continue separately, but they wanted to settle the financial dispute. My parents would return $78,000 from the savings they had built through false claims, reimburse my legal fees, and sign a written acknowledgment that I was not responsible for any debt, loan, refinance, or contract they had attempted to place in my name.
I agreed after Daniel reviewed everything.
Then Mom finally looked at me.
“So that’s it? You take our savings and walk away?”
“No,” I said. “I take back part of what you took from me.”
“We raised you.”
“And I helped you because I loved you.”
Dad leaned forward. “After everything we sacrificed, you think you owe us nothing?”
I thought about Noah’s empty grandparent chairs.
“I don’t owe you access to my bank account.”
Mom’s eyes filled with tears.
“What about seeing Noah?”
There it was.
Not an apology.
A negotiation.
“You said you didn’t recognize him as your grandson,” I said. “You don’t get to erase that because the money stopped.”
Dad looked down.
The legal consequences took months. Carol lost her notary commission and cooperated with investigators. Dad eventually pleaded guilty to a fraud-related charge and received probation, restitution requirements, and community service. Mom entered a court-approved diversion program and completed financial counseling.
I did not celebrate any of it.
I also did not rescue them.
They sold their house that winter, paid off the remaining mortgage, and moved into a smaller rental outside Dayton.
The first time Dad called to say the rent was “killing them,” I felt the old reflex rise.
Open the banking app.
Send the money.
Fix the emergency.
Instead, I said, “I hope you find a solution.”
Then I hung up.
A year after the birthday they refused to attend, we celebrated Noah turning two.
There were no empty chairs waiting for people who had chosen not to come.
Mark grilled burgers. My aunt brought cupcakes. Rachel arrived with a toy fire truck. Our friends filled the backyard with noise.
Halfway through the party, my phone buzzed.
A message from Mom.
Happy birthday to Noah. We know we have a lot to repair. We are sorry.
I stared at it for a long time, then put my phone face down.
Maybe one day there would be a carefully supervised conversation. Maybe there would not.
Forgiveness, I had learned, did not require immediate access.
Noah ran toward me with frosting on his cheek and lifted both arms.
“Mommy!”
I picked him up as everyone started singing.
This time, I did not look toward the gate.
I looked at my son.
My parents had laughed when I told them not to ask me for money again because they thought my boundary was temporary.
They were wrong.
The real surprise in their inbox had never been the canceled payments.
It was the proof that I had finally stopped confusing being useful with being loved.