“Dad, the bank said if we don’t fix this by noon, we lose the mansion.”
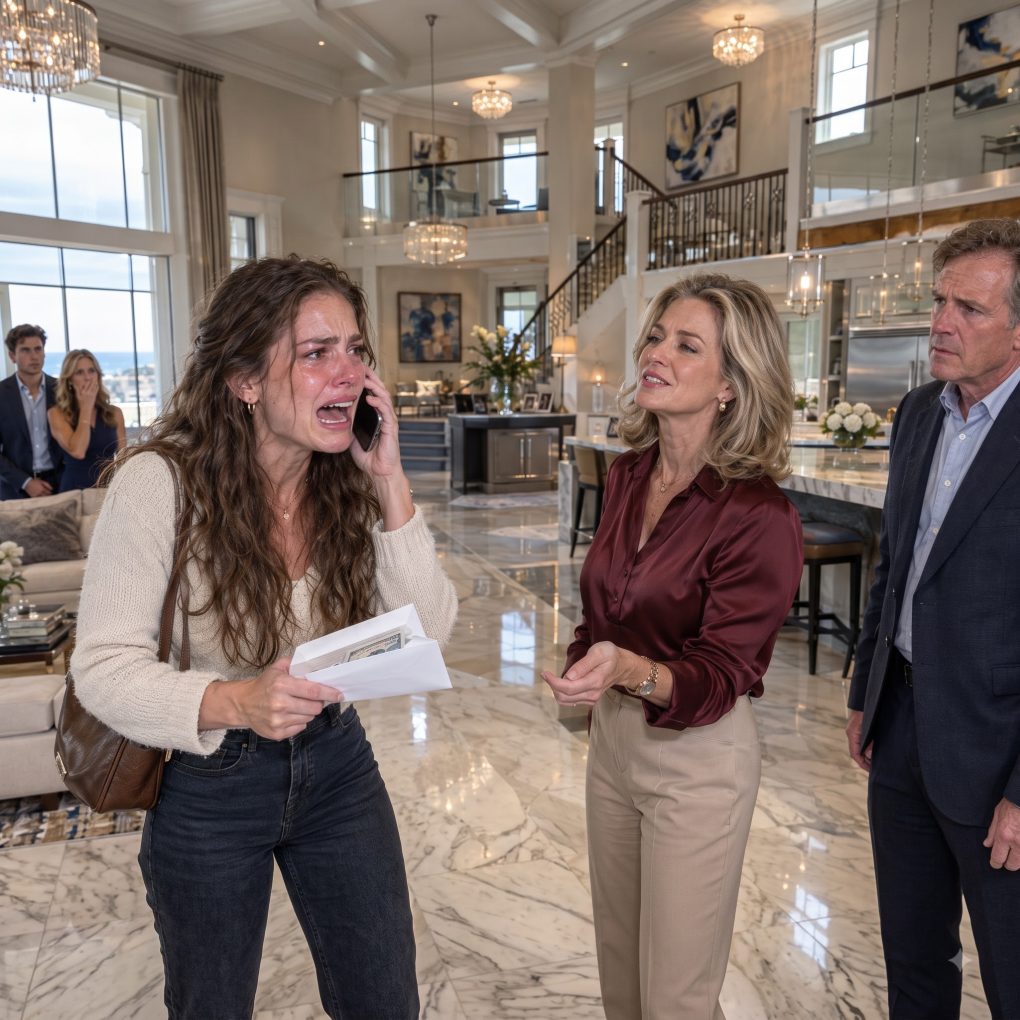
I was standing in their marble foyer when he shoved a folder into my hands.
The $5 million house had been bought with money I had given my parents to invest for me. Now the mortgage was in trouble, and they needed me to rescue it.
“Do everything the lender asks,” Dad said. “We’ll pay you the $950,000 when it’s done. Every penny.”
Mom nodded. “You have our word.”
For three straight days, I handled everything. I gathered statements, called the title company, corrected insurance paperwork, answered the lender’s questions, and drove across town for signatures. By Friday afternoon, the bank emailed confirmation: the recovery process was complete.
Dad hugged me.
“You saved our home.”
I waited.
Instead of the promised payment, Mom handed me a thin white envelope.
I opened it.
A cashier’s check for $950.
I stared at it.
Mom smiled. “That’s all you’re getting.”
Dad avoided my eyes.
I looked from one parent to the other. “Where’s the rest?”
Mom shrugged. “Consider the other $949,050 a family expense.”
I felt something inside me go completely cold.
I could have screamed. I could have threatened them.
Instead, I folded the check, placed it back inside the envelope, and said nothing.
Dad gave a satisfied sigh, as if the argument were over.
Then my phone rang.
I glanced at the screen.
It was the bank.
“Hello?”
The woman on the other end sounded tense.
“Ms. Carter, please stay where you are. We’ve just discovered something concerning about the $5 million mortgage.”
I looked at my parents.
Dad’s face changed instantly.
“What did you find?” I asked.
The banker paused.
“Someone has placed the entire loan under an emergency fraud review.”
My mother stopped smiling.
Teaser
I thought the $950 check was the final insult. Then the bank uncovered something buried inside the mortgage records that made my parents panic—and suddenly, the mansion they thought they had secured was no longer safely theirs.
The banker lowered her voice.
“Before we placed the account on hold, our fraud team found a second mortgage modification request attached to your parents’ file.”
“A second request?”
“Yes. It lists you as a consenting party.”
My stomach tightened. “I never signed one.”
There was silence.
Then she asked, “Did your parents recently ask you to complete lender documents?”
“Yes. For three days.”
“Those documents were legitimate. But someone also submitted another packet using a signature that does not match the signature on your original account.”
I looked at Dad.
He had gone pale.
Mom whispered, “This is getting out of hand.”
I turned back to the banker. “What happens now?”
“The $5 million mortgage is under an administrative freeze. No foreclosure action, modification, sale processing, or disbursement can move forward until the review is complete.”
My father suddenly stepped toward me.
“Tell them it was a mistake.”
“A mistake?” I said.
He lowered his voice. “You know what this house means to us.”
I stared at him. “You bought it with my money.”
Dad flinched.
Then Mom snapped, “We raised you! Everything you have came from this family!”
That sentence hurt more than the $950.
The banker interrupted. “Ms. Carter, there is one more issue. We found records showing that the original funds used in the purchase were transferred from an account connected to you.”
My heart stopped.
“What does that mean?”
“It means we need to determine whether your parents had authority to use those funds as they did.”
I looked at the mansion around me—the marble floor, the enormous windows, the expensive furniture I had never been allowed to question.
Suddenly, the story sounded different.
This house had never been their money.
It had been mine.
Dad grabbed the folder from the counter.
“You’re overreacting,” he said.
I stepped back.
The banker said, “Please do not sign anything else. Our investigator will contact you directly.”
Then the call ended.
Mom’s face crumpled.
Dad stared at me, no longer angry.
Now he looked scared.
And that was when I remembered something I had almost forgotten: six months earlier, Dad had asked me to sign a document he called “just a property form.”
I had refused because the numbers didn’t make sense.
He had told me I was being paranoid.
Now I wondered what that document had actually been.
My phone buzzed again.
This time, it was an email from the title company.
The subject line was simple:
URGENT: OWNERSHIP DOCUMENT DISCREPANCY
I opened it.
And the first sentence made my hands shake.