The cashier’s check was sitting in front of me when I realized my parents had never intended to keep their promise.
I looked at the amount again.
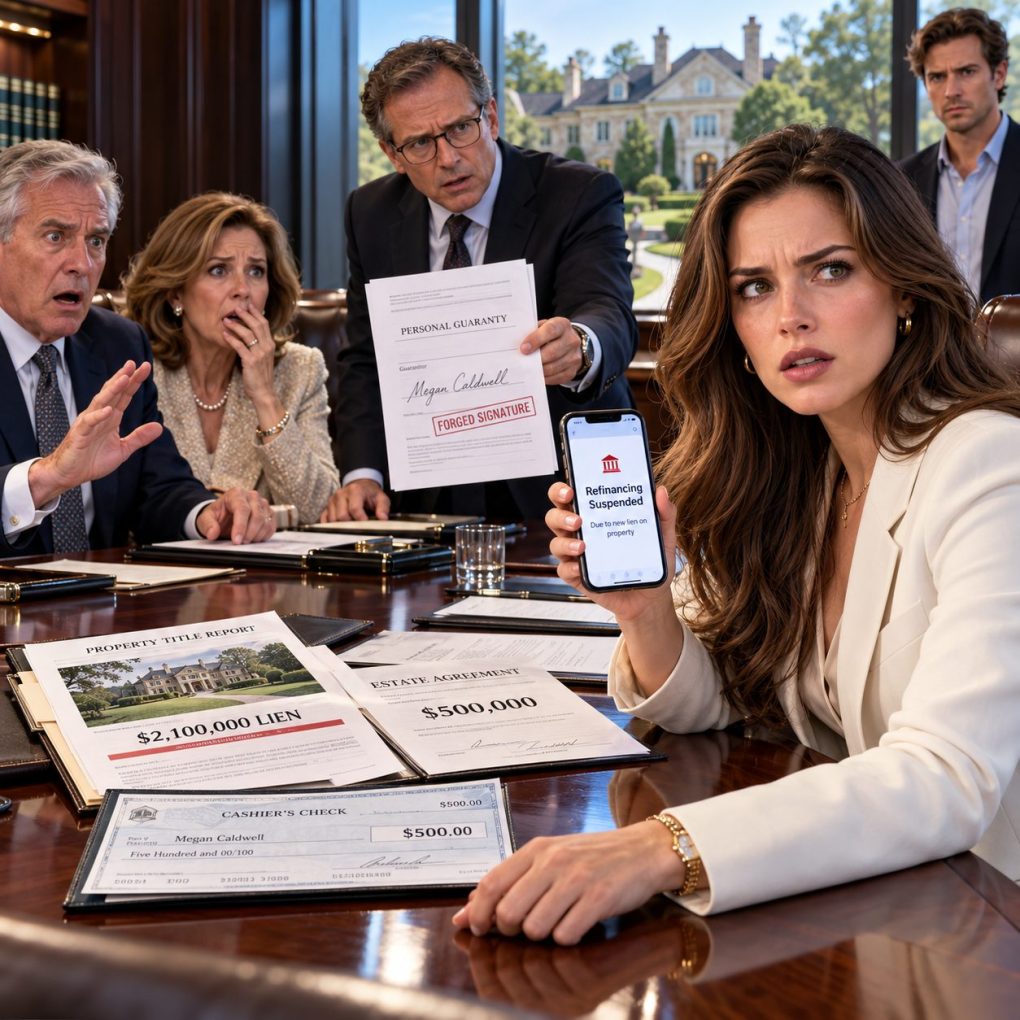
$500.00.
Not $500,000.
Five hundred dollars.
My father, Richard Caldwell, leaned back in the leather conference-room chair like we were discussing a dinner bill instead of the agreement that had consumed six months of my life.
“There’s your payment, Megan,” he said.
I stared at him. “You agreed to five hundred thousand.”
Mom folded her hands over her designer purse. “We agreed to compensate you. We never said you should profit off your own family.”
Actually, they had.
In writing.
Twice.
The first agreement had been signed in February. The second had been reviewed by their attorney three weeks later.
If I stopped Caldwell Ridge from falling into foreclosure, refinanced the debt, and protected the family’s Virginia estate from being sold at auction, I would receive a $500,000 success fee.
Caldwell Ridge wasn’t just a house.
It was 214 acres outside Charlottesville, with a main residence built in 1911, two guest cottages, a horse barn, and land appraised at $10.4 million.
It had been in Dad’s family for four generations.
And at exactly noon that day, the lender’s final forbearance expired.
The clock on the conference-room wall read 11:56.
Four minutes.
For months, I had negotiated with banks, accountants, title attorneys, and private lenders after discovering my parents were far deeper in debt than they had admitted.
Eventually, I found a refinancing package that could stop the foreclosure.
There was one problem.
The bank required an additional guarantor.
Me.
I had agreed because my parents promised the estate would remain intact and because the signed documents showed enough equity to protect me.
Now Dad pushed the $500 check closer.
“You should be grateful,” he said. “Most daughters would have done this for free.”
Something inside me went completely still.
“Is this really what you’re doing?”
Mom sighed. “Please don’t create a scene.”
11:57.
Their attorney, Martin Ellis, suddenly became very interested in the papers in front of him.
That bothered me.
Martin had personally reviewed my compensation agreement.
I turned toward him.
“Has the refinancing funded yet?”
His head snapped up.
Dad answered first.
“It’s done.”
“That wasn’t my question.”
Martin hesitated.
“The wire has been authorized,” he said carefully. “But the lender hasn’t released funds from escrow yet.”
Dad’s face changed.
Just slightly.
But I saw it.
I reached for my phone.
Mom leaned forward. “Megan.”
I opened the email from the bank and found the number for Samantha Reed, the senior loan officer handling the transaction.
Dad stood.
“What are you doing?”
I called her.
She answered immediately.
“Samantha, this is Megan Caldwell. I am withdrawing my personal guaranty before disbursement.”
Silence.
Then keyboard clicks.
“Megan, I need you to confirm that instruction.”
“I confirm it.”
Dad slammed his palm onto the table.
“You can’t do that.”
Samantha’s voice came through the speaker.
“Yes, she can. The loan has not funded.”
11:58.
Mom went white.
Then Martin’s computer chimed.
He stared at the screen.
His expression changed so fast that everyone noticed.
“What?” Dad demanded.
Martin didn’t answer him.
He looked directly at me.
“Megan, there’s something on the title report that wasn’t there yesterday.”
My stomach tightened.
“What kind of something?”
He swallowed.
“A new lien.”
Dad stopped moving.
Mom whispered his name.
And that was when I understood the $500 check wasn’t the worst thing they had done.
It was just the first thing I had caught.
What appeared on that title report changed the entire meaning of the deal. My parents hadn’t simply decided to cheat me out of money. Someone had quietly placed millions of dollars at risk, and somehow my name had been pulled into it too.
Martin turned his monitor toward me.
A $2.1 million deed of trust had been recorded against Caldwell Ridge nine days earlier.
The borrower was a company called Blue Ridge Development Holdings.
I had never heard of it.
Then I saw the managing member.
Daniel Caldwell.
My brother.
I looked at Dad.
“You borrowed against the estate for Daniel?”
“It’s temporary,” he said.
Martin interrupted him. “Richard, this wasn’t disclosed to the refinancing lender.”
Mom’s voice sharpened. “Because it was supposed to be paid off after closing.”
Everything clicked into place.
The new bank loan I had agreed to guarantee was supposed to refinance approximately $4.3 million of existing obligations.
But my parents had added another $2.1 million after underwriting was substantially complete.
If the new loan funded without the bank discovering it, part of the collateral securing my guaranty had already been pledged elsewhere.
“You were going to let me guarantee this without telling me?”
Dad looked furious that I had figured it out.
“We were protecting your brother.”
I actually laughed.
Not because anything was funny.
Because suddenly the $500 check made perfect sense.
They had promised me $500,000 because they needed me cooperative until the money cleared.
Once the refinance funded, my leverage disappeared.
11:59.
Martin grabbed the phone.
“We need to inform the lender immediately.”
Dad reached across the table.
“Don’t.”
Martin stared at him.
“You recorded undisclosed debt nine days before closing.”
“It’s family business.”
“No,” Martin replied. “Now it’s lender business.”
The wall clock clicked to noon.
An email notification appeared on my phone.
REFINANCING TRANSACTION SUSPENDED.
Thirty seconds later another arrived from the existing lender.
FORBEARANCE PERIOD EXPIRED.
Mom began crying.
“You’ve destroyed everything.”
I looked at her.
“No. I stopped you from attaching my name to something you hid from me.”
Then the conference-room door opened.
Daniel walked in.
He wasn’t surprised to see me.
That was the second warning.
Dad immediately said, “Tell her.”
Daniel shut the door behind him.
“Megan, withdrawing now doesn’t solve anything.”
“What does that mean?”
He placed a folder on the table.
Inside was another personal guaranty.
My name appeared on the first page.
My initials appeared on six more.
And on the final page was what looked like my signature.
For a few seconds, I couldn’t process it.
Martin took the document.
His face drained of color.
“This is notarized.”
Mom wouldn’t look at me.
I read the date.
Three weeks earlier.
“This isn’t my signature.”
Daniel crossed his arms.
“The lender has a signed guaranty.”
“I never signed this.”
Dad spoke quietly.
“Maybe you don’t remember every document you signed.”
I turned toward him slowly.
Then I understood why nobody seemed terrified when I withdrew my real guaranty.
They believed they had another one.
One they could use without me.
I took a photo of the document.
Then another.
Daniel reached for the folder.
I pulled it away.
“Megan,” Mom said, “don’t make this worse.”
My hands were shaking now, but my voice wasn’t.
“Who notarized this?”
Nobody answered.
Martin flipped to the acknowledgment page.
His eyes stopped on the seal.
“Oh, God.”
I knew the name too.
Patricia Holloway.
My mother’s best friend for almost thirty years.
And a commissioned Virginia notary.
Martin looked at me.
“If you truly didn’t sign this, we’re no longer dealing with a family dispute.”
Daniel finally lost his confidence.
Dad sat down.
And my mother began begging me not to call anyone.
The strangest thing about discovering that your own family may have forged your signature is how quickly ordinary details become evidence.
Three weeks earlier, on the date Patricia Holloway supposedly watched me sign that guaranty in Albemarle County, Virginia, I had been 600 miles away.
I was in Chicago.
Not “I think I was in Chicago.”
I could prove it.
I had flown out of Richmond that morning for a commercial real estate conference. My airline account showed the boarding pass. My hotel had my check-in record. I had used my credit card at a restaurant near McCormick Place that evening, and there were photographs of me speaking on a panel in front of several hundred people.
The notarized document claimed I had personally appeared before Patricia in Virginia at 3:18 p.m.
At 3:18 p.m., I was standing beside a projector screen in Chicago discussing distressed-property restructuring.
I looked at Martin.
“I want the bank’s fraud department.”
Mom grabbed my wrist.
“Megan, please.”
I pulled my arm away.
“For six months, you told me Caldwell Ridge was in trouble because interest rates increased and Dad had made some bad business decisions.”
“That’s true,” she said.
“Some of it may be true. What else don’t I know?”
Nobody answered.
Martin made the call.
Once the words “disputed guaranty” and “possible forged notarization” were spoken, everything changed.
The refinancing lender froze the transaction.
The title company placed the closing file under internal review.
Martin instructed everyone not to alter, destroy, or remove any documents connected with the transaction.
Daniel looked like he wanted to run.
I sat across from my parents and waited.
Eventually Dad spoke.
“You have no idea what your brother has been dealing with.”
There it was.
Not denial.
Justification.
Daniel had launched a luxury home-development company four years earlier. According to the version of the story I had been told, business was booming.
He drove a Range Rover.
His wife posted photographs from Cabo.
Their children attended private school.
At Thanksgiving, Dad once spent twenty minutes telling everyone Daniel was “building the next major development company in Central Virginia.”
What nobody mentioned was that Daniel’s business had been losing money for almost two years.
Projects went over budget.
Two investors pulled out.
A subdivision outside Richmond stalled after permitting problems.
Then suppliers began demanding payment.
Daniel borrowed to cover old loans, then borrowed again to cover those.
Dad started helping.
First $200,000.
Then $400,000.
Then more.
“How much?” I asked.
Dad stared at the table.
“How much family money went into Daniel’s company?”
Mom answered.
“About $1.7 million.”
Daniel immediately said, “That includes investments.”
“Investments that are worth what today?”
Silence.
Martin rubbed his forehead.
“And the $2.1 million lien?”
Daniel explained that a private lender had agreed to advance emergency capital if Caldwell Ridge secured the loan.
My parents approved it.
They knew recording the lien before my refinancing closed could jeopardize the new loan, but Daniel insisted he would lose one of his developments unless the money arrived immediately.
So they gambled.
The plan was breathtakingly simple.
Use Caldwell Ridge again.
Keep the new lien quiet.
Let my refinance close.
Use part of the new liquidity to stabilize Daniel’s business.
And rely on my personal guaranty to make the bank comfortable enough to release the funds.
“What about the forged document?” I asked.
Daniel looked at Mom.
Mom looked at Dad.
Dad finally looked at me.
“We needed a backup.”
I felt something inside me break.
Not dramatically.
Quietly.
Like a thread finally snapping after being pulled too tight for years.
“You forged my signature as a backup?”
Dad’s jaw tightened.
“We believed you would sign.”
“That is not the same thing.”
“You were already helping.”
“That is not the same thing.”
“We were going to explain after everything stabilized.”
I stared at him.
“You mean after I could no longer stop you.”
He didn’t answer.
That silence told me everything.
Patricia arrived twenty minutes later.
Mom had apparently texted her before Martin told everyone to preserve communications.
Patricia walked into the office looking terrified.
She barely made it past the door before saying, “I didn’t know what they were doing.”
Martin stood.
“Patricia, you should probably obtain independent counsel before saying anything else.”
That was enough.
Whatever explanation my parents had prepared was finished.
The title company requested copies of every document Patricia had notarized for the family during the previous year.
The refinancing lender requested the original guaranty.
The private lender behind Daniel’s $2.1 million loan was notified that the closing had failed.
Then another problem surfaced.
A much bigger one.
When investigators began comparing the debts against the property’s title, they discovered Caldwell Ridge wasn’t carrying $4.3 million in obligations.
It was carrying almost $9.6 million.
There was the primary mortgage.
A business line secured by the estate.
Daniel’s new $2.1 million lien.
Back property taxes.
A judgment connected to one of Dad’s failed partnerships.
And another loan my parents had taken against a separate parcel that was legally part of Caldwell Ridge.
The famous $10 million family estate barely had any real equity left.
For years, my parents had maintained the appearance of wealth by borrowing against the thing that represented our wealth.
The house.
The land.
The family name.
All of it was leveraged.
I finally understood why they had been willing to promise me $500,000.
It wasn’t because they planned to pay it.
They needed me to believe there was enough money to pay it.
The success fee had never been compensation.
It had been bait.
Two days later, the original lender refused to extend the forbearance again.
My parents asked me to reconsider.
Then they begged.
Then they became angry.
Mom called twelve times in one afternoon.
Dad left a voicemail saying four generations of Caldwells would remember that I was the person who let the estate disappear.
I saved the voicemail.
I never answered it.
The foreclosure process moved forward.
There was still time for my parents to sell Caldwell Ridge voluntarily, but every realistic offer required them to accept the truth: after paying secured creditors, taxes, closing costs, and legal expenses, almost nothing would remain.
Dad refused.
He kept insisting the property was worth at least $10 million.
Maybe it was.
But a $10 million asset with nearly $10 million of obligations is not a $10 million fortune.
It is a highly decorated financial emergency.
Three months later, Caldwell Ridge was sold through a court-supervised process to a regional hospitality company.
They paid less than my parents wanted but enough to satisfy most of the secured debt.
The antique furniture went to auction.
The horses were moved to another farm.
My mother’s annual Christmas gala ended after twenty-seven years.
The brass plaque bearing our family name remained beside the front gate for a few weeks.
Then one morning, it was gone.
That photograph hurt more than I expected.
I had loved that property.
I learned to ride a bicycle on its gravel driveway.
My grandmother taught me to bake biscuits in that kitchen.
My grandfather used to walk me through the orchard and tell me which trees his father had planted.
Losing Caldwell Ridge felt like watching part of my childhood disappear.
But I had to remind myself of something important.
I had not mortgaged it repeatedly.
I had not hidden the debts.
I had not forged anyone’s signature.
I had simply refused to become the final person holding the bill.
The investigation into the guaranty continued for months.
Patricia eventually admitted she had notarized the document without seeing me sign it. She claimed Mom told her I had already approved everything and that obtaining another signature was merely a technical formality.
Her notary commission was revoked.
Daniel’s attorney negotiated with prosecutors after evidence showed that he had emailed the unsigned guaranty to my parents with instructions about where my signature needed to appear.
He eventually pleaded guilty to charges connected with falsifying financial documents. He avoided prison, but received probation, restitution obligations, and a record that effectively ended his ability to raise institutional money for his development company.
His company collapsed soon afterward.
My parents were not charged with the same offenses Daniel was, but the civil consequences were brutal.
Creditors pursued remaining assets.
They sold their vehicles.
They moved into a two-bedroom condominium outside Richmond.
The people who had once hosted charity dinners beneath crystal chandeliers were suddenly arguing over storage-unit fees.
Six months after Caldwell Ridge was sold, Mom asked to meet me.
We chose a quiet coffee shop halfway between Richmond and Charlottesville.
She looked smaller than I remembered.
Not physically.
Just somehow diminished.
She placed something on the table.
The original $500 cashier’s check.
I had never deposited it.
Martin had kept it with the closing records and eventually returned it to her.
Mom pushed it toward me.
“I suppose you want this.”
I looked at the check.
Then at her.
“No.”
Her eyes filled.
“I know you think we chose Daniel over you.”
“I don’t think that.”
She seemed surprised.
“I know you did.”
She looked down.
For once, there was no argument.
No explanation.
No speech about family loyalty.
Just silence.
Finally she whispered, “Your father thought Daniel could fix everything if we gave him enough time.”
“And you?”
“I thought saving him meant saving the family.”
I nodded.
“That was the mistake.”
She waited.
I continued.
“You kept confusing the estate with the family. Then you confused Daniel with the estate. Eventually you were willing to sacrifice anyone necessary to protect both.”
Including me.
I didn’t need to say it.
She already knew.
Before leaving, Mom asked whether I thought I would ever forgive them.
I told her the truth.
“Maybe. But forgiveness doesn’t mean giving you access to my finances, my signature, or my future again.”
A year has passed since then.
Caldwell Ridge is now a boutique hotel and wedding venue.
For months, I refused to look at its website.
Then one evening, curiosity won.
The new owners had restored the stone exterior.
They replanted part of my grandfather’s orchard.
The old horse barn had been renovated instead of demolished.
I expected to feel angry.
Instead, I felt relieved.
The property had survived.
Just not as our family monument.
And maybe that was appropriate.
My parents spent decades believing the Caldwell name was something they could preserve with money.
Then, when the money disappeared, they borrowed against the land to preserve the appearance.
When the borrowing stopped working, they tried to borrow against me.
That was where the cycle ended.
I still have a copy of the $500,000 agreement.
I also have a photograph of that ridiculous $500 check.
Not because I plan to collect either one.
I keep them because together they remind me of the exact moment I finally understood what my parents had been asking me to save.
It wasn’t a $10 million estate.
It wasn’t four generations of history.
It wasn’t even our family.
They wanted me to save the illusion that nothing had changed.
And when they handed me $500 after promising $500,000, they assumed family loyalty would make me swallow the insult and sign away my future anyway.
Two minutes later, I withdrew my guaranty.
That decision cost them the estate they had spent their lives trying to preserve.
But it saved me from inheriting the one thing they were actually leaving behind.
Their debt.