The first thing I remember is the bathroom tile against my cheek and my phone buzzing somewhere under the sink.
I had a 103-degree fever, a kidney infection that had turned ugly overnight, and barely enough strength to crawl into the hallway. By the time my neighbor Jenna found me and called 911, I was shaking so hard I couldn’t hold water.
At the emergency room in Charlotte, the doctor said “sepsis,” and everything inside me went cold.
I’m thirty-six and run a corporate compliance firm. I’m usually the person everyone calls when something goes wrong. But that morning, with an IV in my arm, I wanted my mother.
So I called her.
“Mom, I’m in the ER.”
I could hear restaurant noise behind her.
“What happened?”
“I have an infection. They may keep me overnight. Could you come?”
She sighed. “Claire, I’m already out. I have things to do today.”
I stared at the ceiling.
“Mom, I’m scared.”
Her voice sharpened. “Don’t expect my help every time something happens. You’re an adult.”
That sentence landed harder than the diagnosis.
For almost four years, I had transferred $8,000 into my mother’s account every month. It started after my father died. She said she wanted to keep traveling, shopping, having lunches with friends, and “not live like a widow counting coupons.”
I could afford it, so I did it.
I had also bought the three-bedroom house she lived in outside Charlotte. Cash. No mortgage. The deed was in my name, but I never charged her rent. I paid the property taxes too.
She called the monthly money her “freedom fund.”
I never called it a burden.
But when I was lying in a hospital bed, genuinely afraid, she couldn’t give me an hour.
“I understand,” I said.
“Good.”
Then she hung up.
I didn’t cry.
I opened my banking app, stared at the recurring transfer scheduled for the next morning, and realized how absurd my life had become.
Then I did one thing.
I called my private banker, canceled the monthly transfer, and shut down the authorized-user card attached to the household account I funded for my mother.
No speech. No warning.
I put my phone facedown and let the nurse adjust my IV.
About ninety minutes later, someone started arguing at the nurses’ station.
A familiar voice.
My mother.
She appeared in my doorway wearing a camel coat, expensive sunglasses pushed onto her head, and the leather handbag I had bought her for Christmas.
For one hopeful second, I thought she had changed her mind.
Then I saw her face.
She wasn’t worried.
She was furious.
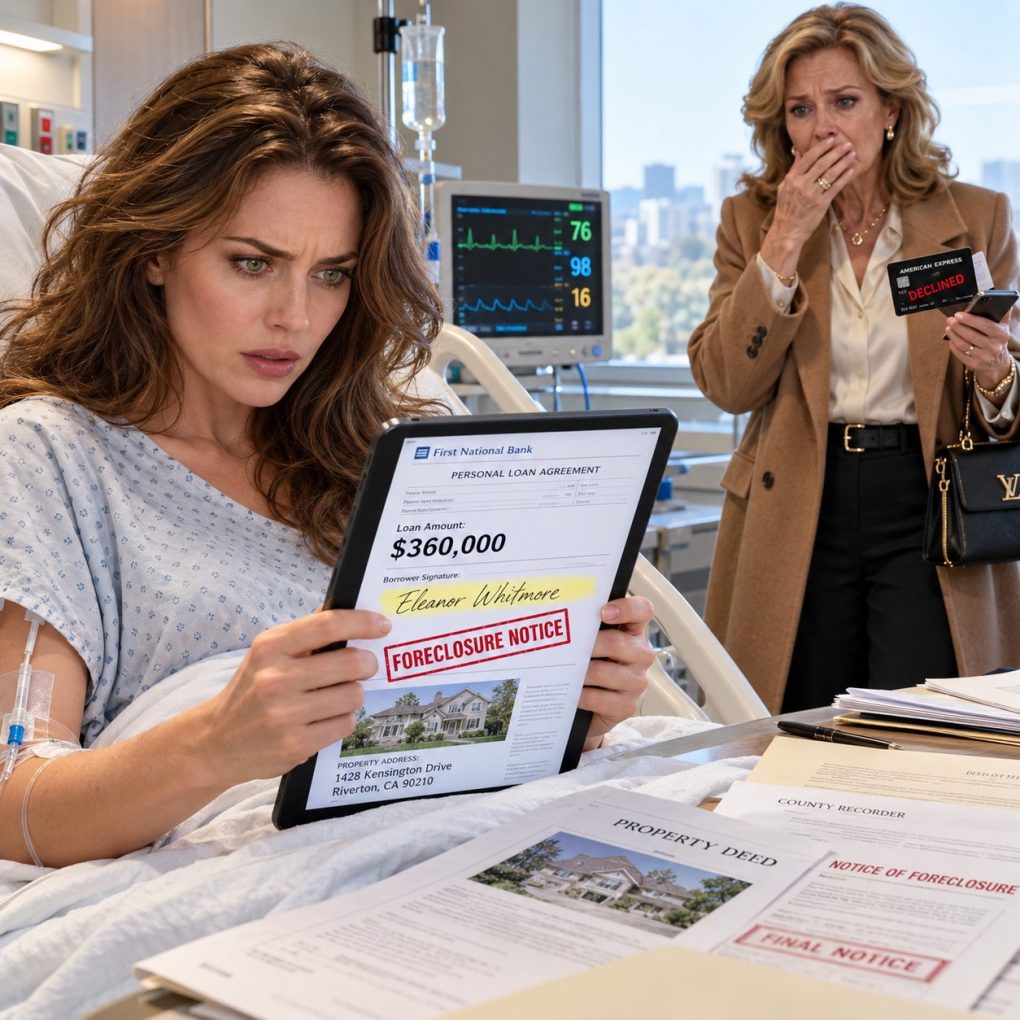
“What did you do?” she demanded.
“My card was declined. And the transfer is gone.”
I stared at her.
“Claire, turn it back on right now.”
“No.”
Her face drained of color.
Then she said something that made me sit upright despite the pain.
“If that payment doesn’t clear by five o’clock, they can start taking the house.”
My pulse jumped on the monitor.
“What house?”
Mom looked toward the hallway, then back at me.
“The one you bought me.”
For a few seconds, I thought the fever had made me misunderstand her. The house was paid for. There was no mortgage to miss, no lender to call, no reason anyone could “take” it. Unless my mother had done something I didn’t know about.
I stared at my mother until the monitor beside me started beeping faster.
“That house is paid off,” I said.
Mom’s eyes moved to the door. “Keep your voice down.”
That was when I knew this wasn’t confusion. It was a secret.
I reached for my phone.
She grabbed the edge of my blanket. “Claire, please. Just restore the transfer. We can discuss everything when you’re better.”
“No. We can discuss it now.”
For the first time since she arrived, she looked frightened rather than angry.
She admitted there was a loan.
Not in her name.
In mine.
Eighteen months earlier, she had borrowed $360,000 against the house I owned. She said the money had gone to my younger brother, Ryan, after his fitness studio began collapsing under equipment debt, payroll taxes, and a disastrous second location.
I actually laughed because the alternative was screaming.
“You can’t borrow against my house.”
Mom swallowed. “You signed the documents.”
“No, I didn’t.”
She said nothing.
I opened my email and called my attorney, Daniel Price. I told him I was in the hospital and asked him to pull the county records immediately.
Mom kept whispering that I was “making this worse.”
Twenty minutes later, Daniel called back.
There was a recorded deed of trust on my property for $360,000.
The borrower listed was me.
The lender was a regional private-credit company I had never heard of.
Daniel emailed me the filing.
My name appeared twelve times.
My signature appeared four times.
It looked almost perfect.
Almost.
Then I saw the date.
I had been in Seattle that entire week speaking at a compliance conference. I still had the hotel receipt and airline itinerary.
Mom sat down slowly.
I asked one question.
“Who signed my name?”
She started crying.
Not answering. Crying.
Then my phone rang again.
This time it was Daniel.
“Claire, there’s more. The loan is already in default.”
My stomach tightened.
Ryan’s business had stopped making payments three months earlier. The lender had sent notices to an email address containing my name, but it wasn’t mine. Someone had created it specifically for the loan.
The $8,000 I sent Mom each month had been covering part of the debt service while she tried to keep the default hidden.
That was the first major lie.
The second was worse.
Daniel had checked the notarization.
The woman who notarized my supposed signature was Carol Mercer.
My mother’s closest friend for twenty-seven years.
Mom covered her face.
I felt suddenly colder than I had when the doctor said sepsis.
Then Daniel said, “There’s a foreclosure notice attached to the file.”
I closed my eyes.
“How long do we have?”
He hesitated.
“The sale is scheduled for Friday morning.”
It was Wednesday.
Mom whispered, “That’s why I needed the money today.”
I looked at her.
Not once had she come because I was sick.
She had come because the fraud was about to collapse.
I thought I would feel rage.
Instead, I felt strangely calm. Maybe it was the antibiotics, or maybe betrayal can become so complete that your mind stops trying to excuse it.
I looked at my mother and said, “Give me your phone.”
She clutched it tighter.
“No.”
“Then leave.”
Her mouth fell open. A nurse stepped in and asked if I wanted security. Mom immediately called it a “family misunderstanding.”
“I want her to leave,” I said.
Security escorted her out.
The moment the door closed, I called Daniel again. He told me not to contact the lender myself and to preserve everything. He wanted my Seattle conference registration, hotel receipt, flight records, calendar entries, and every message I had exchanged with Mom and Ryan around the loan date.
Then he asked whether Mom had ever possessed copies of my identification.
Of course she had.
When I bought her house, she had copies of my driver’s license, tax information, insurance documents, and closing paperwork. I had left a folder with her because I trusted her.
By that evening, Daniel had sent fraud notices to the lender and the foreclosure law firm. The next morning, while I was still hospitalized, he prepared an emergency filing to stop the sale.
Then the lender’s fraud department found something worse.
Attached to the original application was an email chain.
The account pretending to be mine had been created less than two weeks before closing. Most messages came from Mom.
One came from Ryan.
“Mom says Claire is okay with us using the house. Just tell me where I need to sign.”
Three days later, he wrote, “Does she actually have to be on the call, or can Mom handle it?”
I read that twice.
Ryan had spent months telling me his business was “finally turning around.” He had even thanked me for always believing in him.
He never mentioned that my house was backing his debt.
The lender postponed the foreclosure while it investigated.
Then Carol Mercer, Mom’s friend who had notarized the documents, hired a lawyer.
Her attorney contacted Daniel two days later.
Carol admitted she had never watched me sign anything.
Mom had brought her papers already signed and said I was traveling, had approved everything, and that notarizing them was simply helping family avoid a scheduling problem.
Carol knew she should not do it.
She did it anyway.
That statement changed everything. This was no longer a vague family dispute over consent. There was direct evidence that the signature process had been fraudulent.
I was discharged Friday afternoon.
Mom was waiting in the parking lot.
She looked smaller than she had two days earlier.
“I was trying to save your brother,” she said.
“By stealing my identity?”
“He was going to lose everything.”
“So you decided I should lose something instead?”
She shook her head. “I thought I could fix it before you knew.”
That sentence explained more than any apology could.
My mother had not believed she had the right to do it.
She had believed she could get away with it.
I asked where the $360,000 had gone.
Most went into Ryan’s business: overdue rent, equipment financing, payroll taxes, vendors, and a settlement with a former partner.
But nearly $50,000 had gone into Mom’s personal account.
She had used some for travel, shopping, and credit-card balances.
And the $8,000 I sent her every month?
About $5,700 had been covering the loan after Ryan stopped paying.
The rest funded her lifestyle.
She had been using my monthly gift to make payments on a debt created by forging my name.
Mom reached for my arm.
“Please don’t report this. We can keep it inside the family.”
I stepped back.
“It stopped being a family matter when you put my name on legal documents.”
The next several months were ugly, but clear.
The lender’s investigation confirmed that I had never participated in the closing. My travel records placed me across the country. The email address was not mine. The notarization had not been properly performed. The loan proceeds had gone to Ryan’s company and Mom.
After negotiations, the lender released the lien against my house and preserved its claims against the people who had obtained the money.
The foreclosure was canceled.
I filed a police report.
Carol surrendered her notary commission and cooperated with investigators. Ryan closed the second fitness studio, sold equipment, and eventually shut down the original location. He blamed me for months.
He said I could have “handled it privately.”
I asked what private solution he had imagined for a $360,000 debt in my name.
He never answered.
I stopped the $8,000 payments permanently.
I canceled every card connected to me, changed my banking passwords, froze my credit, and removed Mom from every financial and estate-related role she had held.
Then, through Daniel, I gave her lawful notice that she would need to leave the house.
She called me cruel.
That word would have destroyed me a year earlier.
Now I understood that, to my mother, “cruel” meant I was no longer absorbing the consequences of her choices.
She moved in with Ryan for a while.
I sold the house six months later.
After taxes, legal expenses, and repairs, I invested most of the proceeds and used some for something I had neglected for years: my own life.
That summer, I took three weeks off and rented a small place on the Maine coast with Jenna.
One evening, Mom called.
She did not ask for money.
She said she had started working part-time at a furniture showroom and moved into a modest apartment. Ryan was making payments under a civil restitution agreement.
Then she said, “I know you probably don’t believe me, but I’m sorry.”
I looked out at the ocean.
“I believe you’re sorry things ended this way.”
She went quiet.
“But I don’t know yet if you’re sorry for what you did.”
For once, I did not rush to fill the silence.
We are not magically close now.
We speak occasionally. I keep distance. There are no shared accounts, no financial favors, and no emergencies that become my responsibility simply because someone says “family.”
The strangest part is that getting sick may have saved me from something worse.
If I had not called Mom from that hospital bed, I probably would have kept sending $8,000 every month.
If she had shown up because I was sick, I might never have canceled anything.
And if her card had not been declined, she might never have panicked and revealed the secret she had hidden for eighteen months.
I used to think generosity proved love.
Now I know generosity without boundaries can become permission.
My mother came to the hospital ninety minutes after telling me not to expect her help.
She came because she thought she was about to lose her house.
Instead, that afternoon she lost access to my money.
And I finally got my life back.