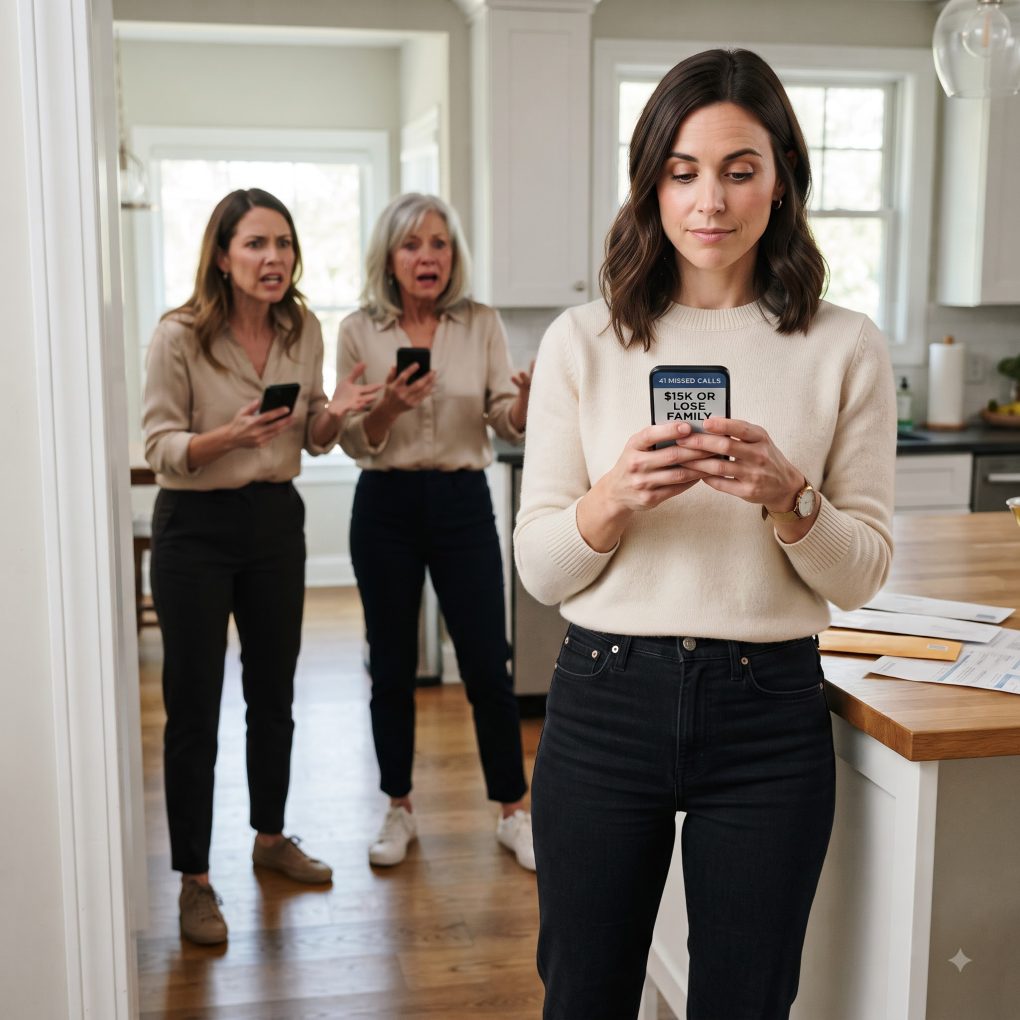
“They expected me to bail out my sister’s debt. When I refused, my mother issued an ultimatum: pay $15,000 or lose the family. I severed all financial ties, triggering a late-night storm of 41 frantic calls.”
“SO YOU’LL WATCH US STRUGGLE?” My sister, Megan, snapped over the phone.
“I’m not paying your $15,000 debt,” I said. “Not my emergency.”
Silence.
Then she laughed bitterly. “Fine. Remember that when Mom and Dad need help.”
I hung up.
Two hours later, my phone buzzed.
Mom: $15K. Pay it today or lose this family.
I stared at the message, convinced it had to be a joke.
It wasn’t.
Another text appeared.
Your sister made mistakes, but family fixes family problems.
Then Dad joined in.
If you walk away now, don’t call us again.
I had spent years being the “responsible” child. Whenever Megan overspent, I was expected to cover the difference. Whenever she missed a payment, Mom called me. I had finally stopped.
So I replied with three words:
I’m done paying.
Then I blocked them.
For the first time, my apartment was completely quiet.
Until my banking app sent me an alert.
NEW TRANSFER REQUEST: $15,000
My heart stopped.
Someone had tried to move money from my savings account.
I immediately called my bank.
The representative told me something that made my stomach drop.
“There’s an authorized user connected to this account.”
“I never added one.”
She paused.
“Ma’am… the authorization was created several years ago.”
I grabbed my laptop and checked my old financial records.
There it was.
A document I barely remembered signing when I was twenty-one.
My mother had told me it was “just paperwork” for an emergency savings account.
But the account wasn’t mine alone.
And someone had just tried to use that old authorization to take the exact amount Megan owed.
Then my phone lit up again.
A message came from an unknown number:
“You really should ask Mom why your name is on Megan’s loan.”
I froze.
Because I had never taken out a loan for Megan.
At least, I thought I hadn’t.
I thought refusing $15,000 was the end of the argument. I was wrong. What I found in my old financial records changed everything—and suddenly, the debt wasn’t the only thing my family had been hiding from me.
I called the unknown number.
No answer.
A minute later, a photo arrived.
It was a screenshot of a loan document.
My name was listed as a co-signer.
Megan’s name was beside mine.
The loan balance was exactly $15,000.
I stared at the screen.
“That’s impossible.”
I had never signed a $15,000 loan for Megan.
Then another message appeared.
Check the signature.
I zoomed in.
The signature looked like mine.
Not perfect—but close enough to make my hands shake.
I called the bank again and asked them to freeze every account connected to my information.
Then I contacted the lender listed on the document.
The representative confirmed the loan had been opened three years earlier.
“Who submitted the application?” I asked.
“We can’t disclose all details over the phone.”
“I’m the person supposedly responsible for this debt.”
There was a pause.
Then she said, “The application was submitted through a branch.”
“Which branch?”
She gave me the address.
My stomach tightened.
It was the same bank branch where my mother had taken me years earlier to “update some family paperwork.”
I drove there immediately.
The branch manager pulled up the archived file.
There were copies of my identification, the application, and the signature.
But there was something else.
A note attached to the file.
Parent present during signing.
I felt cold.
“Who was the parent?”
The manager looked at the screen.
“Linda Carter.”
My mother.
I left the bank and called her.
She answered immediately.
“You finally figured it out,” she said.
I couldn’t speak.
Then she continued.
“Megan needed the money. You had excellent credit. We knew you would help if you understood how serious things were.”
“You forged my signature.”
“We didn’t forge anything,” she snapped. “You signed paperwork that day.”
“I signed paperwork for an emergency savings account.”
“You signed several documents.”
My chest tightened.
“Mom, what exactly did you do?”
She went silent.
Then she said something I never expected.
“Your father and I didn’t use your identity to help Megan.”
“Then what?”
“We used it because we knew the bank wouldn’t approve her.”
That was the twist.
The $15,000 wasn’t Megan’s original debt.
It was the final balance of a much larger financial mess.
And my parents had been using my credit for years.
I demanded copies of everything.
Mom refused.
So I hired an attorney.
The next morning, my attorney called me after reviewing the first documents.
“You need to sit down.”
“What did you find?”
“The loan is only one problem.”
He sent me another file.
Inside was a list of accounts, payments, and transfers.
My parents had connected my name to three separate financial obligations.
And one of them had already gone into collections.
Before I could process it, my phone exploded with calls.
Mom.
Dad.
Megan.
Then an unfamiliar number.
My attorney answered it.
His expression changed.
He covered the phone and looked at me.
“This is Megan’s attorney.”
I whispered, “Why does she have an attorney?”
He listened for another few seconds.
Then he said:
“They’re claiming you voluntarily accepted responsibility for the entire debt.”
I felt my blood run cold.
But my attorney wasn’t worried.
He opened the original bank file again.
“There’s something they don’t know we found.”
He pointed to a timestamp.
A document had been uploaded after the supposed signing date.
And whoever uploaded it had made one fatal mistake.
Their name was attached to the digital record.
It wasn’t mine.
It was my mother’s.
My attorney, Daniel, leaned back in his chair.
“Before you do anything, don’t contact your family.”
I nodded.
“What happens now?”
“We document everything.”
For the first time since the phone calls began, someone sounded completely calm.
Daniel explained that the timestamp on the bank document could be important, but we needed the complete account history before making any accusations. He requested copies of the loan application, authorization forms, account records, and electronic access logs.
I went home and changed every password I had.
Banking.
Email.
Credit cards.
Cloud storage.
Even the password to my old tax account.
Then I placed fraud alerts with the credit bureaus and froze my credit.
That afternoon, Megan called from a different number.
I answered.
“Please stop,” she said.
“Stop what?”
“Making this bigger than it needs to be.”
I almost laughed.
“You tried to take $15,000 from my savings.”
“I never touched your savings.”
“You were the reason they tried.”
Silence.
Then Megan whispered, “You don’t understand what happened.”
“Then explain it.”
She took a breath.
“I borrowed money because Mom said you were going to help me.”
“I never agreed.”
“She said you knew.”
“I didn’t.”
Another silence.
Then Megan said something that changed the entire situation.
“Mom told me you had already signed everything.”
I closed my eyes.
“How much did you borrow?”
“Originally?”
“Yes.”
“Thirty-eight thousand.”
My stomach dropped.
“And you still owe fifteen?”
“Yes.”
“So where did the other $23,000 go?”
Megan started crying.
“I paid bills. I paid off credit cards. I covered rent. Mom also took some of it.”
“What?”
“She said she was helping me.”
That was the first crack in the story.
For years, my parents had told me Megan was irresponsible and needed rescuing. But now it appeared some of the money had never been used for Megan at all.
I asked Megan one final question.
“Did you know my name was on the loan?”
She hesitated.
“Yes.”
My heart sank.
“How long?”
“Since the beginning.”
I ended the call.
I wanted to be furious with her.
I was.
But I also realized something important.
Megan had been part of the deception, but she hadn’t created it alone.
Daniel confirmed that after obtaining the records.
The lender’s electronic audit trail showed that the original application had been created from a branch terminal assigned to my mother.
More importantly, the final authorization document had been uploaded several days after my supposed appointment.
My signature had been copied onto it.
The bank’s security department opened an investigation.
Then came another discovery.
The account my mother had called an “emergency savings account” when I was twenty-one had actually been connected to a joint family financial profile.
My mother had been authorized to communicate with the bank.
That explained how she had obtained old information.
It did not give her permission to use my identity.
Daniel sent a formal dispute to the lender.
I also filed a police report.
The moment I did, my mother stopped calling.
Dad didn’t.
He left three voicemails.
The first said I was destroying the family.
The second said Megan could lose her apartment.
The third was different.
“You don’t know what your mother has done.”
I played it twice.
Then I called Dad.
“What does that mean?”
He was quiet.
Finally, he said, “Your mother borrowed against something she shouldn’t have.”
“What?”
“Our house.”
I froze.
He explained that several months earlier, Mom had taken out another loan secured against their home.
She had used the money to pay overdue bills, cover Megan’s expenses, and keep several accounts from going into default.
Dad claimed he hadn’t known the full extent of it until recently.
But there was more.
Some of those payments had been made through accounts containing my information.
Daniel immediately requested those records.
The next week, the bank sent them.
The documents showed transfers between my parents’ accounts and Megan’s accounts.
There were also transfers into an account I didn’t recognize.
The account belonged to a small business.
Megan’s business.
She had told everyone she was barely surviving.
But she had been running an online boutique and had been using family money to keep it operating.
The business wasn’t secretly worth a fortune.
It wasn’t some dramatic millionaire scheme.
It was simply losing money.
And instead of shutting it down, Megan and my mother kept borrowing to keep it alive.
My name had become the safety net.
That explained the $15,000.
But it didn’t explain the message demanding that I pay immediately.
Daniel did.
“The debt is nearing default,” he said. “Your mother knew that if you paid it voluntarily, you might accept responsibility for it.”
I stared at him.
“So the $15,000 demand was a trap?”
“It appears they wanted you to make the payment yourself.”
That was the part that hurt most.
They weren’t simply asking for help.
They were trying to make me acknowledge a debt I hadn’t legally agreed to.
I refused.
The lender eventually removed my name from the disputed obligation after reviewing the evidence and completed its investigation.
The other accounts connected to my identity were also reviewed.
One was closed.
Another was transferred back to the person who had actually opened it.
The third was still under investigation, but my attorney made sure I wasn’t held responsible while the dispute continued.
Then came the hardest conversation.
I met my parents at a lawyer’s office.
Megan came too.
Nobody spoke for several seconds.
My mother looked exhausted.
Dad wouldn’t look at me.
Finally, Mom said, “I thought I was protecting my daughter.”
“You were protecting Megan,” I said.
She began crying.
“I was afraid she’d lose everything.”
“And you were willing to risk everything I had.”
She didn’t answer.
Megan finally spoke.
“I should have told you.”
“Yes,” I said.
“I was scared.”
“You were scared of losing your business. I was scared of losing my identity.”
She looked down.
For once, nobody had an excuse.
I told them exactly what would happen next.
I would not pay Megan’s debt.
I would not sign another document.
I would not lend money.
I would not provide access to my accounts.
And I would not allow anyone to use the word “family” as a weapon against me again.
Dad asked, “So that’s it?”
I looked at him.
“No. That’s the boundary.”
Megan eventually closed her business.
She sold inventory, negotiated payment plans with legitimate creditors, and moved into a cheaper apartment.
It wasn’t glamorous.
It wasn’t easy.
But it was hers.
My parents sold their house months later and downsized after dealing with their own financial obligations.
Our family relationship didn’t magically return to normal.
For a while, there were no calls at all.
Then, six months later, I received a text from Megan.
I know saying sorry doesn’t fix it. But I’m sorry.
I stared at the message for a long time.
I didn’t immediately forgive her.
But I replied.
Thank you for finally telling the truth.
That was all.
A year later, I still had the original message from Mom saved:
$15K OR LOSE FAMILY.
At the time, I thought those words were a threat.
Eventually, I understood them differently.
Losing financial access to me didn’t destroy our family.
It exposed what our family had become.
I hadn’t walked away because I didn’t care.
I walked away because caring about someone doesn’t mean giving them unlimited access to your money, your credit, or your future.
And the most important lesson wasn’t about the $15,000.
It was about the sentence I should have said years earlier:
“That isn’t my emergency.”