For seven months, I quietly bought Mom’s groceries every Saturday and covered whichever bill was about to fail. Sometimes it was electricity. Sometimes insurance. Once it was the property tax installment on the small Indianapolis house she had owned for thirty-four years. Mom kept blaming inflation for why her retirement money suddenly disappeared so quickly.
I knew something else was wrong. Mom received Social Security, Dad’s small survivor pension, and income from a certificate of deposit. She wasn’t wealthy, but her basic expenses hadn’t changed enough to explain why she was repeatedly short by $600 or $900.
My older brother, Scott, handled her online banking. After Dad died, Mom gave him legitimate access because she hated computers. Scott owned a struggling flooring company and constantly complained about customers paying late, but I never connected his problems to hers until Mom’s homeowners insurance payment bounced.
With Mom sitting beside me, I logged into her account to find out why. The balance was only $412. Then I noticed repeated transfers to an account labeled SBR Holdings. I recognized the initials immediately: Scott Bradley Renovations.
I printed six months of statements. There were eleven transfers totaling $18,700. Some were labeled reimbursement. Others simply said transfer. Mom stared at the pages and shook her head. “Scott said he moved money around to earn better interest.”
I called him and asked him to come over. When I placed the statements on Mom’s dining table, Scott barely looked at them. He said I didn’t understand business banking and accused me of frightening Mom over ordinary financial management.
“Then show us where the money is,” I said.
His face hardened. Instead of answering, he turned toward Mom. “Do you know why Claire keeps paying your bills? She wants you to think you can’t manage without her. Then she’ll convince you to put the house in her name.”
I couldn’t believe how quickly Mom’s expression changed. Scott had found exactly the fear that would work. Mom had spent years terrified that aging meant losing control of her home.
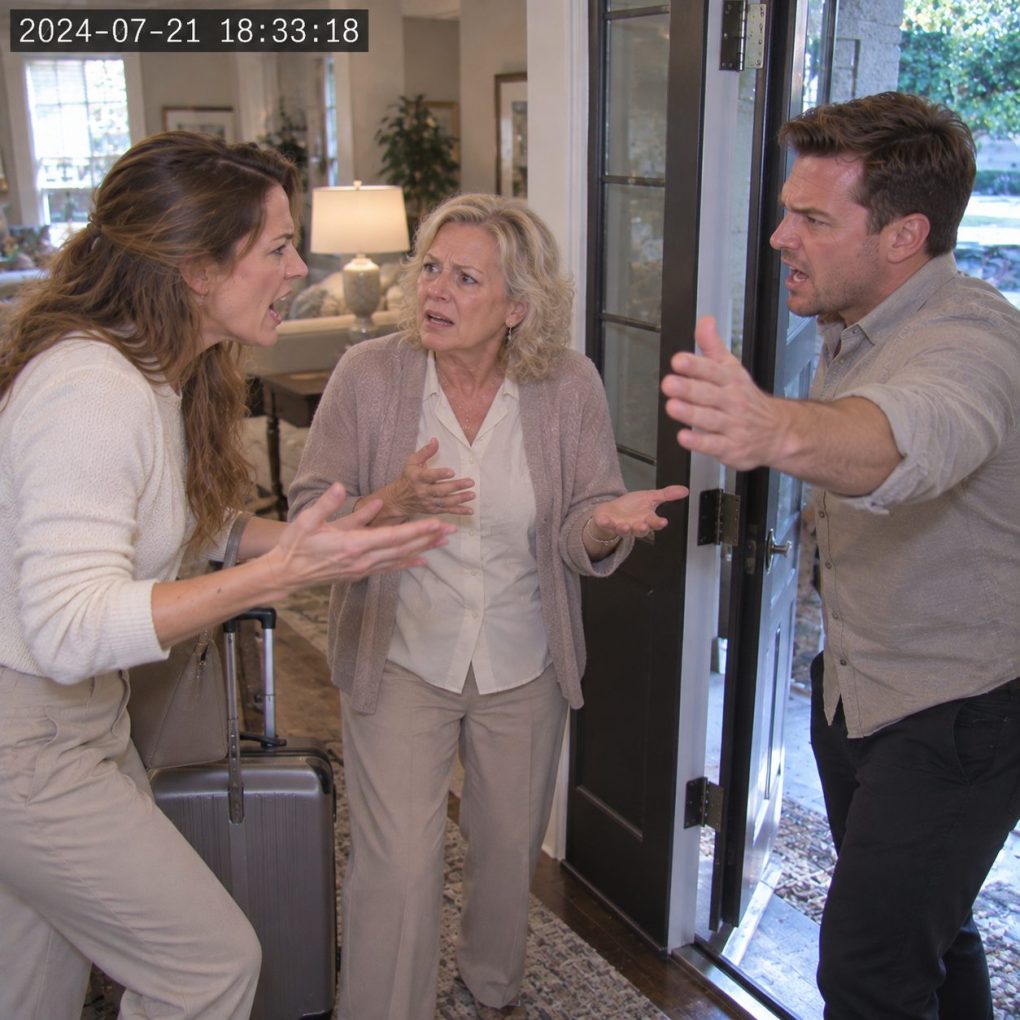
I tried to explain, but Scott kept talking over me. Finally, Mom pushed the statements away. “Claire, I think you should leave.” I stared at her. Scott walked to the front door and opened it like the house belonged to him.
I gathered my purse and the duplicate statements. Before leaving, I said, “Mom, I haven’t taken one dollar from you. Please call the bank yourself.” Scott slammed the door behind me. Three weeks later, Mom called crying. Two official envelopes had arrived—and one was addressed to Scott’s company at her house.
The first envelope came from a commercial lender. The second was from an attorney representing a supplier Scott’s company had failed to pay. Mom didn’t understand why either organization had her home address, so she finally called the bank without telling Scott.
A bank employee reviewed the account and asked whether Mom had authorized the transfers to SBR Holdings. Mom said she had believed Scott was moving money between accounts for her benefit. She had never knowingly agreed to fund his company.
The bank couldn’t simply promise to restore everything. It opened a review and advised Mom to secure her online access immediately. She changed her password, replaced access credentials, and removed permissions after receiving appropriate guidance.
Then Mom called me.
I found her sitting at the same dining table where she had thrown me out. The statements were spread everywhere. “I’m sorry,” she whispered. “I believed him because believing you meant admitting my own son was taking advantage of me.”
I sat beside her. This wasn’t the moment to collect an apology. We needed to understand what Scott had done and what risks remained.
Mom contacted an attorney who worked with older clients on financial and estate matters. She brought every statement, message, and document she could find. I brought receipts showing the groceries and household bills I had paid from my own account.
Those receipts mattered emotionally more than legally to Mom. She kept touching them as though she needed proof that I hadn’t secretly been reimbursing myself.
Scott’s situation unraveled quickly after his access disappeared. His company had been surviving from one overdue obligation to another. He had transferred Mom’s money whenever payroll, equipment payments, or suppliers threatened immediate consequences.
When confronted through proper channels, Scott initially claimed the money was a family loan. Mom asked for the loan agreement. There wasn’t one. She asked for messages where she had agreed to lend him $18,700. There weren’t any.
Then another problem surfaced. Scott had used Mom’s address on several business documents because his commercial lease had ended months earlier. That explained the envelopes and why creditors were suddenly contacting her home.
Mom’s attorney helped her respond correctly and separate her property from Scott’s business affairs. The house itself had not been transferred or pledged, which was the news we had been most afraid to hear.
Scott called Mom repeatedly. She didn’t answer until her attorney advised her how to handle communication. When she finally spoke to him, she asked only one question.
“If it was really a loan,” she said, “why did you have to lie about where my money went?”
Scott had no answer.
The bank’s review took time. Some transactions were complicated because Scott had originally been given legitimate access to help Mom manage her finances. The dispute wasn’t as simple as a stranger stealing a debit card.
Mom’s attorney explained that permission to help manage an account did not automatically mean permission to use the money for personal business expenses. What could be recovered, and through which process, depended on the documents, authorizations, and evidence.
Scott eventually admitted he had used the money to keep his company alive. He said he always intended to repay Mom after two large contracts were completed. One customer had canceled, another delayed payment, and his temporary borrowing became a pattern.
His business closed before Christmas.
Equipment was sold, creditors negotiated over what remained, and Scott moved into a small apartment. Through a formal agreement reached with professional advice, he began repaying Mom in monthly installments.
Mom never celebrated his failure. Neither did I. Watching your child lose a business is painful even when his own choices helped cause it. But she stopped confusing protecting Scott from consequences with loving him.
She also changed how she handled money. Her bills were placed on automatic payment from an account she could monitor easily. Her attorney updated important documents, and Mom chose safeguards that didn’t give either child unchecked financial control.
I stopped secretly paying her expenses too. Instead, we created a monthly budget together. If she needed help, she asked. If I wanted to give her something, we both knew exactly what it was.
Scott didn’t speak to me for almost six months. When he finally did, he still resented that I had printed the statements. I reminded him Mom had been sitting beside me and had asked me to help understand why her insurance payment failed.
He looked exhausted. “I thought I could replace everything before anyone noticed.”
“That’s why you kept doing it,” I said.
He nodded.
Mom and Scott slowly rebuilt some relationship, but she never restored his banking access. When he visited, they talked about ordinary things: football, neighbors, repairs, Dad’s old tools. Money remained outside their relationship.
One Saturday, nearly a year after everything happened, I brought Mom groceries. At the register, she pushed my card away and used her own.
“You don’t have to prove anything,” I told her.
She smiled. “I know. I just like knowing I can pay for my own cereal again.”
That sentence stayed with me. The worst thing Scott took wasn’t $18,700. For months, he took away Mom’s confidence in her own financial reality. Getting the money under control mattered. Getting that confidence back mattered more.