My father refused to spend a single penny on food, and for almost a year I believed it was because we were broke. Then, on the night my fourteen-year-old brother collapsed beside the refrigerator, I found a bank receipt showing that Dad had more than four hundred thousand dollars sitting in an account none of us knew existed.
I had moved back into our house outside Pittsburgh three months earlier after losing my apartment, and from the first day, Dad treated groceries like an enemy. He brought home dented cans from church donation boxes, stale bread from a bakery dumpster, and expired frozen meals that coworkers were throwing away, while insisting that my brother Noah and I were “spoiled” whenever we asked for fresh milk, fruit, or meat.
“We have food,” he always said.
Most nights, “food” meant canned beans, crackers, and whatever Noah could get free at school.
Dad earned nearly ninety thousand dollars a year as an electrical supervisor.
Whenever I asked where his paycheck went, he answered the same way.
“Bills.”
That Friday evening, Noah opened the refrigerator, stared at a jar of mustard and half a carton of eggs, then quietly said, “I’m dizzy.”
He hit the kitchen floor before I could reach him.
I called 911.
While the paramedics checked him, one asked what Noah had eaten that day.
“A school lunch,” I said.
The paramedic looked at the clock.
It was almost nine at night.
Dad arrived home while they were preparing to take Noah to the hospital, carrying a box of bruised apples someone from work had given him. Instead of asking whether Noah was okay, he looked at me and demanded, “Who called an ambulance?”
“I did.”
“You know what that costs?”
I stared at him.
“Your son just passed out.”
“He skipped dinner. Kids pass out.”
Something inside me snapped.
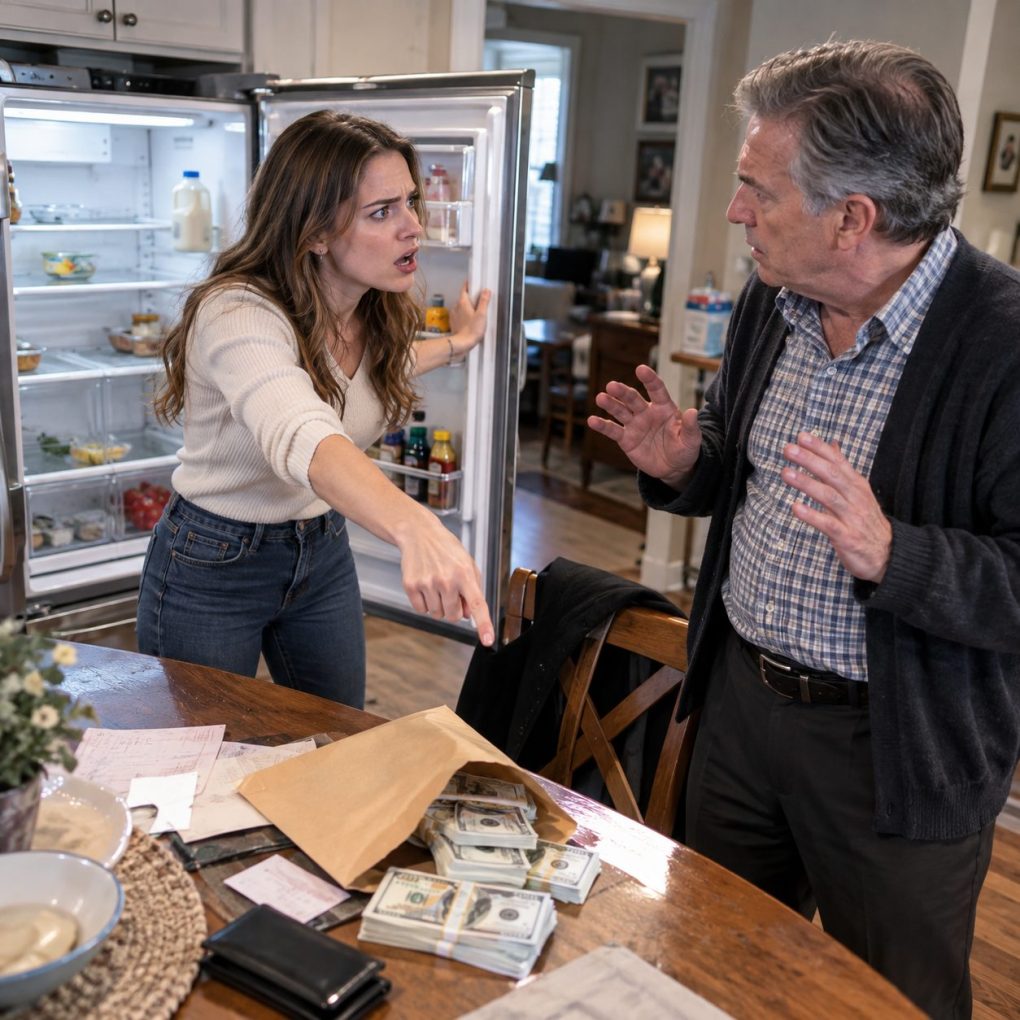
I followed him into the kitchen while he complained about medical bills, and that was when I saw a crumpled ATM receipt on top of the trash.
I unfolded it.
AVAILABLE BALANCE: $417,382.16
For several seconds, I genuinely thought I was reading somebody else’s account.
Then I saw the last four digits.
They matched Dad’s debit card.
“You said we didn’t have money.”
He stopped moving.
Behind me, the paramedics rolled Noah toward the front door.
Dad looked at the receipt in my hand and became completely still.
“That money isn’t for groceries.”
I almost laughed.
“Then what the hell is it for?”
His face changed.
Not embarrassment.
Fear.
“Rachel,” he said quietly, “put that back.”
That was the moment I understood something much worse than poverty was happening in our house.
And my mother, who had been dead for three years, was somehow connected to it.
Part 2 — Mom’s Missing Money
Word Count: ~575
Noah was treated for dehydration, low blood sugar, and nutritional deficiencies that the emergency physician said had likely developed gradually rather than in a single day. The doctor was careful not to accuse anyone, but when she asked how regularly Noah had access to balanced meals, I could not answer without sounding like I was describing a household from the Great Depression instead of a suburban home with two working vehicles and a father earning a middle-class salary.
Dad barely spoke during the drive home.
The next morning, I placed the ATM receipt on the kitchen table between us.
“You have four hundred thousand dollars.”
“It isn’t mine.”
“Your name is on the account.”
“That doesn’t make it spending money.”
“Then explain it.”
Dad stared at his coffee.
“No.”
That one word made me start looking.
Mom had died from ovarian cancer when Noah was eleven and I was twenty-two. During her final year, she worried constantly about leaving Noah behind, and I remembered her telling me more than once that she had “made arrangements” so Dad would never have to choose between medical bills, the mortgage, and taking care of us.
At the time, I assumed she meant life insurance.
I called my aunt Linda, Mom’s older sister.
There was a long silence after I mentioned the account.
“Rachel,” she finally said, “your mother had a life-insurance policy.”
“How much?”
“Half a million.”
My hand tightened around the phone.
Dad had never told me.
Linda explained that Mom’s policy had been structured differently from what I expected. Dad was the primary recipient, but Mom had also left written instructions through an attorney asking that a large portion be preserved for Noah’s living expenses, education, health care, and general support until he turned eighteen.
The instructions were not a formal trust, which meant Dad technically controlled the money.
But there had been another account.
Mom had also inherited almost $160,000 from my grandmother shortly before her diagnosis, and according to Linda, she had intended that money specifically for Noah and me.
“Your mother made me witness paperwork,” Linda said.
“What paperwork?”
“A beneficiary agreement with her financial adviser.”
My stomach tightened.
Dad claimed that account no longer existed.
The financial adviser disagreed.
After I contacted him and provided the necessary documentation, he confirmed that the investment account had been liquidated eleven months after Mom died. The proceeds had been transferred into an account controlled by Dad.
That was the same period when Dad stopped buying groceries.
I confronted him that night.
At first, he denied everything.
Then I showed him the transfer statement.
His shoulders dropped.
“You don’t understand what your mother did.”
“What did she do?”
“She made me promise.”
I waited.
Dad opened a drawer and pulled out a folded letter.
Mom’s handwriting covered four pages.
The letter was emotional but clear: she wanted Dad to preserve as much money as possible for Noah’s future because she feared Dad’s impulsive spending. She mentioned college, health emergencies, housing, and the possibility that Noah might need counseling after her death.
She never said to starve him.
I looked at Dad.
“You interpreted this as never spending money?”
“She wanted me to protect it.”
“She wanted you to protect Noah.”
“You think I don’t know that?”
For the first time, he raised his voice.
Then he told me the part none of us knew.
During Mom’s illness, Dad had secretly accumulated almost $120,000 in gambling debt.
Mom discovered it before she died.
Her final months were filled with arguments about money, and she made him promise that after she was gone, he would never touch the funds meant for the children unless absolutely necessary.
Dad took that promise and turned it into an obsession.
He paid his gambling debt with his salary over several years, but he refused to spend any of Mom’s money—even when Noah needed clothes, school supplies, dental work, or food.
“I was protecting what she left him,” Dad whispered.
I stared at him.
“No. You were protecting yourself from feeling guilty.”
He looked away.
Then I noticed something else in Mom’s letter.
A name.
Attorney Susan Bell.
Underneath it, Mom had written:
If anything happens to me and you start making decisions out of fear again, Susan has the originals.
Dad saw me reading.
His face went white.
“Rachel, don’t call her.”
I already had my phone in my hand.
Part 3 — What Mom Actually Asked Him to Protect
Word Count: ~600
Susan Bell still practiced family and estate law in downtown Pittsburgh, and two days later, I sat across from her with Linda while Dad refused to come. Susan remembered Mom immediately and pulled a thick folder from storage that contained copies of beneficiary forms, financial statements, letters, and something Dad had apparently hoped none of us would ever discover.
Mom had created a custodial account for Noah.
It contained $94,000.
Dad was listed as custodian until Noah turned eighteen, but the money was legally supposed to be used for Noah’s benefit when necessary and managed according to strict fiduciary standards. Dad had not stolen the account, but he had transferred part of its holdings into another institution without properly updating records, mixing funds in a way Susan described as “seriously problematic.”
The $417,000 I saw on the ATM receipt was not all Noah’s money.
Roughly $280,000 came from Mom’s life insurance, about $90,000 traced back to Noah’s custodial funds, and the remainder came from Dad’s own savings.
Susan asked the obvious question.
“If Noah needed food, medical care, or basic necessities, why was none of this being used?”
Dad finally agreed to meet with her.
His answer was painfully simple.
Because spending any of Mom’s money made him feel like he had failed her.
Every dollar that left the account reminded him of the gambling, the lies, and the arguments during her final months, so he had created a rule that required no judgment at all.
Never spend it.
He collected discarded groceries, relied on food pantries, cancelled Noah’s dental appointments, refused school-trip fees, and forced the entire household to live as if we were destitute because watching the account balance remain untouched made him feel as though he was finally keeping one promise.
Susan did not sympathize.
“Your wife did not ask you to preserve a number on a screen,” she told him. “She asked you to take care of her child.”
Dad started crying.
It was the first time I had seen him cry since Mom’s funeral.
What happened next was not dramatic enough for television, but it changed our family.
Susan helped petition the court for a new custodian over Noah’s funds, and Dad agreed rather than fight it. Linda was eventually approved to supervise the account alongside professional financial management, which meant Dad could no longer make unilateral decisions about money intended for Noah.
Noah also started seeing a therapist.
His doctor connected us with a nutritionist, and within several months his blood work improved, he gained healthy weight, and he stopped hiding granola bars in his backpack “just in case.”
That detail nearly destroyed me.
Dad moved temporarily into a small apartment after I told him I would not keep living with him unless he got help for his gambling history and his obsessive behavior around money. He joined a recovery group and began therapy, not because anyone promised him forgiveness, but because his relationship with Noah had reached the point where his own son became anxious whenever he heard Dad complain about grocery prices.
Six months later, Dad asked Noah if he could take him to dinner.
Noah looked at me first.
I told him the decision was his.
He agreed.
They went to a small burger place near Noah’s school.
When they returned, Dad handed me the receipt.
Two burgers.
Two fries.
Two milkshakes.
$38.74.
I looked at him.
“Why are you showing me this?”
His eyes filled.
“Because I paid for it.”
For anybody else, that sentence would have sounded ridiculous.
For my father, it meant everything.
Dad never became generous overnight, and our family did not magically return to normal. Trust came back slowly, through grocery receipts, therapy appointments, school fees paid without arguments, and the simple fact that Noah no longer had to wonder whether there would be dinner.
A year later, on Mom’s birthday, Dad invited us over.
The kitchen counter was covered with food.
Fresh chicken, vegetables, bread, strawberries, and a chocolate cake from the bakery Mom used to love.
No donated cans.
No expired packages.
No bruised fruit rescued from somebody else’s trash.
Before we ate, Dad placed Mom’s original letter on the table.
“I read this wrong for three years,” he said.
I shook my head.
“No. You read the words correctly.”
He looked at me.
“You just forgot what they meant.”
Mom had told him to protect Noah’s future.
Dad thought that meant protecting the money.
What he finally understood was that a child’s future is not something you save for while neglecting his present.
Sometimes protecting your family means spending the money.
Sometimes it means admitting that the thing you called discipline was actually fear.
And sometimes recovery begins with something as ordinary as paying for dinner.