Part 1
“We don’t run a nursing home.”
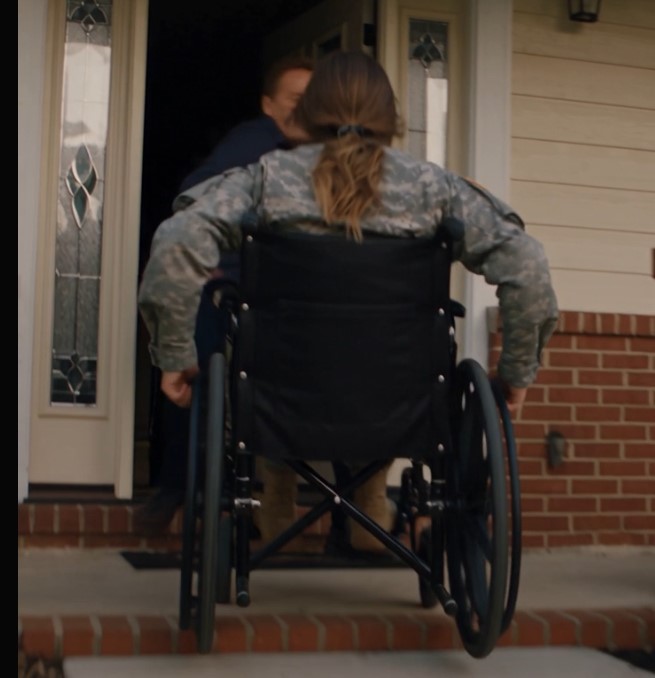
My father stood in the doorway, looking down at my wheelchair.
“Go to the VA.”
Behind him, my sister held a shoebox against her chest.
“I need your room,” Brooke said. “My collection’s outgrown the closet.”
I had been home from overseas for seven weeks.
Six of them were spent in hospitals and rehabilitation.
Before discharge, Dad told me the house was ready.
He said my room had been cleared, the downstairs bathroom checked, and someone would be there to help.
Now the transportation van idled behind me while he blocked the door.
“I’m not asking you to be my nurse,” I said.
“Then don’t make your problems ours.”
I looked past him.
My old bedroom door was open.
Shelves covered the wall where my bed used to be.
Then Noah appeared.
My little brother was twelve.
He ran outside holding a blanket, crying so hard he could barely speak.
“You can stay with me.”
He draped it across my knees.
It was the blue blanket Mom used to keep on the couch.
She had been gone four years.
I folded one corner over my hand because it still felt like something she would have done.
“Thank you, buddy.”
Dad told him to come inside.
Noah stayed beside me.
The driver stepped out of the van.
“Do we need another destination?”
“Yes,” I said.
My father smiled as though I had finally become reasonable.
He didn’t know I had already arranged a backup place near my rehabilitation appointments.
He also didn’t know who held his mortgage.
Before my last deployment, I used a military bonus and years of savings to purchase the remaining loan through a small company my attorney helped establish.
I hadn’t bought the house.
I had bought the debt secured by it.
A professional servicer handled the account.
Dad received the required notices under the company’s name.
He never asked who owned it.
For years, he had complained that the bank was destroying him.
I thought keeping the loan under patient, lawful management might give him room to recover.
I had also sent him money explicitly for mortgage payments while I was away.
The recent account reports showed arrears.
I planned to ask about them after I settled in.
Now there would be a different conversation.
Dad’s phone rang before the driver could help me leave.
He checked the number.
“The bank,” he muttered.
It was the loan servicing department returning a call about his request for another extension.
He put it on speaker.
“My son finally came home,” he said. “He’ll be taking over the payments.”
The representative paused.
“Mr. Mercer, we need to verify that arrangement with the loan owner.”
“I know. Cedar Ridge.”
“Cedar Ridge’s authorized representative is Daniel Mercer.”
Dad looked at me.
The porch went silent.
Then Noah leaned close.
“Daniel,” he whispered, “Dad said the bank took the money you sent. But I saw what they bought.”
I had come home expecting to discuss missed payments. Now my father knew whom he owed, and my little brother knew why the money was missing. The house wasn’t mine to take—but the lies holding this family together were about to become records someone could check.
The rest of the story is below 👇
Part 2
I asked Dad to end the call and speak with the servicer privately later. Noah did not need a financial argument on the porch. I told him where I would be staying and promised to call that evening. The driver helped me return to the van. Brooke stood beside the doorway, gripping her box. Dad said I should have told him about the loan. I answered, “You should have told me not to come.”
At the accessible apartment I had arranged as a backup, a friend from my unit met me with groceries. The discharge team knew the alternative address, and I contacted them to confirm the change. My follow-up care and practical support still needed coordinating. I did not have to become instantly independent to prove Dad wrong. I needed a reliable plan, including help I could ask for without being humiliated.
My attorney, Rebecca Sloan, reviewed the loan status with the servicer. The assignment was documented. Notices had been issued, and the borrower’s terms remained in place. Owning the note did not let me throw Dad out or claim his house. It gave my company the creditor’s rights under the documents and applicable law. Any enforcement would require proper procedures. I had bought it hoping not to use those rights.
The transfers from me were separate. My messages identified the money as funds for mortgage payments. Dad repeatedly confirmed he had paid. The servicing records contradicted him. We requested an accounting instead of declaring every missing dollar stolen. Some spending might have legitimate explanations. But the amounts overdue could not be explained by the bank deducting mysterious charges, as he had told Noah.
Brooke called that afternoon. “You can’t foreclose because we hurt your feelings.” “The loan is already delinquent,” I said. “And I haven’t made that decision.” She said she would tell everyone I was taking the family home. I told her to provide the actual documents if she wanted to discuss it. Then I ended the call. The pressure felt familiar: turn a clear question into proof that I didn’t love them.
Noah called while Dad was outside. I stopped him before he began describing receipts. “You’re not responsible for investigating anything. Don’t go through their things.” He became quiet. “I just wanted you to know I didn’t spend it.” I closed my eyes. Somewhere in the house, they had been talking as though all of us were responsible for a shortage we hadn’t created. I told him firmly that none of this was his debt or his fault.
Then Dad emailed Rebecca a proposed repayment plan. It included copies of statements he said proved where my contributions went. The records showed payments to Brooke’s credit cards and a luxury retailer. One receipt matched the shoebox she held at the door. More disturbing was an attached message Dad apparently forgot to remove. He had written to Brooke: Keep Daniel out until he agrees to forgive the loan. If he stays here, we lose our leverage. The room full of shoes wasn’t just selfishness. My welcome home had been made into a bargaining tool.
Would you have confronted your father with the message, or let your attorney handle the repayment dispute? Reply CONFRONT or ATTORNEY.
Part 3
I asked Rebecca to handle it.
Then I called Noah at the time I had promised.
We talked about school, a model airplane he was building, and whether the blue blanket was warm enough.
“It is,” I told him.
He sounded relieved.
For once, I wanted our conversation to leave him with something other than another adult problem to carry.
The following week was difficult in ordinary ways. Getting into the shower required planning. Moving groceries meant asking my friend to put them where I could reach. Rehabilitation appointments left me tired. My medical team helped address those needs, and I followed the plan we adjusted together. I was angry about the porch. I was also grateful that my backup arrangements meant the anger did not have to decide where I slept.
Rebecca clarified the loan history with me. The purchase had been a real transaction through the entity we established, with the relevant assignment and servicing arrangements. The amount was within what my bonus and accumulated savings could cover. Dad had not received a new loan from me that changed his obligations whenever he felt entitled to help. The original terms remained, along with any documented extensions. I could offer additional concessions, but I did not owe him forgiveness because I was his son.
That distinction was painful. I had bought the note partly as an investment and partly to give the family stability. I expected a modest return over time, professional servicing, and more flexibility than Dad believed he could obtain elsewhere. I had not intended to become a secret test of anyone’s character. His notices named the entity, as required, and I kept my involvement private because every direct financial arrangement in our family became an emotional contest. Eventually, that choice had produced its own complications.
The mortgage contributions were easier to understand. I had sent designated funds. Dad had accepted them and said the payments were made. He used a substantial portion elsewhere. Some covered household expenses. Some went toward Brooke’s debts and purchases. The statements helped establish the amounts, but they did not turn every expensive item into evidence. Rebecca traced transfers, dates, and the communications attached to them. We addressed what could be shown rather than the version that made me most furious.
Brooke had been working intermittently and spending beyond her income. Dad helped because he believed protecting her from consequences was the same as loving her. He expected me to keep sending money because I had always been steady. My injury changed the calculation. He began imagining I would need housing and care badly enough to forgive the loan in exchange. The message to Brooke stated the plan more clearly than either of them did when speaking to me.
The shoes became the insult everyone remembered. They were not the main issue. Brooke could own whatever she could afford. Dad could spend his money supporting her if he chose. They could not honestly tell me that designated mortgage funds had been paid while diverting them, then use my disability to demand release of the debt. Once I focused on that, the dispute became less about deserving a room and more about who would be responsible for promises already made.
Dad requested a meeting. It took place at Rebecca’s office, which had an accessible entrance and space around the table. Brooke came with him. He began by saying nobody understood how hard it was to see me in a wheelchair. I believed it had been hard. It had been harder for me to hear him call the place I grew up a nursing home. I told him his feelings did not explain why he lied to the discharge planner and me about my welcome.
“I thought you’d insist on staying,” he said. “I needed you to agree first.” I asked whether “agree” meant forgive the mortgage. He looked toward Brooke. She said everyone had misunderstood the message. Rebecca read it aloud once and asked them to explain their proposed accounting. There was no shouting. Dad admitted he wanted the debt canceled. He also admitted the transfers from me had not all gone where he said they went.
I did not forgive the entire loan. I did not call the servicer and demand immediate foreclosure either. We evaluated options within the loan documents and applicable procedures. Dad still had equity in the house. Selling voluntarily could satisfy the debt and leave funds for more suitable housing. Refinancing might have been another possibility if he qualified. Continuing to promise money he could not reliably pay would only repeat the problem.
He resisted selling because the house was the last place Mom had lived. That hurt to hear, even after everything. I remembered her garden, the pencil marks recording Noah’s height, and the kitchen chair where she used to leave folded laundry. I had not bought the note because those memories meant nothing. But keeping a building could not be the only definition of preserving a family, especially when it had become a place where one child was told he did not belong.
Noah’s welfare required care separate from the mortgage dispute. I had no automatic authority to decide where my minor brother lived. I stayed in contact, spoke with appropriate professionals when concerns warranted it, and made clear he was not to be used as a messenger. We arranged visits with Dad’s permission and practical support. If I had learned he was unsafe, I would have acted through the proper channels. What I knew then was that he was frightened and being exposed to arguments he should not have had to manage.
Dad eventually agreed to list the house. The sale took several months. During that time, the servicer and counsel documented interim arrangements rather than relying on another family handshake. The mortgage was paid through the closing process, and the remaining proceeds were distributed according to the actual obligations and title. I received what the note entitled my company to receive. I did not receive the entire value of the house as compensation for being rejected.
The disputed contributions were resolved separately. Dad accepted an accounting and repayment obligations supported by the records. Brooke contributed toward amounts that had benefited her under the arrangement reached. I recovered some money promptly and the rest over time. I did not pretend that every misleading transfer inevitably produced a criminal conviction. Counsel evaluated the available remedies, and we used the process that could establish and enforce the obligations.
Dad moved with Noah into a smaller place he could maintain. Brooke found a room elsewhere and had to adjust her spending to her own earnings. I didn’t monitor her shopping afterward. I had wanted my money accounted for, not authority over every purchase she made. She resented me for months. Eventually, she sent an apology that mentioned the doorway and the leverage message without adding a request. I acknowledged it. That did not mean the old trust returned.
My relationship with Dad remained limited. He apologized for saying “Go to the VA” as though medical care could substitute for a home. I used veterans’ services and other appropriate resources, and I was grateful for the people helping me. None of that made his statement less cruel. He had taken an institution intended to support me and used its name to excuse refusing the help he promised. I told him that once, plainly.
He wanted to know whether we could start over. I said we could begin with accurate information and kept commitments. Starting over did not mean deleting the account history or arriving at his new door with another check. We spoke occasionally. Some conversations were strained. Some were better. I stopped treating improvement as proof that I should expose myself to the same financial arrangement again.
Rehabilitation continued, with goals that changed as my condition and abilities became clearer. I learned techniques that made daily tasks easier and accepted that some would continue requiring assistance. I returned gradually to work compatible with my recovery and skills. My life did not become meaningful because I defeated Dad in a money dispute. It became livable because I had competent care, dependable people, and room to make decisions without defending my right to need help.
I found a long-term accessible apartment. A friend helped hang shelves at the height I chose. Noah visited and immediately tested whether he could reach the top one. He couldn’t, which annoyed him enough to make me laugh. We built his model airplane at the kitchen table. He spilled glue, apologized three times, and watched my face. I handed him a cloth. “We can clean it,” I said. He stopped apologizing.
The blue blanket stayed over the back of my chair. I washed it carefully, afraid of losing the last trace of Mom, then learned that keeping something clean did not erase the person attached to it. Sometimes I used it while reading. Sometimes Noah wrapped himself in it during a movie. He no longer asked whether he was allowed. That small confidence felt more valuable than the principal repaid at closing.
One evening, he stood in the apartment doorway with an overnight bag. Dad had agreed to the visit, and the arrangements were settled. Noah held up a pillow. “Where should I sleep?” I pointed toward the couch we had prepared. “Right there, buddy.” He looked around, then smiled. Before he came in, I moved my chair aside and opened the door all the way.