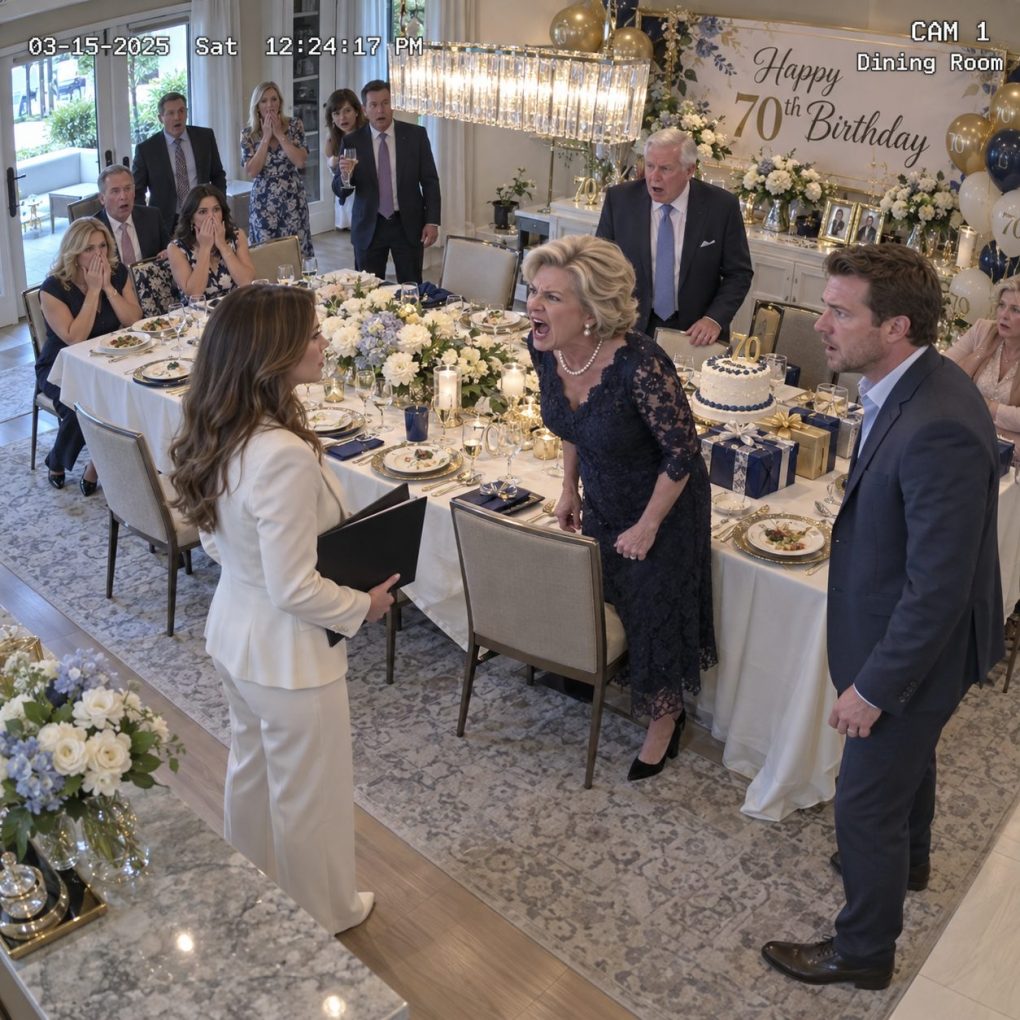
For ten years, my husband’s family treated me like a servant who should cook, clean, pay, and never complain. Even after the divorce, his mother called at 5 a.m. expecting me to prepare his father’s 70th birthday feast. I refused, grabbed one folder, and checked out of the hotel. Before the candles were lit, their accountant was asking them questions none of them knew how to answer.
My name is Claire Dawson, and I had been divorced from Michael Dawson for four months.
The marriage lasted ten years.
His family’s expectations lasted longer.
His mother, Diane, believed every gathering was somehow my responsibility.
Thanksgiving?
I cooked.
Christmas?
I paid for groceries.
His sister needed childcare?
I rearranged work.
His father, Robert, needed help with bookkeeping for the family hardware business?
I spent weekends cleaning up receipts because I was the only one with an accounting background.
Michael called it “helping out.”
I eventually called it unpaid labor.
The divorce should have ended it.
Instead, Diane phoned me at 5:03 a.m. on Robert’s seventieth birthday.
“Claire, the caterer canceled.”
I sat up in my hotel room.
I was in Nashville for a conference.
“So?”
“So you need to come home. We have forty people arriving tonight.”
I actually laughed.
Diane went silent.
Then she said, “After everything this family did for you?”
That sentence finished something inside me.
“No.”
She started listing dishes as if I had not spoken.
Roast beef.
Potatoes.
Three salads.
Robert’s favorite chocolate cake.
I hung up.
Then I opened my laptop.
Four months earlier, during the divorce, my attorney had told me to keep every financial document connected to the Dawson family business because I had spent years handling bookkeeping informally.
One folder bothered me more than the others.
It contained copies of checks, expense reports, and vendor invoices I had flagged before the separation.
At the time, Michael told me his father’s accountant had already reviewed everything.
I had believed him.
Now I looked again.
Payments labeled “equipment repair” had gone to companies I could not identify.
Personal restaurant charges had been coded as business expenses.
And several checks signed in my name had signatures I had never written.
That got my attention.
I called Martin Blake, the company’s outside CPA.
“I need to ask you something about Dawson Hardware.”
He listened quietly.
Then he said, “Claire, can you send me those records?”
I did.
Forty minutes later, he called back.
His voice had changed.
“Did you authorize any of these checks?”
“No.”
“Did Robert know you were keeping copies?”
“I don’t think so.”
There was a pause.
Then Martin said, “I’m going to the house before the party.”
I packed my suitcase.
Before leaving the hotel, I opened Diane’s last message.
You’ve embarrassed this family enough. Don’t make today worse.
I slipped the folder into my bag.
Then I checked out.
For once, Robert’s birthday dinner would happen without me doing the work.
But by dessert, his family would finally understand just how much work I had actually been doing.
Martin arrived at Robert and Diane’s house at 3:40 that afternoon, nearly two hours before the first guests. I was still driving back from Nashville when he called and asked whether I wanted to be present. I said no. I had spent ten years being dragged into Dawson family emergencies. This one could begin without me. What mattered was that the records were examined by someone independent.
The first problem involved six checks totaling just over $31,000. Each had been entered into the company ledger as payments for inventory or equipment service. Three carried what appeared to be my signature because, years earlier, Robert had occasionally asked me to countersign large payments when I helped reconcile books. I told Martin I had not signed those six.
He compared the checks with earlier originals. The signatures were similar but inconsistent. That did not automatically prove forgery, so Martin did not accuse anyone. Instead, he asked Robert for bank records, invoices, and supporting purchase orders. Robert could provide only two invoices, both from businesses Martin could not immediately verify.
The second problem was more embarrassing than criminal. Family vacations, restaurant dinners, furniture purchases, and even part of Michael’s bachelor-party weekend from years earlier had been run through Dawson Hardware as business expenses. Some might have had legitimate business purposes, but the documentation was poor. Martin warned that the tax treatment needed review and possibly correction.
Then came the vendor names. One company, RDM Supply Solutions, had received nearly $58,000 over three years. The address on several invoices matched a mailbox service. The contact number belonged to Michael’s younger brother, Jason. When Martin asked Robert what RDM supplied, Robert said “specialty hardware.” When he asked Jason, Jason said “consulting.”
Those answers did not match.
By then Diane had realized the birthday dinner was becoming a financial meeting. She called me furious. “What did you send Martin?” I said, “Copies of records I kept while doing your family’s bookkeeping for free.” She accused me of revenge. I reminded her that I had not created a single check, invoice, or expense entry.
Michael called next. His tone was different. “Claire, are you trying to get Dad in trouble?” I asked whether he knew about RDM Supply Solutions. The silence lasted too long. Finally he said, “Jason handled some vendor relationships.” That was not an answer.
I arrived back in town around six and went directly to my attorney’s office rather than the birthday party. Martin sent us a preliminary list of discrepancies. He wanted a formal internal review before making conclusions. I agreed. This was not about turning accounting mistakes into crimes for dramatic effect. It was about separating bad recordkeeping from intentional misuse.
The birthday party continued, though apparently very differently from what Diane had planned. The caterer problem was solved with restaurant delivery. Guests ate from disposable trays while Martin sat in Robert’s study reviewing files. According to Michael, Robert blew out his candles with barely half the family watching because everyone kept disappearing into the office.
The next morning, Martin discovered something that connected the financial records directly to me. One of the questionable checks had been dated during a week I was in Seattle for work. Yet someone had signed my name and entered a note saying I had “approved verbally.” My employer’s travel records showed I was more than two thousand miles away.
That check had gone to RDM.
Martin traced the deposit.
The receiving account was controlled by Jason.
Now the problem was no longer simply bad bookkeeping.
Robert called me personally for the first time since the divorce. He sounded older than I remembered. “Claire, did you know about any of this?”
“No.”
“Why didn’t you tell me sooner?”
I almost laughed.
“I tried for years to tell this family your books were a mess.”
He went quiet.
Then I said the part he needed to hear.
“You just preferred me when I was useful and silent.”
The formal review took almost four months. Martin brought in a forensic accountant because too many transactions involved related parties, missing documentation, and inconsistent signatures. The goal was not to prove the worst possible interpretation. It was to reconstruct what actually happened.
Jason eventually admitted that RDM Supply Solutions belonged to him. He had created the company to bill Dawson Hardware for procurement work he claimed he was doing informally. Some services were real. The problem was that Robert had never properly approved the arrangement, the prices were inflated, and several invoices described goods that were never purchased.
Michael knew more than he first admitted.
He had helped Jason process a few of the payments because he believed their father would “make a big deal” about paying a relative. He insisted he did not know about the checks bearing my name.
The forensic accountant found no evidence that I had benefited financially from any of the questionable transactions.
That mattered because my name had appeared in the bookkeeping often enough that, without my copies, I could easily have been pulled into arguments about who authorized what.
Robert’s role was more complicated.
He had not invented RDM, but he had run the company with terrible controls.
He allowed family members to submit expenses without documentation, mixed personal and business purchases, and signed reconciliations he barely reviewed.
The company was not destroyed.
But it had to correct tax filings, repay certain deductions, restructure its accounting procedures, and negotiate restitution from Jason for unsupported charges.
Jason avoided the criminal nightmare Diane initially feared.
The dispute was resolved largely through civil repayment, amended tax treatment, and his permanent removal from company finances.
The forged-looking signatures remained serious, but investigators could not establish exactly who had written each one to the standard required for prosecution.
Martin’s documentation nevertheless made sure they could never be used against me.
Michael apologized before anyone else.
Not for the divorce.
For the decade before it.
He admitted that he had watched his family treat my competence like a household utility: always available, never thanked, and only noticed when it stopped working.
“I thought because you could handle everything, it was easier to let you,” he said.
I answered, “That was exactly the problem.”
Diane resisted longer.
For months she insisted the entire scandal had started because I sent Martin the folder.
Eventually Robert corrected her in front of everyone.
“No,” he said. “It started because we had problems in the books. Claire only stopped hiding them for us.”
That was the first time he publicly acknowledged what I had done for the family.
Too late to save the relationships.
But not too late to tell the truth.
Dawson Hardware survived under tighter controls.
Robert retired from daily management the following year.
A professional controller replaced the family system of favors and handwritten notes.
Michael kept his distance from the finances.
Jason repaid the company over time.
And Diane finally stopped calling me before sunrise.
My own life became remarkably quiet.
I stayed in corporate accounting, traveled when I wanted, and learned what weekends felt like when nobody expected me to solve a crisis before breakfast.
The folder stayed in my filing cabinet for years.
Not because I wanted to remember the Dawsons.
Because it reminded me of something I had spent a decade forgetting.
Competence is not consent.
Being good at helping does not create an obligation to help forever.
And people who benefit from your silence may call it loyalty right up until the moment you start keeping records.
Robert’s seventieth birthday was supposed to be another day when I cooked, cleaned, paid, and disappeared into the background while everyone else celebrated.
Instead, I said no once.
That single refusal did not cause their problems.
It simply stopped me from carrying them.
And that was the lesson I kept after the marriage, the audit, and the family finally settled down: sometimes the healthiest thing you can do is stop proving how useful you are to people who have never bothered proving how much they value you.