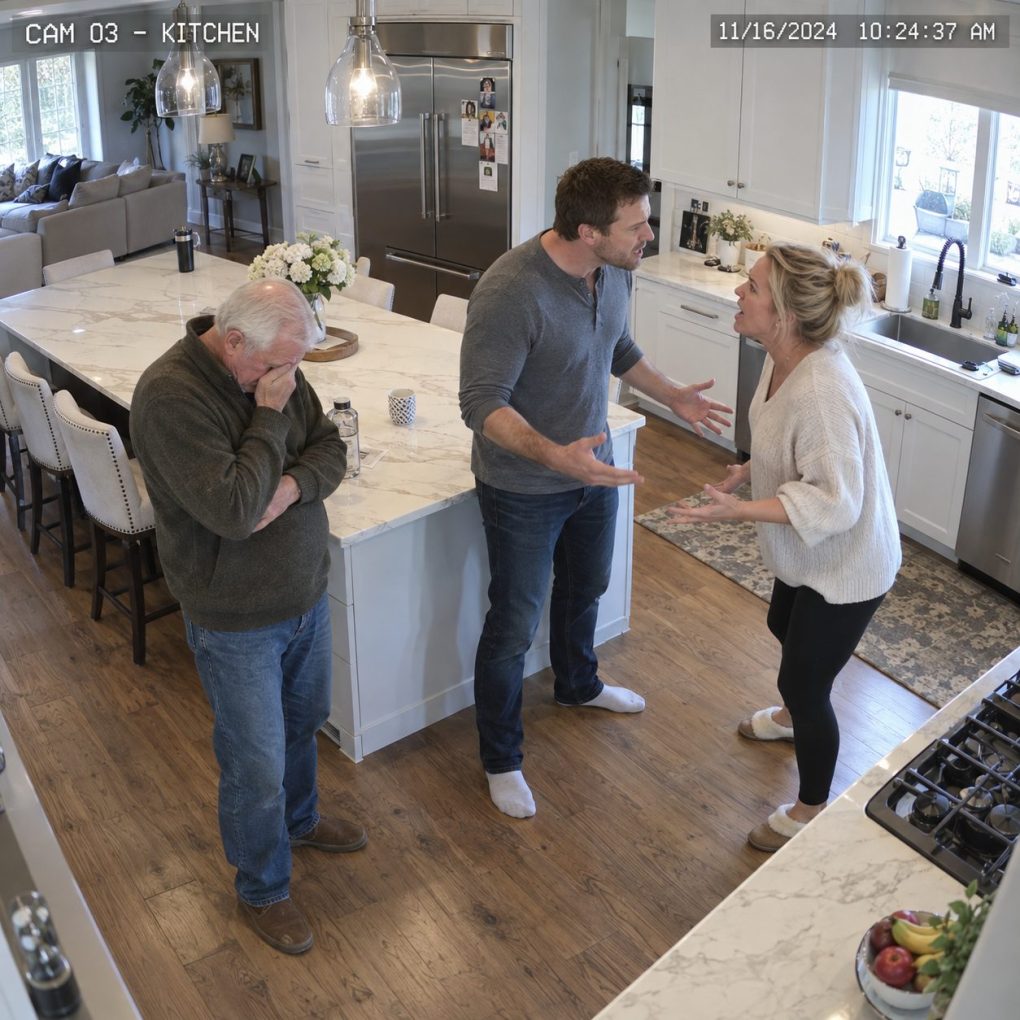
Dad had never asked me for money before, so when he quietly requested $1,000, I knew something was wrong. My wife didn’t even let him finish before humiliating him in my own kitchen. She thought she was defending our finances. Then I reminded her exactly who had paid the down payment on the house she was standing in.
My name is Daniel Brooks, and my father, Walter, had spent most of his life helping everyone except himself.
When I was twenty-six and newly married, he gave me $85,000 from the sale of a small rental property so my wife, Megan, and I could buy our first home outside Columbus, Ohio.
He never asked for repayment.
He called it an early inheritance.
Megan knew that.
At least, I thought she did.
Seven years later, Dad came over on a Tuesday evening looking older than he had the week before.
He waited until Megan finished dinner.
Then he cleared his throat.
“Danny, could I borrow a thousand dollars?”
I stared at him.
Dad hated debt.
If he was asking, something was wrong.
Before I could respond, Megan laughed.
“A thousand dollars?”
Dad’s face tightened.
She continued.
“What happened to all that retirement planning you’re always bragging about?”
“Megan,” I warned.
She ignored me.
“We have a mortgage, childcare, insurance. We aren’t an ATM because somebody didn’t budget properly.”
Dad looked down.
“I can explain.”
“You shouldn’t have to,” I said.
Megan turned toward me.
“You’re seriously going to hand him money without even asking why?”
I looked around our kitchen.
Granite counters.
New cabinets.
The breakfast nook Dad had helped me build himself.
Then I asked her something.
“Do you remember where the down payment for this house came from?”
She frowned.
“That was different.”
“Was it?”
“Your father offered.”
I nodded.
“And now he’s asking for one thousand dollars.”
Dad stood.
“Forget it. I shouldn’t have come.”
I stopped him.
“No. Sit down.”
Megan crossed her arms.
I transferred the money from my personal account before Dad could object.
Then I asked why he needed it.
He hesitated.
“My prescription coverage changed. One of the heart medications isn’t covered this month, and I didn’t want to put it on a credit card.”
Megan’s expression shifted.
But not enough.
She muttered, “You should’ve said that first.”
Dad looked at her quietly.
“I was trying to.”
That was the moment I realized the problem was bigger than one rude sentence.
Megan did not just want financial caution.
She had begun treating generosity as something only she was allowed to approve.
Dad left twenty minutes later.
I walked him to his truck.
Before leaving, he handed me an envelope.
“What’s this?”
“Something I should’ve given you years ago.”
Inside was a copy of the original $85,000 transfer.
Attached was a handwritten note.
For Daniel’s home. No repayment expected.
I stared at it.
Dad said, “Your wife asked me last month whether I had proof that money wasn’t a loan.”
I looked up.
And suddenly Megan’s humiliation of him made a very different kind of sense.
I waited until Dad drove away before confronting Megan. I placed the old transfer record on the kitchen table and asked why she had questioned him about the down payment. She stared at the paper for several seconds before admitting she had recently met with a divorce attorney. She said it was “only informational” and accused me of making something ordinary sound suspicious.
That explanation did not calm me. We had argued more over the previous year, mostly about money and my parents, but I had never understood that Megan was already gathering documents. She believed that if Dad’s $85,000 had been a loan rather than a gift, it could affect how the house equity would be treated if our marriage ended. She had been trying to establish the answer without telling me.
I asked whether she actually wanted a divorce. She said she did not know. Then she added, “I’m tired of your family always coming before us.” I almost laughed because Dad had asked us for money exactly once in seven years. Meanwhile, Megan’s mother had stayed with us for four months after surgery, and we had paid several thousand dollars toward her sister’s legal fees the previous year.
When I pointed that out, Megan said her family’s situations were “real emergencies.” That sentence told me more than she intended. She had divided our families into people whose needs deserved compassion and people whose needs required suspicion. My father had somehow landed in the second category despite helping us buy the house we were arguing inside.
The next morning, I called a family-law attorney of my own. Not because I had decided to divorce, but because discovering your spouse had quietly sought legal advice changes what ignorance can safely accomplish. My attorney, Sarah Miller, reviewed the down-payment paperwork and explained that the exact treatment would depend on state law, title, tracing, and other facts. The handwritten note helped show Dad intended a gift, but it was not a magic answer to every property question.
That distinction mattered. I did not want to turn Dad’s generosity into a weapon against Megan. I wanted accurate records so nobody could later rewrite what happened. Sarah advised me to preserve bank statements, stop making unusual transfers, and keep marital finances transparent while Megan and I decided whether the relationship could continue.
Then Dad called. He had received a voicemail from Megan apologizing and offering to repay the $1,000 herself. I asked him not to get involved in our marital disagreement. He sounded embarrassed. “I don’t want to be the reason you two fight.” I told him the truth: he was not the reason. His request had only revealed an argument that already existed.
Megan and I started counseling two weeks later. During the second session, she admitted that her fear had intensified after one of her friends went through a financially ugly divorce. She had become obsessed with making sure she would never be “the stupid wife who didn’t prepare.” I understood the fear. What I did not accept was the way she had turned preparation into hostility toward people who had done nothing to her.
The counselor asked why Megan humiliated Dad instead of simply asking what the money was for. She said, “Because I thought if I sounded firm, Daniel would understand I was protecting our household.” I answered, “You weren’t protecting us. You were trying to establish that you had veto power over whether my father deserved dignity.”
That conversation was ugly but useful. For the first time, Megan apologized without immediately defending the insult. She called Dad again, this time with me present, and said, “I judged you before letting you speak. I’m sorry.” Dad accepted the apology politely, though I could hear the distance in his voice.
Then Sarah discovered one more detail in our financial records. Over the previous six months, Megan had transferred $14,000 from our joint savings into an account solely in her name. She had not spent it. The money was still there. But she had never told me it existed.
When I asked why, she said it was an emergency fund in case I “chose my family over her.” That was when the marriage counseling stopped being theoretical. We were no longer arguing about $1,000. We were arguing about whether fear had already replaced trust.
Megan returned the $14,000 to the joint account the same day. I appreciated that, but returning money did not erase why she had moved it. Our counselor told us not to rush into either reconciliation or divorce. Instead, she asked us to make every financial decision completely transparent for ninety days and see whether trust could survive ordinary life rather than promises made during crisis.
Those ninety days were uncomfortable. We opened every account together, listed every family-related expense from the previous five years, and created written rules for helping relatives. Any gift above a certain amount required discussion. Emergency medical help could happen immediately within a smaller limit. Most importantly, neither of us could insult or interrogate the person asking for help as a condition of considering the request.
The numbers embarrassed Megan. We discovered that over five years we had spent nearly three times as much helping her relatives as mine. I had never tracked it because I did not think marriage should operate like a scoreboard. Megan stared at the spreadsheet for a long time and said, “I honestly thought it was the opposite.” Fear had edited her memory until every request from my side felt bigger than it was.
Dad’s situation improved quickly. His insurance issue was corrected the following month, and he tried to repay the $1,000. I refused. He finally accepted that but insisted on taking my children fishing that weekend and returning with enough groceries to feed us for a week. That was Dad’s way of recovering his pride without turning love into debt.
His relationship with Megan took longer. He remained polite but stopped dropping by unannounced. He did not ask her for favors. He seemed determined never to give her another reason to think he needed something from us. Watching that distance bothered Megan more than any argument could have.
One evening, she told me, “I think I made him feel like everything he ever did for us had expired.” I said, “That’s exactly what happened.” She cried. I did not rush to make her feel better. Some realizations need enough discomfort to become permanent.
We did not divorce.
That was not because Dad’s down payment trapped us financially or because one apology fixed everything. We stayed because Megan changed her behavior consistently, and because I admitted I had also avoided difficult financial conversations for years. I often said yes to family requests first and explained later because I assumed generosity was obviously good. Marriage required more communication than that.
The difference was that communication could not become permission for cruelty. We learned to ask questions without humiliation, to say no without contempt, and to distinguish caution from suspicion. Those sounds similar until you live with them. Caution protects resources. Suspicion starts treating people like threats before they have done anything wrong.
Two years later, Dad sold the last piece of land he owned and invited us to dinner. After dessert, he handed Megan a small envelope. Her face went pale immediately. Inside was not money. It was the original handwritten note from seven years earlier about the $85,000 down payment.
Dad said, “I think you should keep this.”
Megan shook her head.
“No. Daniel should.”
Dad smiled. “It belongs to both of you now. You learned what it means.”
She cried and hugged him.
That was the moment I knew something had genuinely healed.
The house itself eventually became less important. We refinanced years later, renovated the basement, watched our children grow taller against the kitchen doorframe, and eventually sold the property when we moved closer to Dad.
But I never forgot the night he asked for $1,000.
For years, I had thought generosity was mostly about having enough to give.
It isn’t.
Generosity without memory can become entitlement.
Financial caution without empathy can become cruelty.
And marriage without trust can turn even responsible planning into secret preparation for war.
Dad had given us $85,000 when we were young because he wanted us to begin adult life with less fear.
Years later, he asked for $1,000 because he needed help getting through one difficult month.
The amount was almost irrelevant.
What mattered was whether we remembered who was sitting across from us.
That became the lesson of the house.
Never let spreadsheets make you forget history.
Never let fear turn someone’s vulnerability into an opportunity to establish power.
And never assume dignity should depend on whether a person arrives at your kitchen table asking for money or offering it.
The down payment built the house.
But gratitude was what finally taught us how to deserve living in it.