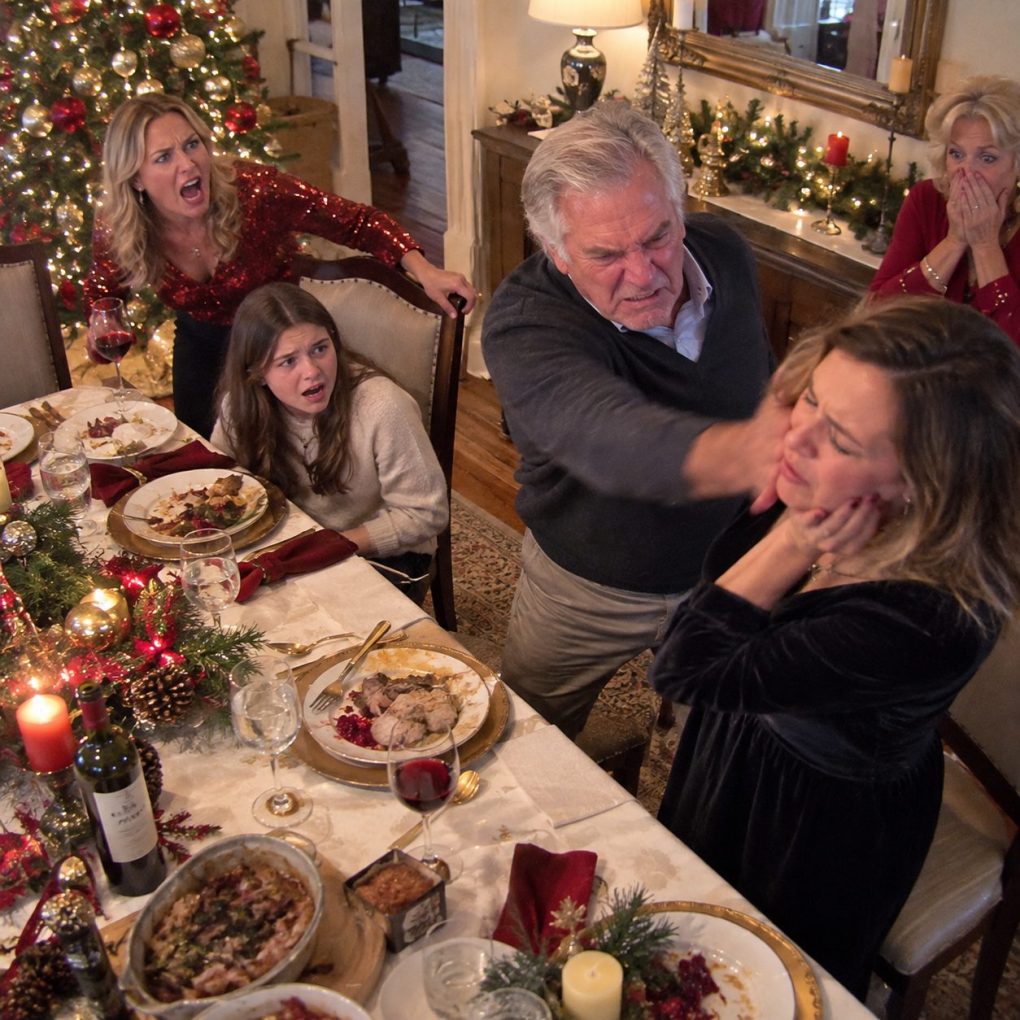
Christmas dinner exploded before dessert at my parents’ house outside Columbus, Ohio. My fourteen-year-old daughter, Lily, had barely touched her food because my sister Vanessa had spent the evening mocking her thrift-store dress, her scholarship, and the fact that she attended public school, but Lily kept squeezing my hand beneath the table and whispering, “Mom, please don’t make this worse.”
Then Vanessa smiled across the table and said, “Scholarships are what people brag about when they can’t afford the real thing.” I put down my fork and told her not to speak to my daughter that way again, but Dad immediately slammed his palm against the table and accused me of “starting drama on Christmas.”
“You heard what she said,” I told him. “Why am I the problem?” Dad stood so quickly his chair scraped across the hardwood, shouting that Vanessa knew how to respect family while I acted superior because I made more money than everyone else.
That accusation almost made me laugh. For six years, my money had quietly covered their mortgage, homeowners insurance, utilities, property-tax shortages, and every emergency Dad described as temporary. I had never announced it at family dinners because I thought helping my parents was something decent people did without keeping score.
I reminded him of that only because he kept shouting.
His face twisted.
Then he slapped me.
Lily screamed, Mom covered her mouth, and Vanessa froze. Dad leaned close enough that I smelled the wine on his breath and shouted, “You’re trash. You always have been.”
Something inside me went completely still.
I wiped my cheek, picked up my phone, and called my financial manager, Claire Benson. “Stop every recurring payment connected to my parents,” I said. “Mortgage support, utilities, insurance, taxes. Everything. Starting with this house.”
Dad’s anger disappeared instantly.
“You wouldn’t.”
“I just did.”
Claire began confirming the cancellations, then suddenly stopped. “Emma, before I process the mortgage support, I need you to know something.”
Everyone at the table was listening now.
“What?”
“The account you’ve been funding changed six months ago.”
Dad went pale.
Claire continued, “Your father refinanced the property.”
I looked directly at him.
“How much?”
He said nothing.
Claire answered for him.
“One hundred and forty-two thousand dollars in cash came out of the house.”
Vanessa dropped her eyes.
And that was the moment I realized Christmas dinner had not exploded because my sister insulted my daughter.
It had exploded because I had finally asked where my money was actually going.
Dad finally admitted that most of the refinance money had gone to Vanessa. Her event-planning company had been collapsing for nearly a year, buried under an expensive downtown lease, unpaid taxes, vendor balances, and a luxury SUV she insisted she needed to impress clients, so Dad had increased the mortgage while continuing to let me believe my $4,800 monthly contribution was keeping my parents secure.
I stared at Vanessa. “You humiliated my daughter for not looking rich enough while my money was covering your debts?” She snapped that Dad had chosen to help her and accused me of making everything transactional, but that only made the truth uglier.
“You made it transactional when you treated my support like an entitlement.”
Dad demanded that I restore the payments before January’s mortgage was due. He called the slap “one bad moment” and said I was willing to destroy Mom’s retirement over hurt feelings, but Lily flinched beside me when he raised his voice, and that reaction mattered more than every excuse he made afterward.
I took her coat and told Mom she could contact me when she was ready to speak without Dad or Vanessa controlling the conversation. We were halfway to the car when Claire texted me again.
She had located a copy of the refinance application.
Under ANTICIPATED HOUSEHOLD CONTRIBUTION, Dad had listed my $4,800 monthly payment as permanent recurring support. Next to my name was a signature stating that I intended to continue funding the property after refinancing.
I had never signed it.
The next morning, I sent the document to an attorney and notified the lender that the signature was not mine. At first I assumed Dad had simply forged my consent because the bank wanted proof of continuing household income.
Then my attorney called.
“Emma, there’s something odd here.”
The signature on the refinance document was not the only document carrying my name.
A second authorization had been submitted weeks later.
This one approved a transfer from the refinance proceeds into an account Dad described as a “family emergency reserve.”
The receiving account did not belong to Dad.
It belonged jointly to Mom and Vanessa.
I felt my stomach drop.
“How much?”
My attorney paused.
“Sixty-eight thousand dollars.”
For years, I had believed I was paying for my parents’ house.
Now I was staring at proof that my name had been used to move money I never agreed to provide.
Then my attorney said the sentence that changed everything.
“Emma, the bank wants to know whether you authorized any of this.”
And suddenly I understood that Dad had not just expected me to keep paying.
He had built the entire refinance around the assumption that I would never dare stop.
The lender opened a formal review after I confirmed in writing that I had never signed either document. I was not a borrower or guarantor, so I was legally free to stop every payment, but Dad was now responsible for explaining why my name appeared on paperwork supporting a loan he could not comfortably afford without me.
Mom called two days later.
She admitted she knew about the $68,000 transfer but insisted she had not known Dad signed my name. The money had been divided between Vanessa’s tax debt, overdue business rent, and a reserve Mom kept because she was afraid Vanessa would lose everything if another emergency happened.
“Another emergency,” I repeated.
Mom started crying.
I asked her one question.
“When was I allowed to have one?”
Silence.
That was when I finally understood the family system I had spent years financing. Vanessa was allowed to fail dramatically because everyone rushed to rescue her, while I was expected to succeed quietly because my stability was useful.
The bank eventually concluded that I had no liability for the refinance. My attorney helped me document the false authorizations, and after months of negotiation, Dad agreed to correct the record rather than drag the family into a longer legal fight.
The financial consequences were immediate.
My parents sold the house before they fell behind on the larger mortgage. After paying the loan and closing costs, they still had enough equity to buy a smaller condo, but the lifestyle my money had supported was over.
Vanessa’s business finally had to shrink to what it could actually afford. She surrendered the downtown lease, sold the SUV, moved into a shared workspace, and entered payment plans for the remaining taxes and vendor debt.
For months, she blamed me.
Then Dad surprised everyone.
During one family meeting, Vanessa snapped, “Emma ruined everything when she shut off the money.”
Dad looked at her and said, “No. We ruined everything when we spent money that was never ours to promise.”
It was the first time he defended me without needing something afterward.
That did not repair what he had done.
Dad and I went almost nine months without speaking. When he finally asked to meet, he arrived without Mom and without excuses.
“I slapped you because you challenged Vanessa in front of me,” he said. “But that wasn’t really why.”
I waited.
“You were proof that someone in this family could say no to me and survive.”
For once, the truth sounded uglier than any excuse.
He apologized for the slap, the forged signature, and for resenting the daughter whose money he had depended on. I did not forgive him that afternoon, but I listened.
Lily chose not to see him for several more months.
I supported that completely.
The following Christmas, she and I stayed home. We made pasta, burned a pie, watched terrible movies, and laughed until nearly midnight without anyone insulting her, demanding money, or deciding peace mattered more than respect.
At one point, Lily asked, “Do you miss the old Christmases?”
I thought about the house, Vanessa’s smile, Dad’s hand across my face, and all those years I had mistaken being useful for being loved.
“No,” I said. “I miss the family I kept hoping we would become.”
Stopping the automatic payments did not destroy us.
It exposed the structure that had been holding us together.
My money had paid the mortgage, covered the emergencies, protected Vanessa, and allowed everyone else to avoid the consequences of their choices.
The moment I stopped paying, every relationship had to stand on its own.
Some collapsed.
Some changed.
A few slowly became honest.
And for the first time in my life, I understood something I should have learned years earlier:
If love disappears the moment you stop funding it, it was never love asking for help. It was dependence wearing a family name.