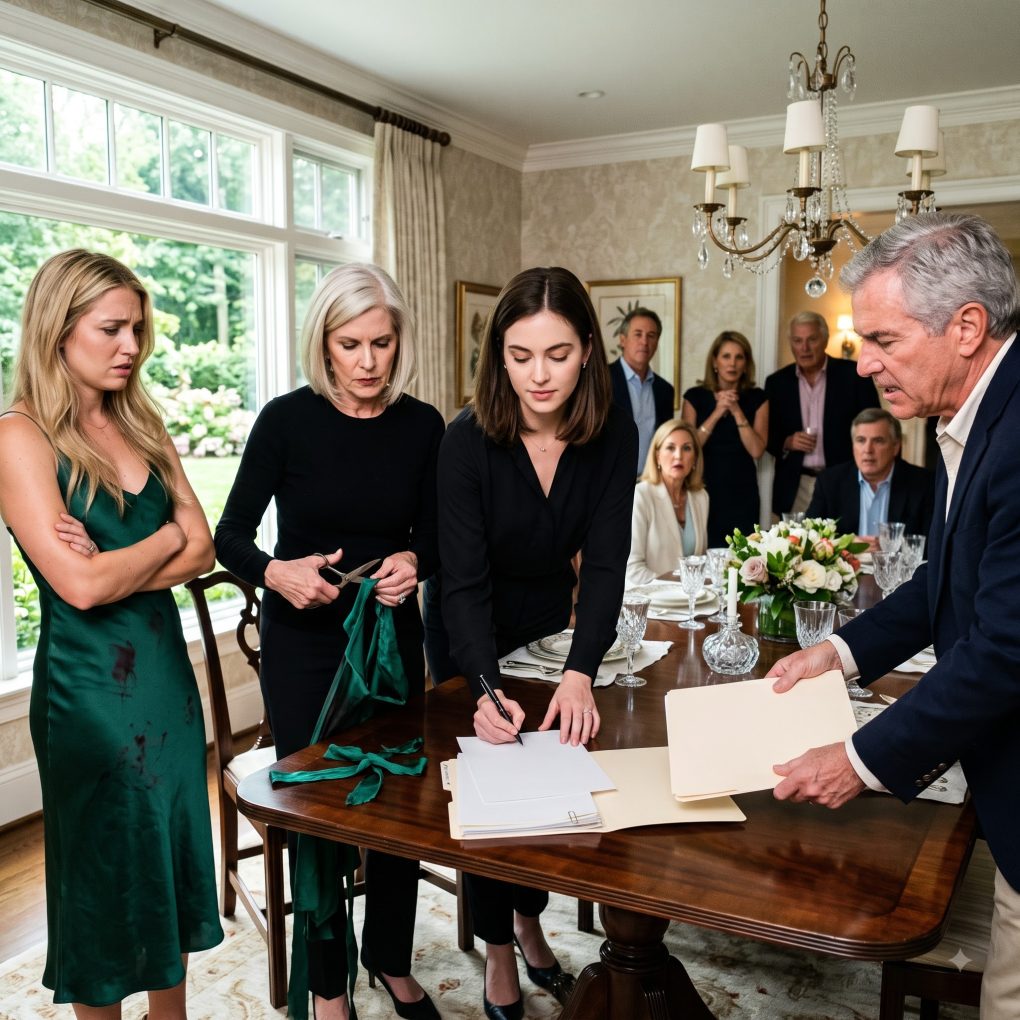
The first thing I saw at my twenty-fifth birthday dinner was my sister wearing my dress.
Not a similar dress.
Mine.
The emerald silk wrap dress I had bought for four hundred dollars after landing my first major client was clinging to Chloe’s body, soaked from shoulder to hem with red wine.
She stood in my parents’ dining room surrounded by candles, crystal glasses, and a dozen of their wealthiest friends from Greenwich. Everyone had gone quiet.
“You went through my closet?” I asked.
Chloe rolled her eyes. “It was just sitting there.”
Before I could reach for the dress, my mother, Diane, grabbed a pair of kitchen scissors.
“Mom, what are you doing?”
“It’s ruined.”
She cut straight through the skirt.
The sound of silk tearing was oddly small.
Chloe laughed nervously. “There. Now you can stop being dramatic about it.”
I stared at the strips falling onto the counter.
My father, Robert, cleared his throat as if we had finished discussing an appetizer.
“Since everyone is here, there’s something else we need to settle.”
He placed a folder in front of me.
Inside was paperwork from a local bank for a fifty-thousand-dollar small-business loan Chloe wanted for her boutique. The page clipped on top was a preliminary guarantor authorization bearing my name.
I looked up. “You want me to guarantee this?”
Dad smiled toward his guests. “Your sister needs someone with strong income and credit. Family helps family.”
Chloe folded her arms. “It’s not like I’m asking you to give me fifty thousand.”
Mom dropped the ruined pieces of my dress into the trash.
“After everything we sacrificed for you,” she said, “this shouldn’t even be a discussion.”
That sentence had followed me for years.
They had sacrificed for college, although I paid my last two years myself.
They had sacrificed by letting me live at home after graduation, although I covered the mortgage whenever Dad’s commissions were slow.
They had sacrificed by “keeping the family together,” while my cards paid groceries, Mom’s car insurance, Chloe’s rent twice, and the country-club dues Dad insisted were essential for business.
I had never added it all up.
Until that week.
I ran a financial compliance company. Details were literally how I earned my living.
So I already knew something they didn’t.
The document Dad pushed toward me was not the final personal guaranty. The bank still required identity verification, income certification, and a notarized closing packet before funding the next morning.
I picked up the pen.
Chloe smiled.
Mom whispered, “Finally.”
I signed the preliminary authorization.
“I’ll handle it,” I said.
Dad lifted his wineglass as though I had surrendered.
At 2:07 a.m., after the guests were gone, I packed two suitcases.
At 2:14, I removed my parents and Chloe as authorized users from every credit card they had been using.
At 2:18, I emailed the bank withdrawing consent before closing and requested a fraud review of the application.
Then I placed one envelope on the dining table.
Across the front I wrote:
THE TRUE COST OF YOUR “FAMILY SACRIFICES.”
Inside was a seven-page spreadsheet.
The total at the bottom was $236,418.
As I closed the front door behind me, I heard my father coming downstairs.
They thought canceling a few credit cards was my entire revenge. By sunrise, one call from the bank would expose why Dad needed my signature so badly—and prove that the $50,000 loan was never really about Chloe’s boutique.
My father reached the foyer just as I pulled away.
He called six times before I reached the highway.
I didn’t answer.
At 7:43 the next morning, Chloe called from a gas station.
“What did you do to my card?”
“My card,” I corrected. “You were an authorized user.”
“You stranded me.”
“You have your own debit card.”
“It’s overdrawn.”
“That sounds like information you should have had before buying a boutique.”
She hung up.
Ten minutes later, Dad called from the country club because his membership charge had been declined. Mom texted that the grocery card was “suddenly broken.”
Then they opened my envelope.
Dad called again.
“Two hundred thirty-six thousand dollars? This is insane.”
“No,” I said from my hotel room. “It’s categorized.”
For seven years, I had kept records because my accountant required them. The spreadsheet included $41,600 in mortgage payments, $18,900 for property taxes, $12,480 in utilities, $27,300 for Chloe’s rent and emergencies, $16,700 toward Mom’s SUV, $9,840 in country-club charges, and thousands more in insurance, vacations, repairs, restaurant bills, and credit-card payments.
The largest category was something my parents never mentioned when describing their sacrifices.
Seventy-four thousand dollars I had transferred after Dad told me his consulting business was “temporarily underwater.”
Mom’s voice came through the speaker.
“You lived under our roof.”
“I paid more toward that roof than either of you did for years.”
Dad snapped, “You’re humiliating us over money.”
“No. I stopped paying.”
Then my business attorney, Lauren Price, called.
The bank had responded to my fraud-review request.
“Emily, did you ever agree to be a silent partner in Chloe’s boutique?”
“No.”
“That’s what the loan application says.”
I sat up.
Lauren forwarded it.
The application listed me as a twenty-five-percent owner and claimed my compliance firm would provide continuing financial support. Attached was a letter on my company’s letterhead confirming the arrangement.
I had never written it.
My electronic signature had been copied from an old family tax document.
Suddenly, Dad’s public pressure at dinner made sense.
The preliminary form I signed would have helped them argue that I had approved the arrangement after the fact.
“Did the bank fund anything?” I asked.
“No. Your withdrawal arrived before closing. They’ve frozen the file.”
I felt my pulse slow.
Then Lauren sent one more attachment.
The bank had asked Chloe what the fifty thousand dollars would be used for.
Her budget showed inventory, advertising, and store renovation.
But an internal email from Chloe to Dad said something completely different.
If Emily signs tomorrow, use the first $32K to clear your line before she notices. I only need the rest.
This was not Chloe’s fifty-thousand-dollar business loan.
My parents had planned to use my guarantee to cover Dad’s debt.
And the seventy-four thousand dollars I had already given him?
Lauren went silent after reviewing the statements.
“Emily,” she finally said, “I don’t think that money ever went into his business.”
She highlighted three transfers I had never seen before.
All of them left Dad’s account within twenty-four hours of receiving my money.
Every transfer went to an investment account held jointly by Robert and Diane Mercer.
The seventy-four thousand dollars had gone into my parents’ brokerage account.
Not Dad’s business.
Not the mortgage.
Not some emergency.
Their statements showed that while they were telling me they were barely surviving, they were investing my transfers and paying ordinary household expenses with my credit cards.
Over four years, the account had grown to almost ninety-one thousand dollars.
Lauren looked at me across her conference table.
“They treated your money like income and preserved theirs like wealth.”
That explained everything.
Every crisis had been urgent because urgency stopped me from asking questions.
Every reminder about “family sacrifices” made me feel guilty enough to pay quickly.
And Chloe had learned the same system.
I did not call my parents that day.
Lauren sent the bank a formal statement denying the forged ownership letter and signature. Because the loan had not funded, I had no fifty-thousand-dollar debt to guarantee. The bank closed the application and referred the falsified documents to its fraud department.
My parents hired a lawyer.
Within a week, their lawyer proposed something surprisingly simple: repayment, confidentiality, and no further use of my identity or company name.
I refused confidentiality.
I did not threaten to publicly shame them, but I would not sign anything requiring me to pretend the documents were legitimate.
We eventually reached a written settlement. My parents returned the original seventy-four thousand dollars from their brokerage account and repaid several recent charges they could not justify. I did not demand every grocery bill or birthday dinner back.
I wanted separation, not another lifetime of accounting.
Chloe’s boutique never received the loan.
She sold part of her inventory, moved to a cheaper storefront, and learned very quickly that suppliers preferred money to family speeches.
My father resigned from the country club.
Mom sold the SUV.
The house did not disappear.
Neither did they.
That was important.
For years, they had made every boundary sound catastrophic. If I stopped paying, the mortgage would collapse. Dad’s work would collapse. Chloe’s future would collapse. The family itself would collapse.
I stopped.
Life continued.
Three months after my birthday, I moved into a small townhouse fifteen minutes from my office. On the first night, I ate takeout on the floor because my dining table had not arrived.
There was nobody asking for my card.
Nobody explaining what I owed them.
Nobody entering my closet.
Chloe texted once about the dress.
I’m sorry Mom cut it up. I shouldn’t have worn it.
I believed that was as close to an apology as she knew how to give.
I never replaced the dress.
I kept one strip of emerald silk I had pulled from the kitchen trash before leaving.
Not as a symbol of four hundred dollars.
As a reminder of the moment I finally understood the difference between helping people I loved and financing people who believed loving them meant I could never say no.
My twenty-fifth birthday cost me one dress, one house key, and the family story I had believed for years.
It also ended a $236,418 bill that was never mine to keep paying.