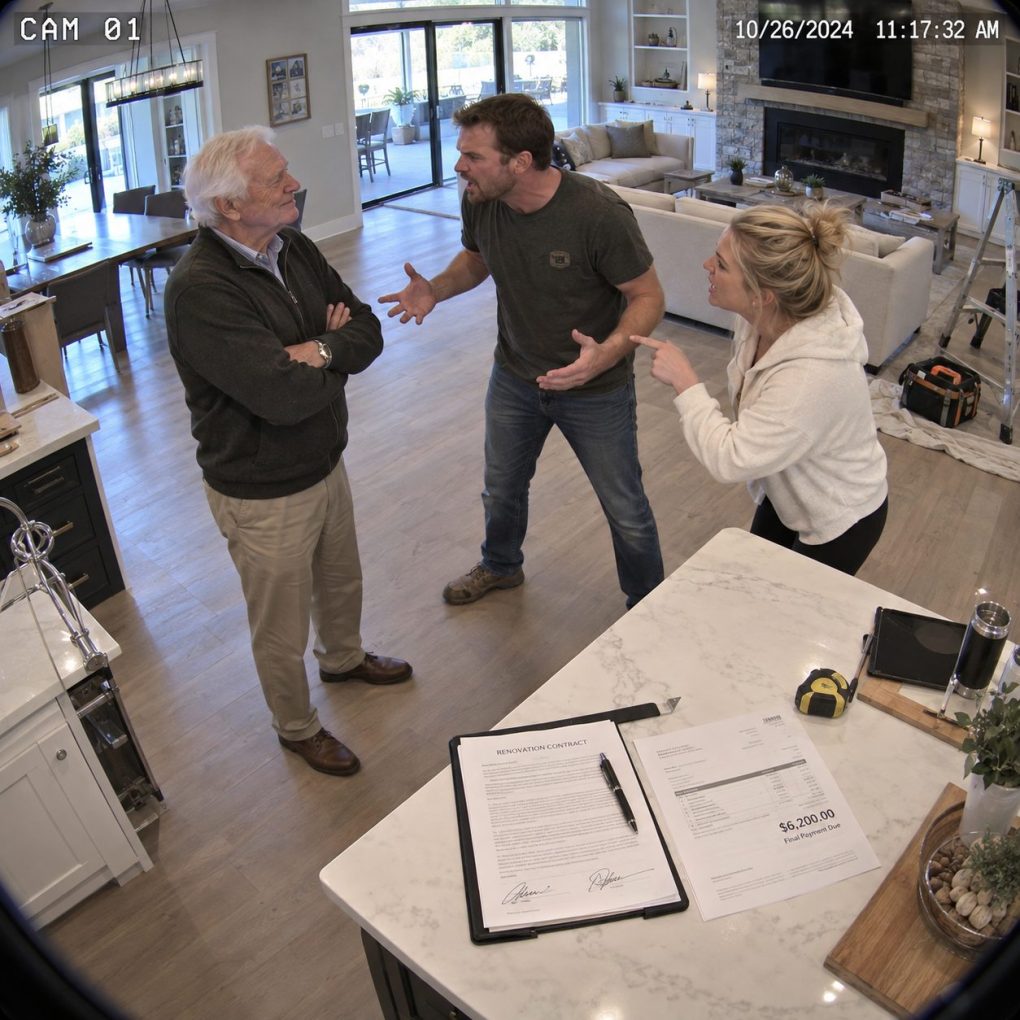
The couple stood inside the beautifully renovated house my grandfather had spent months fixing and told him they weren’t paying the final $6,200. Frank didn’t threaten them or raise his voice. He looked around the room, smiled, and walked out. A few hours later, they finally read the clause they had signed before the first cabinet was installed.
My grandfather, Frank Bennett, was seventy-two and had been a licensed contractor in North Carolina for almost forty years.
He was not wealthy.
He was careful.
That mattered more.
The homeowners, Tyler and Madison Cole, had hired him to renovate an aging bungalow outside Raleigh.
New kitchen.
Two bathrooms.
Flooring.
Electrical upgrades.
Custom built-ins.
The total contract was $86,400.
They paid in stages exactly as agreed.
Until the last one.
Frank completed the final walk-through on a Friday afternoon.
Madison opened cabinets, tested faucets, and complimented the tile.
Tyler shook Frank’s hand.
Then he said, “We’re not paying the last sixty-two hundred.”
Frank thought he was joking.
“What problem needs correcting?”
“Nothing.”
Tyler smiled.
“We’ve already paid enough.”
Madison leaned against the new quartz island.
“My brother says contractors always build extra profit into the last payment.”
Frank looked around.
Every punch-list item had been completed.
Every permit inspection passed.
Every change order had been signed.
He asked once more.
“Are you withholding payment because you believe the work is defective?”
“No,” Tyler said.
“We just think the price was too high.”
Frank nodded.
“All right.”
That response confused them.
Madison laughed.
“That’s it?”
“That’s it.”
He packed his inspection folder.
Then he walked out.
I was waiting in his truck because I had promised to take him to dinner.
“What happened?” I asked.
“They decided not to pay.”
“You’re just leaving?”
Frank started the engine.
“They already signed the answer.”
Three months earlier, before demolition began, Frank had insisted on a detailed contract drafted by his construction attorney.
Page fourteen contained the provision Tyler and Madison had apparently forgotten.
If undisputed final payment remained unpaid after written notice and the required cure period, Frank could pursue every remedy allowed under state law, including interest, attorney fees where recoverable, collection costs under the contract, and a construction lien against the property if statutory requirements were met.
More importantly, they had signed a separate completion certificate that afternoon acknowledging the work was satisfactory.
At 6:08 p.m., Frank emailed the formal invoice and notice.
At 7:31, Tyler replied:
We already told you we aren’t paying. Stop threatening us.
Frank forwarded it to his attorney.
At 9:14, Madison apparently read page fourteen.
At 9:22, Frank’s phone rang.
He ignored it.
Then came a text.
Can we talk about the $6,200?
Frank smiled.
“Now they’ve read the contract.”
Frank did not immediately file anything against the house. His attorney, Laura Mitchell, was careful about that because construction liens are governed by strict deadlines, notices, and statutory requirements. A contractor cannot simply write “lien” on a piece of paper because a customer is annoying. Frank had kept the documents precisely so every step could be handled correctly.
Laura reviewed the contract, invoices, inspection approvals, change orders, and completion certificate. Tyler and Madison had signed that certificate after walking through the finished project. They had listed two tiny items—an uneven cabinet hinge and a paint touch-up near the pantry—and Frank corrected both before leaving. Their refusal was not based on an unresolved defect.
The contract gave them a short written period to dispute specific charges. Instead, Tyler had written that the renovation looked excellent but he believed contractors “expect customers not to negotiate the final payment.” Laura almost laughed when she read it. Negotiation usually happens before someone signs a fixed-price contract, not after receiving everything promised.
Frank sent the required notice and waited.
Three days later, Tyler offered $3,000 “to make the issue disappear.” Frank declined. He was not demanding more than the contract price. He simply wanted the balance already earned. Madison then accused him of taking advantage of young homeowners because he knew they had just spent most of their savings.
That accusation hurt him.
Frank had actually helped them save money several times. When Madison chose imported tile that would have added nearly $4,000, he found a domestic alternative with a similar look. When an unexpected plumbing problem appeared behind a wall, he charged only the documented extra labor and materials.
I asked why he did not remind them of those favors.
He said, “Because favors aren’t invoices.”
That was Frank.
He did not want gratitude substituted for payment.
He wanted the contract followed.
The deadline passed without full payment.
Laura then prepared the next legally available step after confirming Frank had complied with the relevant notice and timing requirements. The claim identified the unpaid contract balance, not some inflated revenge figure. Interest and recoverable costs would be addressed separately under the contract and applicable law.
That was when Tyler’s mortgage lender became relevant. Tyler and Madison were planning to refinance the newly renovated property to consolidate other debts. A recorded lien claim could complicate clear title and delay that transaction until resolved.
Frank had no idea they were refinancing.
He learned only when their attorney called Laura.
Suddenly the $6,200 they considered optional stood between them and a much larger financial transaction.
Their lawyer proposed immediate payment of the principal if Frank waived all additional claims. Laura brought the offer to him. By then, documented attorney expenses and contractual interest had already begun accumulating.
Frank could have made the dispute expensive.
Instead, he made a practical counteroffer.
Pay the full $6,200.
Reimburse the specific filing and legal costs already incurred.
Frank would waive additional interest and release the claim promptly after cleared funds arrived.
Tyler refused.
He said paying legal costs would feel like “letting the contractor win.”
Their own attorney apparently told them this was not a competition.
Another week passed.
The refinance closing was postponed.
Then Madison called me, apparently believing I could persuade my grandfather.
“Your grandfather is holding our house hostage over sixty-two hundred dollars.”
I replied, “Did he finish the work?”
“Yes.”
“Did you sign that he finished it?”
Silence.
“Yes.”
“Then what exactly do you want me to persuade him to do?”
She hung up.
The next morning, their attorney emailed Laura.
They were ready to pay.
But before Frank signed the release, Laura discovered something strange.
Tyler had posted online that he planned to report Frank for “extortion” after the refinance closed.
Frank read the screenshot once.
Then he said, “Add one condition.”
Not extra money.
A written acknowledgment that the payment resolved a valid contract balance and was not made under any threat outside lawful collection procedures.
This time, Tyler signed.
The money arrived by wire two days later. The payment included the $6,200 balance and the documented costs Frank had incurred because collection became necessary. Laura confirmed the funds cleared, then promptly filed the documents required to release the property claim.
The refinance eventually closed.
Tyler and Madison kept their house.
Frank went back to work.
There was no auction.
No foreclosure.
No judge ordering them onto the street.
That was never what Frank wanted.
He had built homes for four decades. He understood better than most people that legal remedies exist to secure payment, not to create revenge stories.
Tyler still filed a complaint with the state licensing board.
He alleged Frank had used a lien threat to force payment for work they considered overpriced.
Frank responded with the signed contract, approved change orders, inspection records, completion certificate, photographs, correspondence, and the message where Tyler admitted the work had no defects.
The complaint was dismissed after review.
That should have been the end.
Instead, something unexpected happened.
A subcontractor named Miguel Alvarez called Frank after hearing about the dispute.
Tyler and Madison had hired Miguel separately for landscaping after Frank finished the renovation.
They owed him $2,400.
And they were now telling him the same thing.
“We’ve already spent enough.”
Frank did not tell Miguel to copy his strategy blindly.
He gave him Laura’s number.
Different contractor.
Different contract.
Different legal requirements.
Miguel needed his own advice.
But the pattern bothered me.
When I asked Frank why some people behaved that way, he shrugged.
“Because they think the last person waiting to be paid has the least leverage.”
Then he added, “That’s why paperwork matters.”
Miguel eventually resolved his own bill without litigation.
Months passed.
Frank completed three more renovations.
Then one afternoon, Tyler appeared at his workshop.
I happened to be there.
He looked embarrassed.
He said he needed advice.
His employer had delayed part of his annual bonus after changing compensation rules, and Tyler was furious because the company had promised something different in writing.
The irony was impossible to miss.
Frank did not laugh.
He asked, “Do you have the agreement?”
Tyler nodded.
“Then read it.”
They stood there for nearly twenty minutes reviewing it together.
Frank was not an employment lawyer, so he eventually told Tyler to take the document to someone qualified.
Before leaving, Tyler said, “I guess I understand why you were so stubborn.”
Frank shook his head.
“I wasn’t stubborn.”
He tapped the agreement.
“I expected both sides to mean what they signed.”
That sentence became the lesson I remembered.
People often describe contracts as evidence of distrust.
Frank saw them differently.
A good contract protects trust by recording what everyone agreed to while relationships are still friendly.
Price.
Scope.
Deadlines.
Responsibilities.
What happens if something goes wrong.
Memory changes when money becomes uncomfortable.
Paper does not.
Frank had no desire to surprise Tyler and Madison with page fourteen.
He had explained the payment provision before work began.
They simply stopped caring about it once the house was finished and all the bargaining power seemed to belong to them.
They were wrong.
Not because Frank had hidden a trap.
Because completing your side of an agreement does not erase the other person’s side.
A year later, Frank retired from full kitchen renovations.
His knees were tired, and climbing stairs had become harder.
At his retirement dinner, several former clients came.
One couple brought photographs of the nursery Frank had built twenty years earlier.
Another man said Frank had repaired his mother’s roof during a difficult winter and allowed her extra time to pay.
That was the part people like Tyler never understood.
Frank could be generous.
He often was.
But generosity was his decision.
Nobody became entitled to it by refusing a bill.
I still remember watching him walk away from that beautiful house without raising his voice.
At the time, I thought he was unusually calm.
Later, I understood.
He was calm because he had already done the important work months earlier.
He had written down the agreement.
Explained it.
Documented every change.
Finished what he promised.
And kept the signatures.
The $6,200 was never really the lesson.
The lesson was simpler:
Do good work.
Keep good records.
Know your rights.
And never mistake someone’s calmness for the absence of options.