“You’re not coming.”
My son said it casually, as if he were telling me the restaurant had changed our reservation.
I stared at the cruise documents spread across his kitchen island.
For eleven months, I had paid for a seven-night Caribbean cruise for Daniel, his wife Megan, their two children, and myself. Three balcony cabins had become four after Megan insisted the children needed more space. Excursions, airfare, gratuities, airport transfers—everything came from my card.
Then, three days before departure, Daniel slid my passport back toward me.
“Megan thinks this should just be family time.”
I almost laughed.
“I’m family.”
“You know what I mean.”
Megan walked in wearing the linen cover-up I had bought her for the trip. “It’s not personal, Carol. The kids are at an age where they need memories with just us.”
Their children, Ava and Mason, were nine and seven.
I had paid their private-school tuition for two years.
Their braces.
Summer camp.
Mason’s occupational therapy.
Half their groceries whenever Daniel said commissions were slow.
And the lakeside house where they lived every weekend and most school holidays?
Mine.
I had bought the Wisconsin property twelve years earlier through my family trust. Daniel called it “our lake house” so often that eventually everyone else did too. Three years ago, when they began spending most weekends there, my attorney drafted a renewable family-use agreement. No rent. No equity. No ownership. Either side could end access with thirty days’ written notice.
Daniel had signed it without reading past the first page.
He leaned against the counter. “Since you won’t be traveling, can you handle the kids’ school payment on Monday? And Ava’s camp deposit is due while we’re gone.”
I looked at him.
He had excluded me from a vacation I financed and was assigning me bills for children he was taking on that vacation.
I said nothing.
That frightened him less than anger would have.
The next morning, I called the cruise line. The fare was mostly nonrefundable, so I didn’t punish the children by canceling the trip. I removed my onboard card, canceled every excursion charged solely to me, and informed the line that Daniel would provide his own payment method for incidentals.
Then I called my bank.
Daniel and Megan were authorized users on two of my credit cards.
Not anymore.
I stopped the automatic tuition transfer, camp payment, streaming accounts, phone-plan reimbursement, and monthly grocery allowance.
Then I called my attorney, Rebecca Shaw.
“Send the thirty-day termination notice for the lake house,” I said. “And list it.”
There was a pause.
“You’re certain?”
“Yes.”
Thirty-two days later, while Daniel’s family was still traveling after extending their trip in Miami, we accepted a cash offer.
The closing happened the morning they flew home.
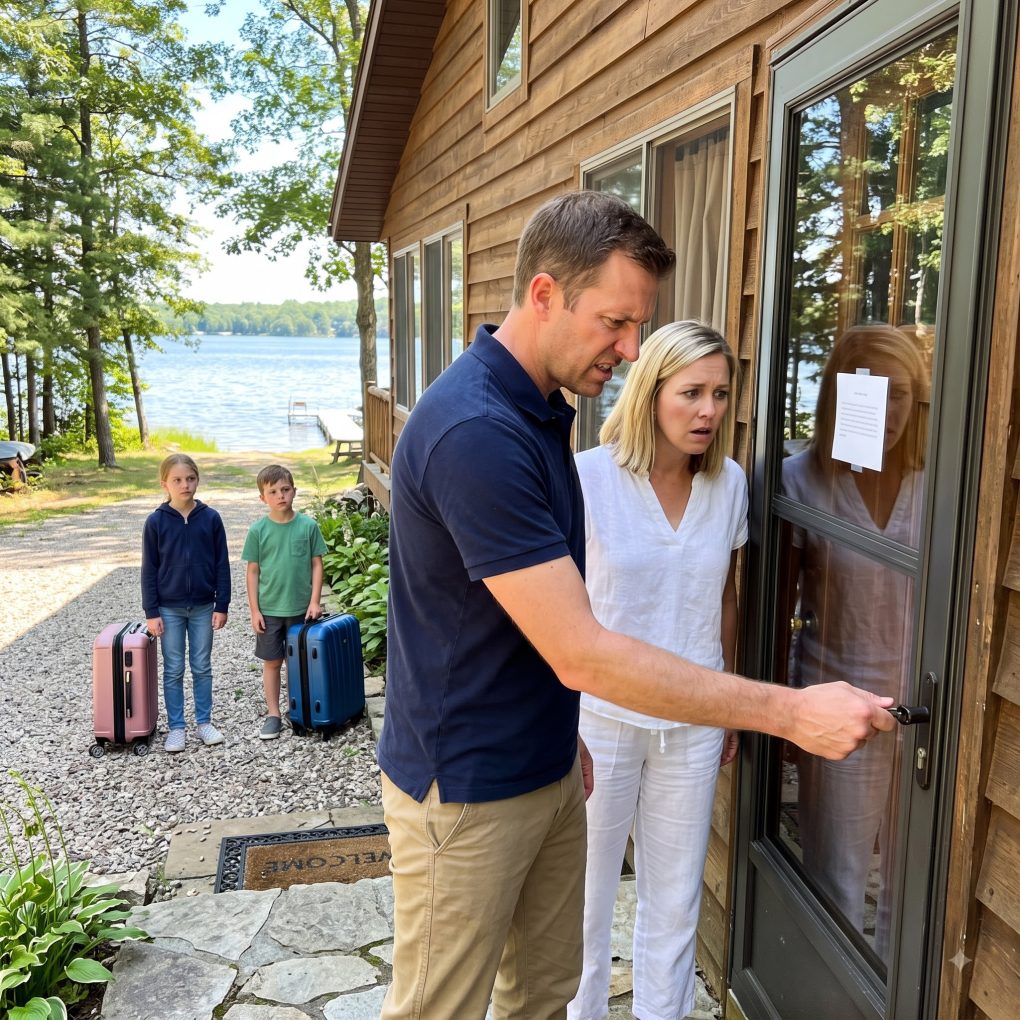
At 6:14 p.m., Daniel called me from the lake house screaming.
“Our key doesn’t work!”
I looked at the photo Rebecca had just sent me of the notice taped inside the glass storm door.
“Read what’s on the door,” I said.
Then the line went silent.
They thought losing a few credit cards was the worst surprise waiting for them. By the time Daniel read the notice on that door, he was about to discover that the house was only the beginning.
The silence lasted five seconds.
Then Daniel read the note aloud.
“Effective today, title to 1187 Pinewater Road has transferred to Thomas and Ellen Brooks. The prior family-use agreement expired after written notice. Personal property has been inventoried and placed in secured storage pursuant to Section Eight.”
His voice rose.
“Who are Thomas and Ellen Brooks?”
“The people who bought my house.”
Megan shouted something behind him.
Daniel came back furious. “You sold our home while we were on vacation?”
“No. I sold my lake property after your right to use it ended.”
“You can’t do that!”
Rebecca had expected that reaction.
Thirty days earlier, the termination notice had been delivered by certified mail to Daniel’s primary residence in Milwaukee, emailed to both him and Megan, and sent through the property portal they used for maintenance requests. Daniel electronically acknowledged the portal message from the cruise ship.
He had never opened the attachment.
That was not my problem.
Their primary residence was a townhouse in Milwaukee that Daniel owned with Megan. The lake house had always been a second home they used rent-free. Their furniture, clothes, kayaks, and toys had been packed by a licensed moving company and transferred to climate-controlled storage at my expense.
Nothing had been thrown away.
Nothing had been taken from them.
Only the assumption that it belonged to them had ended.
Then Megan grabbed the phone.
“What about the children? Ava has riding lessons. Mason’s school payment bounced. You know we budget around what you cover.”
“I know.”
“You promised to help.”
“I promised when help still meant help.”
She called me selfish.
Then she said something strange.
“Daniel told you we couldn’t afford this trip without you.”
I sat up.
“What?”
Silence.
Daniel snatched the phone back. “She’s upset.”
“Daniel, I paid for the cruise. Why would I need to be told you couldn’t afford it?”
He hung up.
That evening, Rebecca called.
“We found something during the sale closing,” she said. “Your son has been using the lake address on financial documents.”
“For what?”
“A business credit application.”
Daniel worked in commercial real estate. Six months earlier, he had formed an LLC to buy distressed properties. On the application, he listed Pinewater Road as real estate he personally owned, with an estimated value of $1.4 million.
I felt my stomach tighten.
“He claimed my house was his collateral?”
“Not formally pledged. But he represented it as part of his net worth.”
Then Rebecca sent me the application.
Under OWNER, Daniel had written his name.
Under ACQUISITION, he had written: FAMILY TRANSFER.
No such transfer had ever happened.
There was more.
Attached to the application was a projected inheritance statement claiming I had already committed the lake property to him in my estate plan.
I hadn’t.
Rebecca said, “Carol, I need you to look at the signature on page nine.”
At the bottom was a typed certification stating that the information had been verified with the property owner.
Beside it was my name.
CAROL BENNETT.
And underneath it was an electronic signature I had never made.
The signature was a copy of mine from an insurance form.
Daniel had scanned a document I signed years earlier and pasted the image into the lender’s certification page.
Rebecca notified the lender immediately.
By noon the next day, Daniel’s business credit application was suspended.
That was when he finally came to my house.
He stood on my porch looking exhausted.
“You’re destroying everything over a cruise.”
I handed him a copy of page nine.
His face changed.
“That has nothing to do with the cruise.”
“It has everything to do with why you thought you could exclude me and still hand me your bills.”
He stared at the signature.
Then the rest came out.
Daniel’s new real-estate company was struggling. To attract an investor, he had exaggerated his personal assets and described the lake house as an early inheritance. During the cruise, he planned to spend two days entertaining that investor, who was traveling on the same ship.
That was why I had been removed.
Megan thought an older mother tagging along would make Daniel look less independent.
Yet they still expected that same mother to pay the children’s tuition while Daniel presented himself as a wealthy property owner.
“You could have asked me for help,” I said.
“I knew you’d ask questions.”
He said it quietly.
That sentence ended the argument.
Questions were exactly what my money had allowed them to avoid.
The lender conducted its own review. Because the loan had not been funded, there was no mortgage or lien against my former property, but Daniel’s application was rejected for material misrepresentation. His prospective investor walked away after receiving updated financial disclosures.
Rebecca advised me that I could pursue additional claims over the copied signature.
I chose not to start a lawsuit.
Instead, Daniel signed a written acknowledgment that he had no interest in my remaining property and no authority to use my name, assets, or anticipated inheritance in financial applications.
The sale of Pinewater Road remained final.
Thomas and Ellen Brooks were a retired teacher and nurse from Madison. They had toured the property twice while Daniel’s family was away and bought it with cash. They knew nothing about our dispute beyond what their attorney needed to know.
The note on their door had been factual:
THIS PROPERTY IS NOW OWNED BY THOMAS AND ELLEN BROOKS. ALL PRIOR ACCESS RIGHTS HAVE ENDED. CONTACT BENNETT & SHAW REGARDING STORED PERSONAL PROPERTY.
Daniel hated that note because it said in four lines what I had failed to say for years.
Paying for something did not make me obligated to keep paying forever.
Ava and Mason were never punished for their parents’ choices. I opened education accounts in their names that only I controlled. Birthdays continued. So did visits.
What stopped were automatic rescues.
Daniel and Megan refinanced their Milwaukee townhouse, cut expenses, and moved the children to a school they could afford themselves.
Months later, Daniel apologized.
Not because he lost the lake house.
Because he finally admitted he had begun treating my generosity like part of his salary.
I accepted the apology.
I did not give him another card.
The lake house had been beautiful.
But selling it bought me something I had needed far longer than waterfront property.
A boundary nobody could mistake for an invitation.