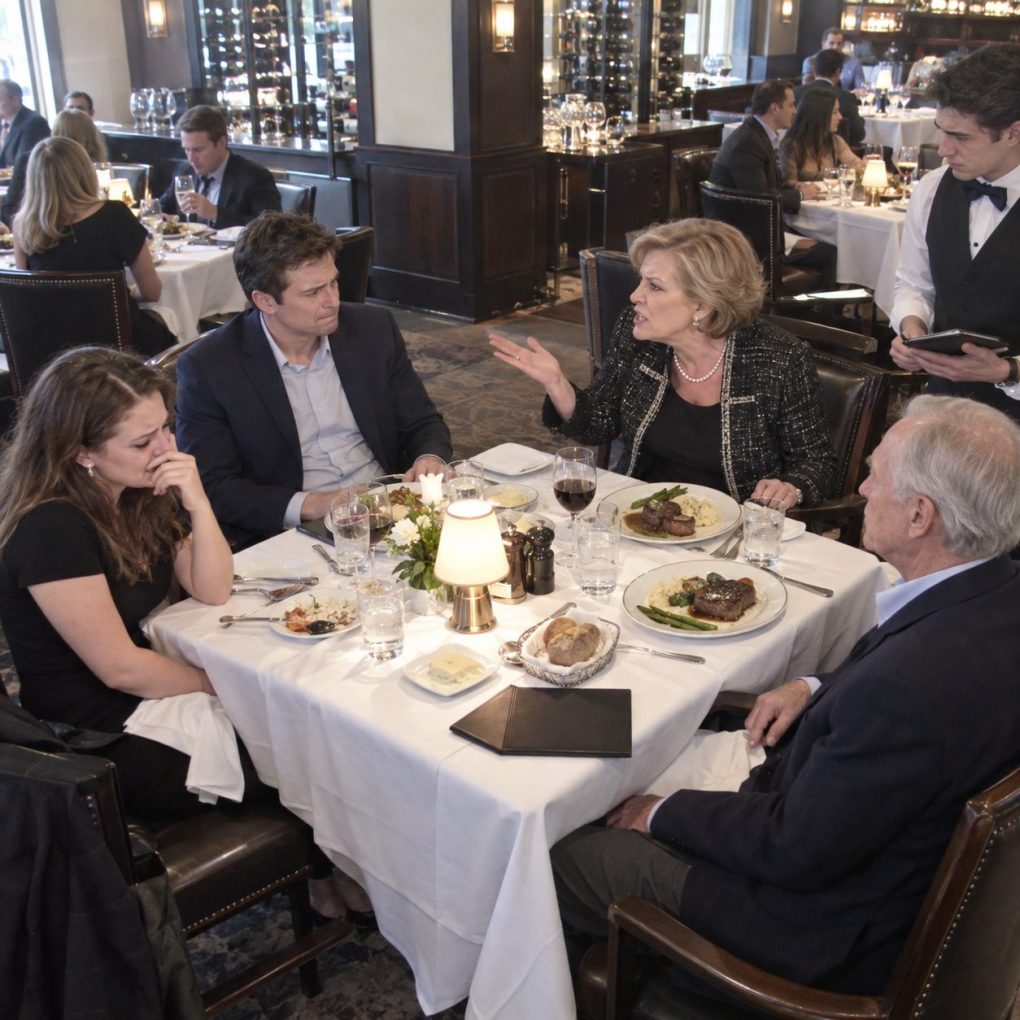
“Separate his bill. He’s not our responsibility,” my mother-in-law said loudly enough for the tables beside us to hear. Diane Mercer pointed across the restaurant at my father, Robert, while my husband Evan gave the waiter a small nod, as though publicly separating my seventy-one-year-old dad from the family was the most reasonable thing in the world.
Dad did not argue. He wore an old navy blazer, ordered the least expensive entrée on the menu, and simply touched my wrist when I started to defend him. “Claire, eat before it gets cold,” he said quietly, while Diane smiled and began explaining that successful families stayed successful because they did not “carry people who should be paying their own way.”
What made the humiliation almost unbearable was that Dad had never asked the Mercers for a cent. Eighteen months earlier, when Mercer Development nearly lost its credit line after two expensive projects stalled, Dad had used his reputation and personal assets to guarantee part of a $1.6 million refinancing agreement, because Evan had sat in our kitchen begging him to help save the company his grandfather had started.
Diane knew exactly what he had done. Yet as she ordered another bottle of wine, she joked that retirement must be “tight on a teacher’s pension,” apparently forgetting that Dad had spent years after teaching building a modest commercial-property portfolio and serving on the advisory board of the very bank keeping her family company alive.
When the checks arrived, the waiter placed one small folder in front of Dad and another beside Evan. Diane leaned back with a satisfied expression, but Dad calmly paid for his salmon and coffee, signed the receipt, then folded his glasses and slipped them into his pocket.
Before leaving, he looked directly at Evan. “You’re right about one thing,” he said. “A man shouldn’t be responsible for debts that belong to someone else.”
Evan stopped breathing for half a second.
Dad continued, still perfectly calm. “So tomorrow morning, my attorney will notify First Commonwealth that I will not renew my personal guarantee when the current term expires.”
Diane’s wineglass froze halfway to her mouth. Evan pushed his chair back so quickly it struck the wall behind him and whispered, “Robert, please. You don’t understand what that will do.”
Dad looked at him for a long moment. “Actually, son,” he said, “I understand exactly what I’ve been paying to protect.”
Then he turned toward me.
“And Claire,” he added softly, “I think it’s time you found out what else you’ve been paying for.”
The moment Dad walked out, Evan stopped pretending the dinner had been about principle. He grabbed his phone, called his brother Grant, and hissed, “Dad’s pulling the guarantee,” while Diane demanded that I chase my father into the parking lot and make him “stop acting vindictive before he ruins hundreds of people.”
I refused. On the drive home, Evan told me Mercer Development would probably survive, but the bank could demand additional collateral, raise the interest rate, or require a major cash injection before renewing the company’s credit line. Then he said something that made my stomach tighten: “We have more exposure than you realize.”
At home, I made him explain. Eighteen months earlier, I had agreed to let Evan invest $25,000 of our joint savings in the company during what he described as a temporary cash-flow problem, but the banking records showed repeated transfers after that—$12,000, then $18,000, then $31,000, then smaller amounts scattered across nearly a year.
The total was $96,400.
“You told me we were rebuilding that account,” I said, staring at the screen. Evan rubbed both hands over his face and insisted the money had not disappeared; it was sitting inside the company and would eventually come back. That was when I noticed another document attached to the refinancing file, and the address printed on it was ours.
Our house had been listed as secondary collateral for a separate company obligation.
My signature appeared at the bottom.
I knew immediately that I had never signed that page.
Evan went pale before he said a word, which told me more than any confession could have. Finally, he admitted that several months earlier, during a refinancing deadline, he had electronically submitted a signature authorization using documents I had previously signed for another purpose, convincing himself he would correct everything once the company recovered.
I did not scream. I think that frightened him more.
The next morning, Dad sat across from me at his kitchen table while I showed him every document. He did not say, “I warned you,” and he did not call Evan a thief; he only asked me whether I understood that saving a marriage and protecting myself were no longer the same thing.
Later that afternoon, Diane arrived carrying flowers and suddenly calling my father “Robert” instead of “your dad.” She apologized for the restaurant, but within two minutes she was begging me to convince him to extend the guarantee for six more months.
I asked her one question.
“If he had been poor, would you still be standing here apologizing?”
Diane stared at me, unable to answer.
That night I packed a suitcase. Evan followed me upstairs, crying now, saying he could fix the company, restore the savings, replace the collateral, fix everything.
I closed the suitcase and finally looked at him.
“You still don’t understand,” I said. “The company isn’t the thing you broke.”
Then I went to Dad’s house with one question left to answer: whether the signature on that document had only endangered my home—or whether it had crossed a line that would end my marriage for good.
The next morning, I met with an attorney Dad trusted, and she confirmed what I already suspected: using my prior authorization to execute a new collateral agreement without my knowledge was serious. She advised me not to make accusations until the bank reviewed its records, but she immediately sent written notice disputing my consent and instructed me to separate my finances from Evan’s until the matter was resolved.
First Commonwealth froze any attempt to rely on our home as additional collateral while it investigated the documentation. Dad’s existing guarantee remained in force until its contractual expiration date, which meant Mercer Development did not collapse overnight, but the family suddenly had a deadline they could no longer avoid.
For the first time in years, the Mercers had to solve their own problem.
Grant sold two unused company vehicles and canceled a speculative land purchase. Diane gave up the luxury SUV the business had been leasing for her, and the brothers put a lake property owned by the company on the market to reduce debt before the bank reviewed the credit line.
Evan moved into a furnished apartment after I asked him to leave. He gave my attorney complete access to our accounts, admitted in writing that I had not knowingly authorized the collateral document, and cooperated with the bank rather than trying to protect himself by claiming I had simply forgotten.
That mattered, but it did not erase what he had done.
Diane reacted differently. She told relatives Dad had destroyed her family over “one restaurant misunderstanding,” until Grant finally confronted her during a company meeting and said the sentence everyone should have said years earlier: “Robert didn’t create this problem. We created a company that only looked strong because somebody else kept standing underneath it.”
The bank eventually removed our house from the collateral package. Mercer Development secured replacement financing through a local investor, but at a painful cost: tighter oversight, higher interest, and no more personal spending disguised as business expenses.
Dad never asked for revenge. He simply declined to renew his guarantee when the agreement expired.
Six months after the dinner, Evan asked me to meet him at the same restaurant. He chose the exact table where Diane had humiliated my father, but this time there were only two place settings.
He placed a folder between us containing proof that the final $96,400 had been restored to our marital account through the sale of his boat, his company bonus, and distributions he would normally have kept. Then he pushed the folder aside without asking me to open it.
“I used to think repayment meant making the numbers right,” he said. “But I can repay money. I can’t repay the moment you realized your husband was willing to risk your home without asking you.”
For the first time since I left, I believed he understood the difference.
I did not move home that night. We spent almost a year in counseling, and Evan had to rebuild trust through hundreds of ordinary decisions rather than one dramatic apology: showing me statements before I asked, refusing to let his mother insult me, admitting when he was afraid instead of hiding problems until they became emergencies.
Eventually, I chose to stay married, but the old marriage ended permanently.
We kept separate personal savings alongside one shared household account. Any investment above an agreed amount required both signatures, and Diane no longer had unlimited access to our home, our holidays, or our decisions simply because she was Evan’s mother.
She never apologized to Dad in the way I wished she would. At family gatherings, however, she became remarkably careful about who was “responsible” for whom.
A year later, Dad and I returned to that restaurant for his birthday. When the waiter brought the check, I reached for it first, but Dad laughed and pulled it toward himself.
“Separate bills?” he asked.
I smiled. “Not a chance.”
Dad paid anyway.
As we walked outside, I finally understood why he had remained so calm that first night. He had never cared about the price of his salmon, and he had never needed Diane to believe he could afford dinner.
He needed me to see something I had spent years refusing to see.
My father had guaranteed a company because he loved me. I had tolerated disrespect because I thought that was love too.
Only one of us had understood the difference.
And in the end, the most expensive thing on that table was never the bill.
It was the silence I had been paying for all along.