My daughter-in-law called and told me my card had been blocked. Then she said I needed to run my spending by them first. I didn’t argue. I drove straight to the bank. Two hours later, I had 38 missed calls.
My daughter-in-law called me at 9:17 on a Tuesday morning while I was standing at the grocery store checkout.
“Your card is blocked,” Rachel said.
I stared at the terminal where DECLINED flashed across the screen.
“What?”
“We froze it last night.”
I stepped away from the register. “You froze my credit card?”
Then she said something I would remember for a very long time.
“Run your spending by us first. It’ll be easier for everyone.”
Us.
She meant herself and my son, Andrew.
I was sixty-six years old. The money in my accounts came from thirty-eight years of work, my late husband’s life insurance, and investments we had built together. But six months earlier, after I underwent a minor surgery, I had added Andrew as an authorized contact on several accounts in case of an emergency.
Apparently, Rachel had decided emergency access meant financial authority.
“Why was my card blocked?” I asked.
“You’ve been spending too much.”
I looked at the groceries in my cart.
Milk. Chicken. Coffee. Laundry detergent.
“How much is too much?”
Rachel sighed like I was a difficult child.
“Just call us before making purchases. Andrew agrees.”
I didn’t argue.
“Okay,” I said.
Her voice softened immediately. “Good. I’m glad you’re being reasonable.”
I hung up, left the groceries, and drove directly to First National Bank.
Twenty minutes later, I was sitting across from branch manager Thomas Reed.
“I want to know exactly who has access to my accounts.”
He pulled up my profile.
His expression changed.
“Mrs. Parker, your son is listed as an authorized user on one checking account and emergency contact on two others.”
“Can he freeze my card?”
“Not independently.”
My stomach tightened.
“Then who did?”
Thomas checked.
The freeze had been requested through the joint household account I had created years earlier to help Andrew with emergencies. My primary card had somehow been linked as a backup payment source.
I felt suddenly cold.
“Remove every connection.”
“Every one?”
“Every one.”
We closed the shared account, removed Andrew’s authorization, issued new cards, changed security credentials, and moved my savings into a new account accessible only by me.
Then Thomas showed me something else.
Several automatic payments connected to Andrew and Rachel’s household had been drawing from the shared account.
Their phone plan.
Their car insurance.
A streaming bundle.
And a monthly payment on Rachel’s SUV.
I hadn’t noticed because the amounts disappeared among dozens of routine transactions.
“Cancel all of them,” I said.
Two hours later, I walked out of the bank and turned my phone back on.
Thirty-eight missed calls.
Twenty-one from Andrew.
Seventeen from Rachel.
Then one text appeared.
Mom, what did you do?
I smiled.
For the first time that morning, my card wasn’t the one being declined.
I hadn’t even reached my car when Andrew called again. This time, I answered. “Mom, what happened at the bank?” There was panic in his voice, not concern. “I corrected my accounts.” “What does that mean?” “Exactly what it sounds like.” Rachel’s voice exploded somewhere behind him. “Ask her why our payments are declining!” I leaned against my car. “Because I’m no longer paying them.” Silence. Then Andrew said, “Mom, you can’t just do that.” I almost laughed. Two hours earlier, his wife had told me I needed permission to buy groceries with my own money. Now my son was telling me I couldn’t stop paying his bills with that same money. “Actually,” I said, “the bank says I can.”
Rachel grabbed the phone. “That money was already allocated!” “By whom?” “We have a system.” “Apparently I wasn’t informed about it.” “Andrew told you.” “No, Andrew asked me years ago if we could use the shared account for emergencies.” Her voice sharpened. “Things changed.” “Yes,” I said. “They certainly did.” I opened my car door but didn’t get inside. “Rachel, when exactly did my generosity become part of your household budget?” She didn’t answer the question. Instead, she accused me of trying to punish them because they were protecting me from irresponsible spending. That was when I finally understood how they had justified everything to themselves. I wasn’t the owner of the money anymore. I was the elderly woman who needed supervision. The fact that nobody had bothered telling me I needed supervision was apparently irrelevant.
Andrew took the phone back. “Mom, nobody thinks you’re incompetent.” “Then why did Rachel tell me to ask permission before spending?” “She worded it badly.” “And freezing my card?” “That was supposed to be temporary.” “Until what?” He hesitated. “Until we talked.” “You mean until I agreed.” He went quiet. That silence answered me. I drove home and spent the afternoon reviewing two years of statements. The deeper I looked, the worse it became. The SUV payment had started eight months earlier. Their cell phone plan had been attached for almost a year. There were utility charges, insurance premiums, and several online subscriptions I had never authorized. Individually, nothing was enormous. Together, they totaled thousands of dollars.
That evening Andrew arrived at my house alone. I let him inside. He looked exhausted. “Rachel’s furious.” “I’m sure.” “Her car payment bounced.” “It’s her car.” He sat across from me. “We were going to pay you back eventually.” “For what?” His face changed. That question forced him to admit something neither of them had ever said aloud: they knew the money was mine. They simply assumed I wouldn’t notice or wouldn’t object. “How much have you taken from that account?” I asked. “Taken is a strong word.” “Then give me a better one.” He couldn’t.
I pushed a folder across the table. Inside were printed statements with every questionable charge highlighted. Andrew turned the pages slowly. His face became paler with each one. “Mom, I didn’t know about some of these.” “Which ones?” He pointed at Rachel’s SUV and several household payments. My anger shifted. “You’re telling me Rachel added these without telling you?” “I think so.” Then his phone rang. Rachel. He answered on speaker. She was screaming before he said hello. “Tell your mother to restore the account right now!” Andrew looked at me, then at the highlighted statements. For once, he didn’t immediately defend her. “Rachel,” he said quietly, “how long has your car been coming out of Mom’s account?” The line went completely silent.
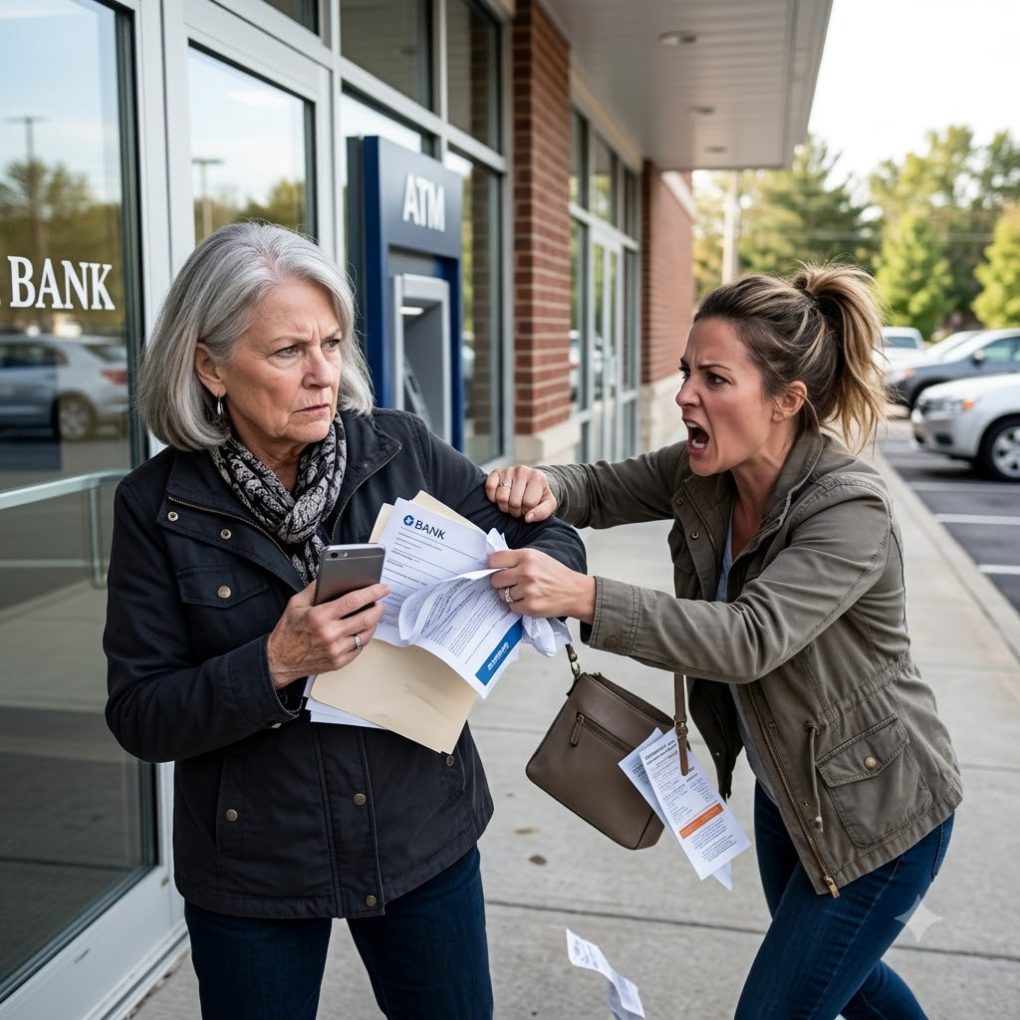
Rachel arrived at my house forty minutes later. She didn’t knock politely. She pounded on the front door until Andrew opened it. “What are you doing?” she demanded, looking from him to me. Andrew held up the bank statements. “I’m trying to understand this.” Her expression changed for half a second. That was enough. “You knew,” I said. Rachel immediately became defensive. She claimed the payments were temporary, that Andrew had been struggling, that I had more savings than I needed, and that family members were supposed to help each other. I listened until she finally ran out of excuses. Then I asked, “Why didn’t you ask me?” She crossed her arms. “Because you would’ve said no.” The room became completely still. Andrew stared at his wife. Rachel seemed to realize what she had admitted, but it was too late.
“So you knew I hadn’t agreed,” I said. “You just decided my answer didn’t matter.” She tried changing the subject. “You spend hundreds of dollars on things you don’t need.” “My money.” “We’re trying to protect your future.” “By using it to pay for your SUV?” Andrew closed his eyes. Rachel turned toward him. “Don’t stand there acting innocent. You benefited too.” He nodded slowly. “I know.” That surprised both of us. Then he looked at me. “She’s right about that part. Even if I didn’t know about everything, I knew Mom was covering too much. I let it happen.” It wasn’t a perfect apology, but it was the first honest sentence either of them had spoken all day.
I told them the shared account would remain closed permanently. They would receive no access to my new accounts, cards, passwords, or financial documents. If Andrew wanted to be my emergency contact in the future, we would arrange it properly with an attorney so emergency authority couldn’t become casual access. Rachel started protesting again. “So you’re cutting us off?” “I’m stopping automatic payments. That’s not the same thing.” “What are we supposed to do?” “Pay your bills.” She stared at me as if the idea were outrageous. Then she said, “You’re going to destroy our finances.” I looked at the folder. “No. I’m simply no longer financing them.”
The following weeks were uncomfortable. Rachel barely spoke to me. Andrew called several times, mostly to apologize and explain that they were downsizing expenses. Rachel sold the SUV three months later and bought a used sedan they could afford. They canceled subscriptions, changed phone plans, and finally created an actual household budget. I didn’t enjoy watching them struggle, but I refused to rescue them from consequences created by treating my money as theirs.
Six months later, Andrew invited me to lunch. Rachel came too. She looked nervous. Halfway through the meal, she placed an envelope beside my plate. Inside was a check. It wasn’t enough to cover everything they had used, but it was the first installment. “I owe you more than this,” she said. “I know.” She swallowed. “And I shouldn’t have blocked your card.” “No.” “Or told you how to spend your own money.” “No.” Then she surprised me. “I think I started believing that because we helped you after surgery, we had the right to manage things.” I nodded. “Helping someone isn’t ownership.”
Things between us improved slowly after that. Trust didn’t return because of one apology or one check. It came back in small pieces. Andrew stopped asking about my balances. Rachel stopped commenting on what I purchased. I hired an independent financial adviser and updated my estate documents so nobody could misunderstand their authority again.
Sometimes I still think about those thirty-eight missed calls. At the time, everyone believed the dramatic part was what I had done at the bank. It wasn’t. The dramatic part was how quickly people panicked when they lost access to something that had never belonged to them. Rachel had told me to run my spending by them first. Two hours later, she learned the rule that should have existed from the beginning: nobody gets to control another adult’s money simply because they became comfortable spending it.