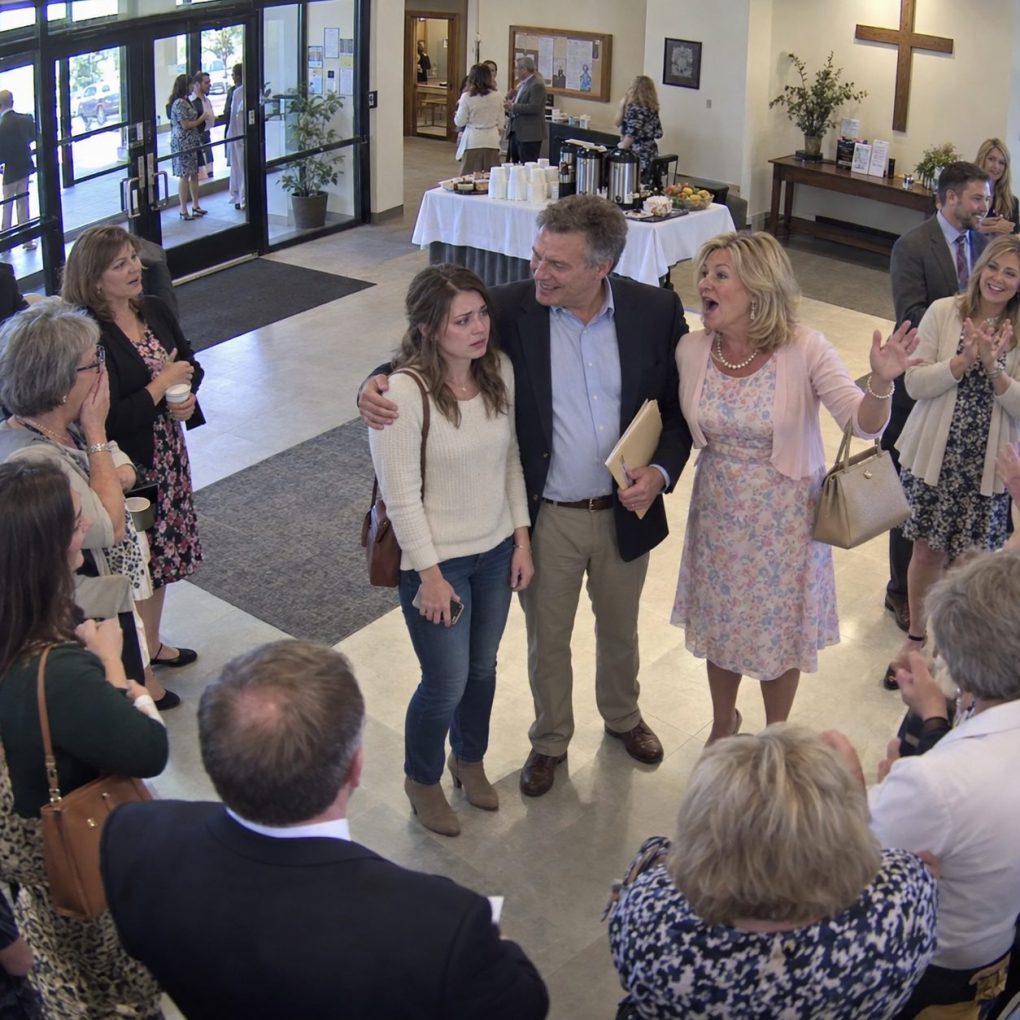
My mother told seventy people at church that I had given my parents $200,000 before she bothered telling me. She stood beside my father after Sunday service, glowing with pride, and announced that their daughter had helped finance Willow Creek Celebrations, the event venue they had dreamed about opening for years.
Everyone applauded. Dad wrapped an arm around my shoulders and said, “Rachel always takes care of her family,” while I stared at him and wondered whether he knew that my phone had alerted me three days earlier to a new commercial loan opened under my name—one I had never applied for, authorized, or signed.
I did not expose them in church. I smiled, accepted congratulations, and even let Mom tell a woman beside us that I had personally insisted they “finally chase their dream,” because by then I had already met with an attorney, frozen my credit, filed an identity-theft report, and sent the lender written notice disputing the debt.
What my parents did not know was that I worked in corporate risk management, so anger was never my first move when something looked fraudulent. Documentation was.
The loan application contained my income, my Social Security number, and an electronic signature that looked convincing enough to pass an initial review. It also listed my condo as evidence of financial strength, which explained why Dad had spent the previous month casually asking whether I still owned it outright.
My attorney, Daniel Mercer, discovered one important detail: the loan had been approved and partially funded, but my parents had not yet signed the three-year commercial lease for Willow Creek. Without that lease, most of their grand plans could still disappear with relatively little damage.
Daniel asked whether I wanted him to contact the landlord immediately.
I looked at the draft lease my mother had proudly emailed me, especially the sections requiring the tenants to personally guarantee rent, renovations, permits, insurance, and operating costs regardless of whether their financing remained available.
“Not yet,” I said.
Four days later, my parents signed.
Dad sent me a photograph of himself holding the keys beneath a giant COMING SOON banner. Beneath it, he wrote, We finally did it. Thank you for believing in us.
I stared at that message for several seconds before forwarding it to Daniel.
The following morning, the lender froze the remaining funds.
By noon, two contractors had stopped work, the landlord was demanding proof of financing, and Mom finally called me screaming, “Rachel, what did you do?”
I looked at the copy of their signed lease sitting beside me and answered quietly.
“Nothing. I just stopped letting you do it in my name.”
Dad took the phone from my mother and immediately changed his voice. The rage disappeared, replaced by the soft, disappointed tone he had used my entire childhood whenever he wanted me to feel guilty for having boundaries.
“We weren’t stealing from you,” he said. “We were building something for all of us.”
Daniel was sitting across from me, listening on speakerphone. When Dad added that they had only “borrowed my credit until the business became profitable,” Daniel slowly wrote the sentence down and circled it twice.
The lender’s fraud department moved quickly. Investigators found that my electronic signature had been submitted from an account I did not control, my tax information had been used without authorization, and the personal guarantee attached to the loan made me responsible for money I had never agreed to borrow.
But my parents had already spent nearly $63,000.
There was the lease deposit, demolition work, kitchen equipment, a custom bar, design fees, signage, and furniture orders they could no longer fully cancel. The remaining loan money was frozen, yet every obligation they had personally signed continued moving toward its due date.
That was the reason I had waited.
If I had confronted them before they signed, Dad would have spent the rest of his life telling relatives that I destroyed a successful business before it had a chance. Now the financing problem belonged to the people who created it, while my name was being removed from the debt through a documented fraud investigation.
Mom understood before Dad did.
“You knew we were going to sign that lease,” she whispered during our first meeting with Daniel. “You let us.”
I looked at her. “You knew I hadn’t agreed to the loan.”
Her eyes dropped.
For the first time, the room became completely silent.
The next week, church volunteers stopped showing up after rumors spread that I had never funded the business. Contractors demanded payment, vendors suspended deliveries, and the landlord’s attorney sent my parents a formal notice reminding them that financing failure did not automatically cancel their lease obligations.
I thought that was the worst of it until Daniel called me into his office on Friday afternoon.
He placed another document on the desk.
It was not part of the loan application.
It was a separate financial statement my father had submitted to strengthen the lease package, listing assets he claimed the family could use if the business failed.
My name appeared again.
So did the address of my condo.
I stared at Daniel. “He already used that for the loan.”
Daniel shook his head.
“Rachel, this is different. Your father told the landlord he had an ownership interest in your condo.”
Then he turned the page.
Attached behind it was a document carrying what appeared to be my notarized signature.
I knew the signature was fake before Daniel finished turning the page. I had never given my father an ownership interest in my condo, never pledged it toward Willow Creek, and certainly never appeared before the notary whose stamp sat beneath my forged name.
That document changed the situation immediately. The original loan dispute had already looked like identity theft, but now there was a separate document presented to a landlord suggesting my father had tried to make property he did not own look available to support his obligations.
Daniel contacted the landlord’s attorney and investigators the same day. A review of the notarization raised more questions, and once my father realized the document had been discovered, his confidence finally disappeared.
His explanation was almost insulting.
He said he had never intended to take my condo. According to him, he had simply needed the landlord to believe the family had enough assets behind the business, and because I would eventually inherit whatever my parents owned, he considered the distinction “technical.”
“You listed my home as if it belonged to you,” I said.
Dad slammed his palm against the table. “Because I knew you’d never let us lose everything.”
That sentence was the entire problem.
For years, my parents had treated my stability as their emergency fund. I paid small bills, covered family trips when someone was short, helped with repairs, and solved problems because I loved them, until somewhere along the way they stopped seeing my help as generosity and started seeing it as access.
The lender ultimately removed me from liability after confirming that I had not authorized the loan. The fraudulent account was corrected through the appropriate reporting process, while investigators continued pursuing the false documents and unauthorized use of my identity.
My parents were not so lucky.
The bank pursued the money already disbursed, vendors demanded payment for completed work, and the landlord enforced the obligations my parents had actually signed. Rather than spend years fighting over an empty venue, both sides eventually negotiated an early termination, but my parents lost their deposit, paid substantial settlement costs, and sold assets to cover debts tied to a business that never hosted a single event.
The criminal and regulatory issues took longer. I provided every email, text, credit alert, document, and church announcement I had preserved, including Dad’s message thanking me for “believing in us” after signing a lease he knew I had never agreed to finance.
Mom asked me one last time to tell investigators it had been a misunderstanding.
She was crying when she said, “He’s still your father.”
“I know,” I answered. “That’s why he knew I would trust him with information I would never give a stranger.”
Neither of us had anything left to say after that.
Months later, Willow Creek’s wooden sign appeared on Facebook Marketplace. Someone from church sent me the listing, and for a moment I stared at the photograph of those elegant white letters lying against a garage wall, remembering how proudly my parents had stood beneath them.
I felt no satisfaction.
What I felt was relief.
My parents had believed the forged loan made me responsible for saving their dream. Waiting until they signed the lease had done something arguing never could: it separated my identity from their choices so clearly that even they could no longer pretend the consequences belonged to me.
We eventually spoke again, but our relationship changed permanently. I locked down every financial account, replaced compromised documents, and made one boundary painfully simple: love did not give anyone permission to sign my name.
People still ask why I waited.
Because before the lease, my parents could have blamed me for the dream they never got to chase.
After the lease, the signatures that mattered were finally theirs.
They had spent years believing I would always rescue them from the consequences of their decisions.
The most expensive lesson they ever learned was that this time—
I let their choices belong to them.