“Buy your own,” my in-laws laughed when my little boy asked to borrow a tent. This from the same people who had spent years enjoying my $60,000 pool like they owned it. A few days later, they threw another party without permission and left me with thousands in damage. I stayed completely calm, because the next morning they were about to discover how many of their monthly expenses had my name behind them.
My name is Claire Morgan, and my husband, Daniel, had spent years calling my generosity “family support.”
His parents, Patricia and Robert, lived ten minutes away in a house they could barely afford after Robert retired early.
I paid their lawn service.
Their premium cable package.
Part of their homeowners insurance.
Their country-club social membership.
And, because Daniel insisted it was easier, I had also been covering the insurance and maintenance on Robert’s truck.
None of those things were necessities.
They started as temporary help.
They became permanent because nobody ever asked when temporary ended.
My eight-year-old son, Ethan, understood none of that.
He simply knew Grandma and Grandpa owned a large camping tent they used twice a year.
When he asked whether he could borrow it for a backyard campout, Patricia laughed.
“Buy your own.”
Robert added, “Kids need to learn they can’t expect other people’s things.”
Daniel smiled awkwardly.
I said nothing.
Ethan looked embarrassed.
Three days later, Daniel and I attended a wedding in Richmond.
I had specifically told his parents not to use our house because the pool deck was being resealed and the contractor had warned us to keep heavy furniture off it for forty-eight hours.
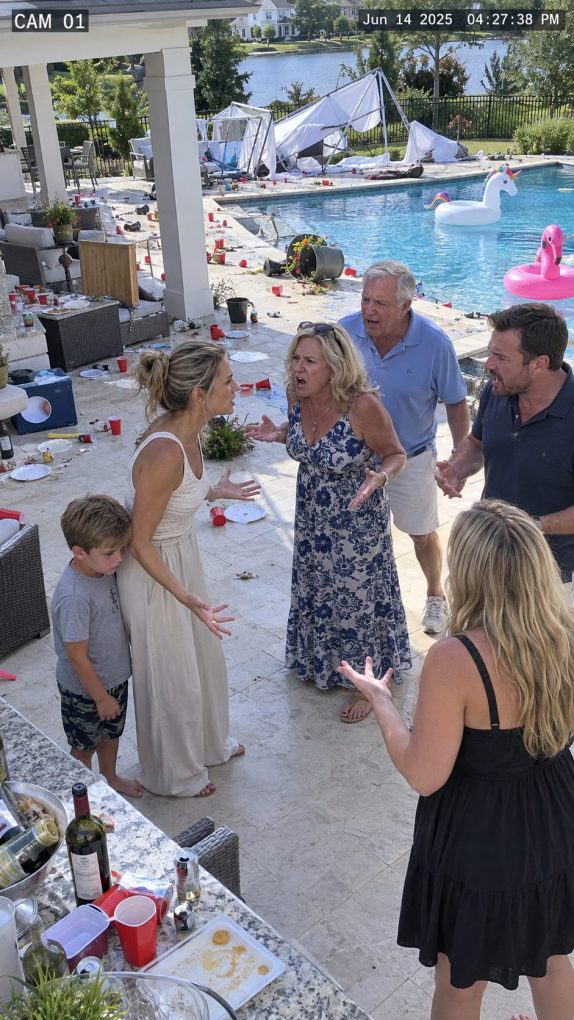
At 6:12 p.m., my security camera sent an alert.
Thirty people were in my backyard.
Music.
Coolers.
Children jumping into the pool.
Patricia had invited relatives over for Robert’s birthday.
Without asking.
By the time we returned the next morning, two lounge chairs were broken, wine had stained the new stone, a section of railing was loose, and someone had dragged a metal table across the freshly sealed deck.
The contractor estimated $4,800 in repairs and rework.
Patricia shrugged when I called.
“It was a family party.”
Robert said, “You can afford it.”
Daniel asked me not to overreact.
So I didn’t.
I photographed everything.
Saved the security footage.
Got the contractor’s written estimate.
Then I opened our household accounts.
Patricia and Robert’s monthly expenses were scattered across seven automatic payments.
Total: $2,740.
Every month.
Almost all charged to accounts in my name.
I canceled none of their essential utilities.
I simply removed my payment methods from expenses I had voluntarily been covering.
Then I sent one message:
Beginning tomorrow, please arrange payment for your own discretionary expenses.
At 8:07 the next morning, Patricia called.
Her club payment had failed.
At 8:16, Robert discovered his truck-insurance autopay needed a new card.
At 8:24, Daniel walked into the kitchen holding his phone.
“What did you do?”
I poured coffee.
“Exactly what your parents taught Ethan.”
He stared at me.
“What does that mean?”
I looked up.
“They can buy their own.”
Daniel initially accused me of retaliating over a child’s tent. I corrected him. The tent had revealed the attitude; the unauthorized party had created the boundary. His parents had been using my property after being explicitly told not to, then dismissed thousands of dollars in damage because they believed my ability to pay made the damage irrelevant.
I printed twelve months of statements before discussing anything further. The numbers surprised even me. I had paid $32,880 toward Patricia and Robert’s lifestyle during the previous year. That included lawn care, club dues, streaming packages, vehicle insurance, roadside assistance, phone upgrades, and several recurring restaurant charges linked to a family dining account.
Daniel stared at the total. “That can’t be right.” I showed him each transaction. None had been hidden. The problem was that they were scattered across accounts, so no one ever looked at the complete number. What felt like a few hundred dollars here and there had become nearly thirty-three thousand dollars a year.
The arrangement had started four years earlier when Robert underwent a temporary income drop after retirement. At the time, Daniel and I agreed to cover several bills for six months. The six months ended. The payments did not. Every time I suggested reviewing them, Daniel said his parents were embarrassed and we should give them more time.
Meanwhile, Patricia and Robert were taking cruises, upgrading electronics, and maintaining a club membership that cost more each month than Ethan’s after-school program. Their finances were not desperate. They had simply adjusted their budget around the assumption that certain bills belonged to me.
I did not cancel anything registered solely in their names without notice. I removed my own cards where the agreements permitted it and sent them a spreadsheet showing exactly which payments required replacement methods. For the truck insurance, I gave Robert enough notice to prevent a lapse because I was not interested in creating a safety problem to make a point.
Patricia responded by telling relatives I had cut off two elderly people after they hosted a birthday party. Then my brother-in-law called asking why I was “financially abusing” Daniel’s parents. I forwarded him the repair estimate and asked whether he wanted to take over the $2,740 monthly contribution. He never replied.
The property damage became its own issue. My contractor confirmed the deck resealing had to be partially redone because furniture and spilled alcohol disturbed sections before curing. The railing damage came from guests leaning against an area not designed for that load. The pool equipment also contained debris from party decorations, requiring service.
I sent Patricia and Robert the $4,800 estimate and asked them to reimburse the actual repair costs. Robert refused. He said hosting family at “their son’s house” gave them implied permission. I reminded him the house was jointly occupied by Daniel and me, and I had explicitly told them no party because of active work.
Daniel stayed silent during that conversation.
That silence was becoming a problem.
Later, I asked him whether he agreed that his parents could ignore my instructions inside our home. He said no. Then he added, “But making them pay everything themselves is harsh.”
I asked what he thought adulthood meant.
He had no answer.
Two days later, Patricia arrived at our house with a folder of her own. She expected to prove that we had promised permanent support.
Inside was a four-year-old email from Daniel.
Claire and I will cover these things until you’re fully back on your feet. Don’t worry about paying us back.
Patricia pointed at it triumphantly.
I read it carefully.
Then I looked at Daniel.
“Are they still getting back on their feet?”
He lowered his eyes.
Because the same folder also contained their recent cruise receipts, club renewal, and paperwork for the new SUV they planned to lease the following month.
The issue was no longer whether they could afford independence.
It was whether anybody had ever expected them to try.
Daniel and I spent the next several weeks in couples counseling because the dispute exposed something larger than his parents’ expenses. He had grown up believing supporting family meant preventing them from feeling financial discomfort. I had grown up believing help should solve a temporary problem, not become part of someone else’s permanent lifestyle.
Our therapist asked Daniel to imagine the arrangement reversed. Suppose my parents regularly used our home without permission, damaged property, dismissed his objections, and expected him to fund their hobbies indefinitely. He admitted he would be furious.
That was the beginning of change.
Patricia and Robert resisted longer.
When their country-club account required a new payment method, they canceled the membership instead of paying it themselves. Their lawn service was reduced from weekly to twice monthly. They switched phone plans and dropped several subscriptions.
Nothing terrible happened.
Robert obtained his own truck-insurance policy.
Patricia started tracking household spending for the first time in years.
Within two months, they discovered they could cover their actual necessities from retirement income. What they could not afford was every luxury they had kept because somebody else was paying.
The $4,800 repair dispute eventually ended in compromise. Daniel believed his parents should reimburse the full amount. I agreed to absorb the portion related to ordinary resealing work we would have paid anyway. Patricia and Robert reimbursed $3,600 tied directly to damage and additional labor caused by the party.
I required one more thing.
Our spare house key came back.
Patricia called that humiliating.
I called it appropriate after an unauthorized event.
For six months, they visited only when invited.
Then something unexpected happened.
Ethan’s birthday arrived.
Robert gave him a brand-new camping tent.
I almost laughed when I saw it.
But before Ethan opened the box, Robert crouched beside him and said, “I owe you an apology. When you asked to borrow ours, I told you to buy your own. That wasn’t kind.”
Ethan shrugged in the uncomplicated way children sometimes do.
“Can Grandpa camp with me?”
Robert smiled.
“Yes.”
They slept in our backyard that weekend.
With permission.
That mattered more to me than the tent.
Patricia’s apology came later. She admitted she had begun seeing our property and money as extensions of Daniel because he was her son. Since Daniel and I were married, she treated the distinction between his resources and mine as unnecessary.
I told her the distinction was consent.
She nodded.
Our relationship improved, but the old financial arrangement never returned.
We occasionally paid for family dinners or bought generous gifts.
When Robert’s water heater failed unexpectedly, Daniel and I offered an interest-free loan because replacing it genuinely strained their monthly budget.
They repaid it.
The fact that they repaid us without being chased showed me how much had changed.
Daniel changed too.
He stopped promising our resources before speaking with me.
That rule worked both ways.
If either of us wanted to provide substantial family support, we discussed the amount, purpose, and duration first.
The system felt formal at first.
Then it felt peaceful.
A year after the party, I totaled the expenses again.
We were saving more than $25,000 annually compared with the old arrangement, even after occasional gifts and genuine help.
We put some of that toward Ethan’s education account.
The rest went into our retirement savings.
That felt appropriate.
Money previously used to preserve adults from ordinary responsibility was now strengthening our own household.
The pool remained too.
We repaired the deck, replaced the damaged furniture, and installed a keypad on the backyard gate.
Patricia once joked that I had turned the house into Fort Knox.
I smiled.
“Ask before coming over and you’ll never notice.”
She laughed.
Two years earlier, that sentence would have started an argument.
Now it didn’t.
That became the real lesson.
Boundaries are often called cruel by people who benefited from their absence.
The first month after I stopped paying, my in-laws believed I was punishing them.
Eventually, even they recognized something else.
I had not taken away their money.
I had stopped supplying mine.
I had not banned them from family life.
I had ended automatic access to property and accounts that required permission.
And I had not taught Ethan to be selfish.
They had accidentally taught all of us something useful when they laughed and told an eight-year-old, “Buy your own.”
They meant that other people’s belongings were not automatically his.
They were right.
They just never expected the same rule to apply to them.