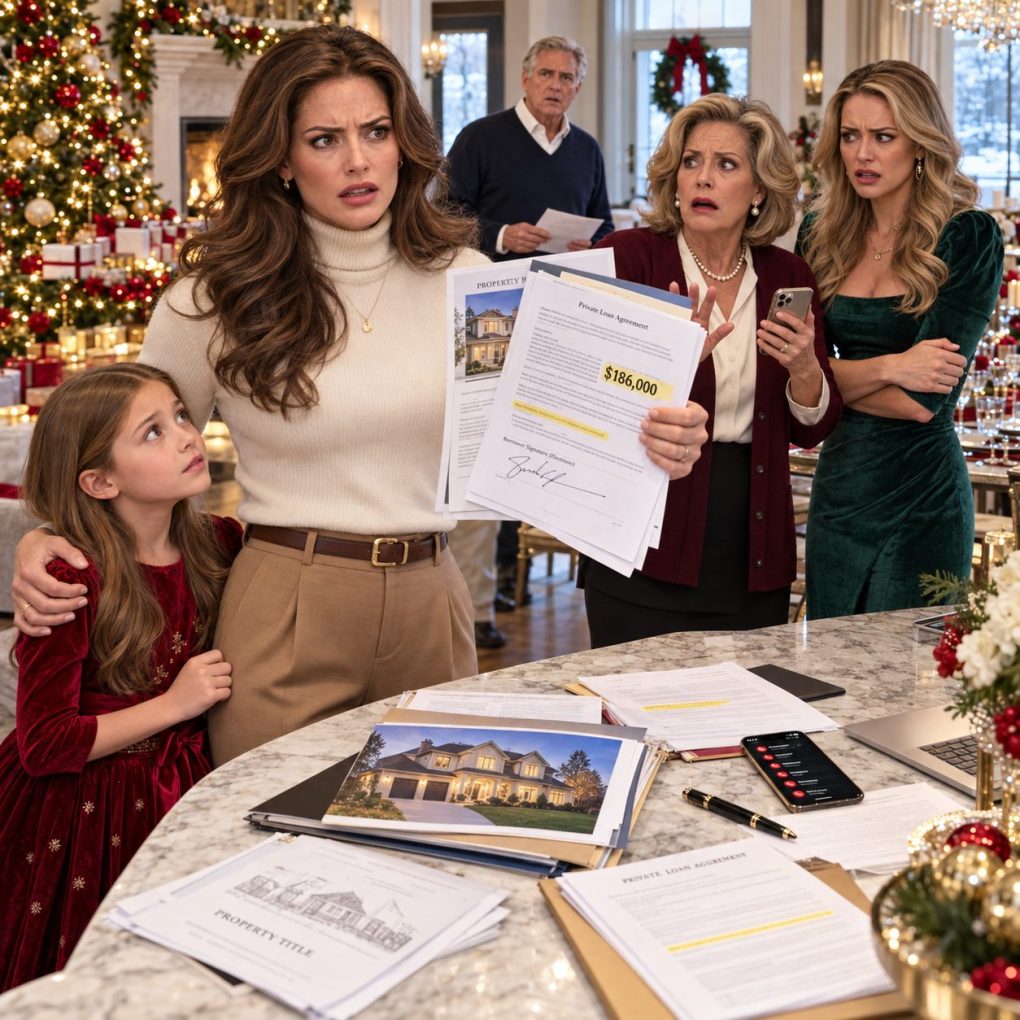
The moment I saw my nine-year-old daughter sitting on a metal folding chair beside my mother’s kitchen trash can, I knew something was wrong.
Everyone else had a real seat.
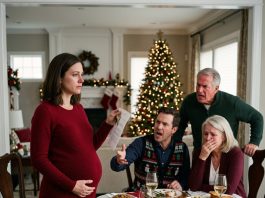
My parents’ dining table was dressed for Christmas with linen napkins, crystal glasses, and the china my mother only used twice a year. My sister Lauren’s two sons sat between their parents, my father was at the head of the table, and even Lauren’s boyfriend’s mother had a padded chair.
Emma was six feet away, half in the kitchen, beside a black trash bin.
“Mom,” she whispered. “Grandma said there weren’t enough chairs.”
There were three unused chairs in the den.
I looked at my mother, Carol. She avoided my eyes and reached for the gravy.
Lauren smiled.
For the past month, Mom had been pushing me to buy the brick house next door to theirs. My parents owned it after my grandmother died, and they had offered it to me before listing it. I had submitted a $468,000 offer through my agent, Mark, contingent on inspection and clean title.
I’d told myself moving next door might be good for Emma. Family nearby. A yard. A stable school district.
Then my daughter tugged my sleeve.
“Do we still have to move next door?”
The room went quiet.
Lauren laughed into her wine.
“You already made the offer, sweetheart.”
The way she said it tightened something in my stomach.
Not “you’ll love it there.”
You already made the offer.
Emma stared at the floor. I asked why she wanted to know.
She whispered, “Aunt Lauren said when we live next door I should get used to knowing where my place is.”
Every face at the table froze.
Lauren rolled her eyes. “Oh, come on, Sarah. She misunderstood.”
“You put her beside the trash.”
“It’s a chair.”
Mom finally spoke. “Please don’t ruin Christmas.”
That sentence did it.
I took Emma’s coat, grabbed mine, and walked out while my mother called after me that I was being dramatic.
By 8:12 the next morning, I was on the phone with Mark.
My inspection contingency expired at noon. I told him to withdraw my offer immediately.
At 8:27, he emailed confirmation.
At 8:31, my phone rang.
Mom. Dad. Lauren. Mom again.
Six calls in four minutes.
I finally answered.
My mother didn’t ask about Emma.
She said, “Call Mark back. Tell him you made a mistake.”
“No.”
“Sarah, you don’t understand. That house has to close.”
“Why?”
Silence.
Then I heard my father behind her.
“Carol, don’t tell her about the note.”
“What note?” I asked.
Mom came back breathing hard.
“Your sister borrowed some money. We were going to handle it.”
“What does that have to do with me buying your house?”
Another silence.
Then she said, “Because they used your offer to keep the loan from being called.”
Before I could answer, an email from Mark appeared.
Subject: URGENT — TITLE ISSUE.
Attached was a document with my name on it.
A document I had never seen before.
I thought withdrawing a house offer would end a family argument. Instead, it opened a door I didn’t know existed. The document Mark sent me wasn’t just connected to my parents’ house. It was connected to my identity, my credit, and a debt no one had ever told me about.
I opened the attachment with my mother still breathing into the phone.
At the top was the name of a private lender I had never heard of: Hawthorne Capital Funding. Beneath it was an “Assignment of Purchase Proceeds” tied to the house next door.
The amount was $186,000.
My parents had borrowed it seven months earlier.
The document said that when I purchased the house, part of the sale proceeds would satisfy the debt. That alone would have been their problem.
Then I reached the bottom.
My name was there.
Sarah Bennett.
Under it was an electronic signature that looked almost exactly like mine.
I hung up on Mom.
Mark called thirty seconds later.
“The title company found the loan during the preliminary search,” he said. “They also found this document in the lender’s payoff package. Did you sign it?”
“No.”
“Then don’t sign anything else. And don’t communicate with the lender alone.”
My hands started shaking.
I called my mother back and demanded the truth.
She admitted Lauren’s home-staging business had been collapsing for almost a year. My parents had mortgaged the house next door to keep it alive. Hawthorne had given them a short-term loan at a brutal interest rate, due January 5.
My purchase was supposed to pay it off.
“So you wanted me next door because you needed my money.”
“That’s not fair,” Mom snapped. “We wanted you close too.”
“Did you know my signature was on this?”
Silence.
Then Lauren called.
She didn’t deny anything. She accused me of destroying the family over “one stupid chair” and said if I walked away, Mom and Dad could lose the property.
I asked who copied my signature.
She hung up.
An hour later, Mark forwarded another file from the title officer.
This one was worse.
It was a personal guaranty.
According to the document, I had guaranteed repayment of the entire $186,000 loan if the sale failed to close.
It listed my old apartment address, my date of birth, and the last four digits of my Social Security number.
All correct.
I had never signed it.
“Where did they get this information?” I asked Mark.
“I don’t know. But the lender says the guaranty was submitted from an email address using your name.”
Then he read it aloud.
I recognized it instantly.
Lauren had created that account three years earlier when she helped me collect documents for my divorce refinance.
I hadn’t used it since.
Before I could process that, an unknown number called.
A man introduced himself as Hawthorne’s fraud counsel.
Then he said, “Ms. Bennett, we need to discuss whether you actually authorized this loan.”
That was when I understood this wasn’t about a cruel Christmas dinner anymore.
Someone in my family had built a financial transaction around pretending to be me.
I didn’t answer the lawyer’s question.
I took his name, number, and email, then told him my attorney would contact him.
I didn’t have an attorney yet.
By noon, I did.
Mark referred me to Denise Morgan, a real-estate attorney who handled identity-theft disputes. I sent her every document, froze my credit, placed a fraud alert, changed my passwords, and filed an identity-theft report.
“Your job now,” she said, “is to create a clean record showing what you did and did not authorize.”
That afternoon, she sent Hawthorne and the title company a sworn statement denying both signatures.
Then my mother showed up at my apartment.
Emma was in her bedroom watching a movie. I stepped into the hallway and closed the door.
Mom looked exhausted.
“Please put the offer back,” she said.
Not “I’m sorry.”
Not “Are you okay?”
Put the offer back.
I asked one question.
“Did you know Lauren used my name?”
Mom’s face changed.
She admitted she knew Hawthorne wanted “extra reassurance” before extending the loan. Lauren had told her I agreed to guarantee it because I planned to buy the property anyway.
“Did you ever ask me?”
“No.”
“Did you ever hear me say yes?”
“No.”
“Then why did you believe her?”
Mom started crying.
Because they needed to.
Lauren’s business, Lark & Pine Staging, had been losing money for more than a year. She had hidden unpaid vendor bills, maxed-out business cards, and overdue taxes. My parents had already given her nearly $70,000. When that disappeared, they borrowed against the house next door.
The loan was supposed to be temporary.
Then it came due.
Lauren convinced Hawthorne that the house had a committed buyer: me. She sent them my legitimate purchase offer. Then she used the old email account, an outdated copy of my driver’s license, and financial documents she still had from helping with my divorce refinance to make it look as though I had agreed to stand behind the debt.
My mother knew Lauren was using my purchase to keep Hawthorne calm.
She claimed she did not know Lauren had actually signed my name.
Before Mom left, she said, “If that sale doesn’t happen, your father and I could lose a lot of money.”
I said, “You were willing to risk my name so you wouldn’t lose yours.”
She had no answer.
The next morning, Dad asked to meet alone.
He brought printed text messages between Mom and Lauren.
One stopped me cold.
Three days before Christmas, Lauren had written: Sarah cannot back out now, right?
Mom replied: She won’t. Once she closes, everything is covered. Just keep Christmas peaceful.
My mother had known there was a reason I could not be allowed to walk away.
Dad said he knew about the $186,000 loan, but he had never seen my supposed guaranty until I withdrew the offer. He believed Lauren when she said Hawthorne only needed proof that a sale was pending.
Then he told me what I hadn’t understood about Christmas dinner.
Lauren thought my parents were practically “giving” me the house.
They weren’t. My offer was based on an appraisal and was only $7,000 below the price they had planned to list it for.
But Lauren had spent months telling herself I was getting a family gift while she was drowning.
Putting Emma beside the trash had been deliberate.
Lauren wanted to humiliate me without confronting me directly. She had told Mom that I needed to “remember this family doesn’t revolve around Sarah.”
Mom let it happen because she was afraid a fight might expose the loan before I closed.
That hurt more than the forged signature.
The house had never been about bringing Emma and me closer.
We were the exit strategy.
Denise handled everything from there.
Hawthorne opened a fraud review. The lender discovered the email account’s recovery phone number belonged to Lauren. The documents submitted with the guaranty were old, and the electronic signature history did not match the way I had signed the real purchase contract.
Within two weeks, Hawthorne confirmed in writing that it would not treat me as a guarantor.
A month later, it formally released any claim against me.
The police investigation took longer.
I gave a statement and turned over the documents. Dad provided his texts. Mark and the title officer provided transaction records.
Lauren stopped calling after Denise sent a no-contact letter.
Her husband, Eric, called once. He said he knew the business was struggling but not that she had used my identity.
I didn’t comfort him.
By February, Lark & Pine had closed.
My parents listed the house next door with an independent agent. They sold it in March for less than they hoped. After the loan, interest, legal fees, taxes, and closing costs were paid, most of the equity they thought they were protecting was gone.
They did not lose their primary home.
But they lost the illusion that hiding Lauren’s problems had protected anyone.
The county prosecutor eventually filed charges related to the forged documents. Lauren later accepted a plea that included restitution, probation, and financial restrictions. I did not attend the hearing.
People sometimes ask whether I felt guilty.
I didn’t.
I felt sad.
There is a difference.
I was sad that my sister had used my identity rather than admit her business had failed. I was sad that my mother saw the warning signs and chose silence. I was sad that my father waited until everything broke before deciding honesty mattered.
But I was not sorry I withdrew the offer.
In April, Emma and I bought a different house eighteen minutes away.
It had a small backyard, a blue front door, and a dining room that barely fit a six-person table.
On our first night there, we ate takeout pizza because the kitchen boxes were still packed.
Emma carried two chairs in from the garage.
Then she grinned.
“Real chairs?”
I laughed harder than I expected.
“Only real chairs in this house.”
The following Christmas, we did not go to my parents’.
Dad came by two days later with a gift for Emma and an apology that did not contain the word “but.” I let him stay for coffee.
Mom sent a long letter. For once, she did not ask me to fix anything. She wrote that protecting Lauren had become a habit, and eventually that habit turned into sacrificing whoever was most likely to forgive them.
I still keep distance.
Forgiveness does not require giving people the same access they had before.
Emma never moved next door to my parents.
Neither did I.
And the folding chair beside the trash can, the thing everyone accused me of overreacting to, turned out to be the smallest betrayal of that Christmas.
It was simply the first one I could see.