“There will be important people there,” my husband wrote. “Mom thinks you’ll embarrass us.” He wanted me to stay away from my own son’s birthday so his wealthy relatives could pretend I didn’t exist. I didn’t argue. I simply opened the foreclosure file I had quietly resolved months earlier and made one decision before sunrise.
My name is Hannah Reed, and my husband, Grant, came from a family that treated money like a blood type.
His mother, Evelyn Reed, had spent twelve years reminding me that I had married “up.”
I grew up in rural Indiana.
My father repaired farm equipment.
My mother taught elementary school.
I became a commercial lending attorney.
Apparently, none of that mattered because I did not belong to the Reed family’s country club.
Our son, Oliver, was turning eight.
He had been talking about his birthday for weeks.
Grant told me his mother wanted to host it at Hawthorne House, the family estate outside Indianapolis.
Then, the night before the party, his message arrived.
There will be important people there. Mom thinks you’ll embarrass us. Maybe let Oliver enjoy one afternoon without tension.
I read it twice.
Then I walked into Oliver’s room.
His dinosaur costume was hanging over the chair because the party had a prehistoric theme.
“Are you coming tomorrow?” he asked.
I smiled.
“I’m still figuring out the schedule.”
He nodded and went back to building a plastic volcano.
I kissed his head.
Then I went downstairs.
Grant was already asleep.
I opened my laptop.
Six months earlier, Evelyn had called me privately.
Hawthorne House was in foreclosure.
Grant’s father had borrowed heavily against the estate before his death, and Evelyn had missed payments for nearly a year.
She begged me not to tell Grant.
“He’ll think I failed his father.”
I contacted the lender professionally, helped restructure part of the debt, and eventually arranged for a holding company I controlled to purchase the note at a discount when the bank decided to exit.
Evelyn knew an investor had saved the property.
She did not know it was me.
Neither did Grant.
I had planned to transfer the restructured loan into a family trust once Evelyn stabilized her finances.
Then Grant told me I was too embarrassing to attend my own child’s birthday in the house I had prevented from being sold.
At 4:38 a.m., I opened the foreclosure file.
The loan documents were clear.
Evelyn had missed two payments under the new agreement.
I could have accelerated the debt.
I did not.
Instead, I sent one email to my servicing attorney.
Do not waive the defaults again. Follow the contract exactly. No special treatment.
At 7:15, Grant came downstairs in a suit.
“You’re really not coming?”
“No.”
He seemed relieved.
That was the part I remembered.
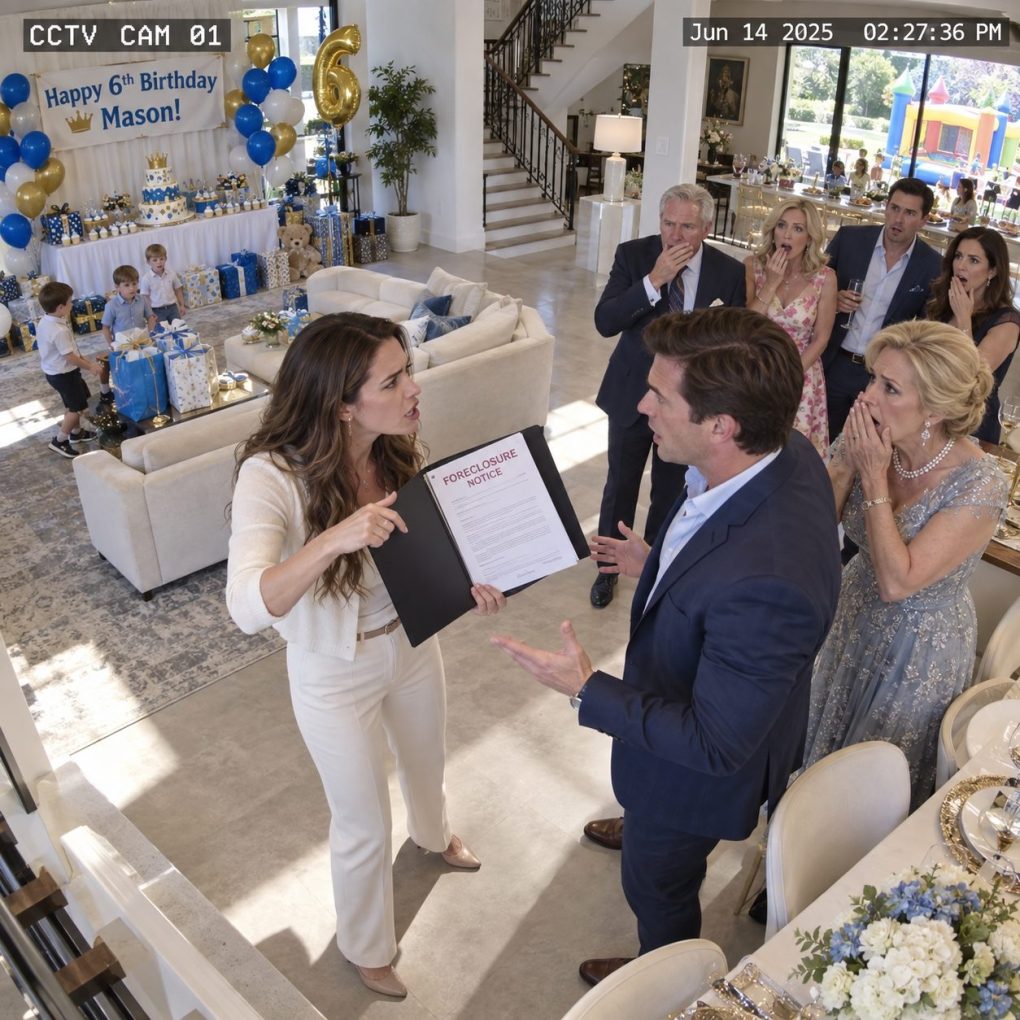
Three hours later, while wealthy relatives drank champagne beneath Hawthorne House’s chandeliers, a courier arrived at the front door carrying a formal default notice.
Evelyn opened it.
Then she read the name of the company holding her mortgage.
And finally understood who had been keeping her house standing.
The company was called HBR Capital Holdings. The initials meant nothing to most of the family, but Evelyn recognized the mailing address immediately because she had once sent financial documents there during the restructuring. What she had never asked was who owned it. The answer was Hannah Bennett Reed—me—through a separate investment entity established years before my marriage.
The notice did not evict anyone that afternoon. It did not cancel Oliver’s birthday or send sheriffs through the gates. It simply stated that two required payments had been missed and that the informal grace periods previously extended would no longer continue. Evelyn had a contractual cure period, and the consequences were spelled out exactly as they had been from the beginning.
Grant called me eleven times before noon. I answered the twelfth. His first question was not why I had hidden the investment. It was, “Are you trying to take Mom’s house because of one text?” I told him no. The missed payments existed before his message. The only thing his message changed was my willingness to keep protecting his family from consequences they believed they were entitled to avoid.
He accused me of setting everyone up. I reminded him that six months earlier, Evelyn had been days from losing Hawthorne House through a bank foreclosure. The bank had rejected another extension. I had negotiated an orderly purchase of the note, reduced immediate pressure, and accepted a payment schedule far more flexible than the original lender offered.
Then I asked him something simple. “Did your mother tell you the house was in foreclosure?” Silence. She had not. Evelyn had continued hosting charity luncheons, family dinners, and political fundraisers while telling everyone the estate was financially secure. Grant had spent months assuming his mother possessed millions in liquid assets.
The truth was worse. After restructuring the debt, Evelyn had resumed spending as if nothing had happened. A new greenhouse. Imported furniture. A luxury lease on a second vehicle. She had made the first three loan payments, then quietly skipped the next two while assuming I—or whoever the mysterious investor was—would extend another courtesy.
My attorney had documented every prior extension. I had authorized them because Evelyn kept promising that a property sale from another part of the estate would provide cash. That sale never happened. Each time, she requested “just thirty more days.” I kept agreeing because I wanted Oliver to retain the family home connected to his grandfather.
By afternoon, the party atmosphere had disappeared. Evelyn gathered Grant, his two sisters, and her accountant in the library. She finally admitted that Hawthorne House had nearly been lost months earlier and that someone had intervened. Then she placed the default notice on the table and said, “That someone was Hannah.”
Grant came home after midnight. He looked exhausted. He asked why I never told him. I told him because his mother had asked for confidentiality and because I did not need gratitude. I wanted the debt stabilized, not applause. “Then why reveal yourself now?” he asked.
“I didn’t reveal myself,” I said. “The contract did.” HBR’s ownership was already in the servicing records. Once Evelyn defaulted again, formal notice had to identify the current noteholder. I had simply stopped instructing counsel to bend the agreement around her choices.
Grant sat across from me for nearly a minute before asking whether I planned to foreclose. I said that depended on whether his mother cured the default and presented a credible repayment plan. I would not use Oliver’s birthday as leverage, and I would not punish Evelyn because she disliked me.
But I would no longer finance the illusion that I was beneath people whose roof remained theirs partly because I had chosen, repeatedly, to keep it that way.
Evelyn cured one missed payment within the contractual period but could not cover the second. Her accountant finally produced a complete picture of her finances. Hawthorne House itself remained valuable, but maintaining it cost far more than the family’s available income could support. Prestige had become an expense they were financing with denial.
I offered no special rescue this time. Instead, HBR proposed three standard options: refinance with another lender, sell part of the surrounding acreage to reduce principal, or place Hawthorne House on the market and satisfy the loan from proceeds. Evelyn rejected all three initially because each required admitting the estate could no longer operate as it once had.
Grant surprised me. He told her the truth I had stopped saying years earlier: “Keeping the house is not worth humiliating Hannah to preserve the idea that we’re richer than we are.” Evelyn stared at him as though he had betrayed the family. Maybe in her world, honesty felt like betrayal.
The Reed siblings eventually agreed to sell twenty acres of unused land along the northern boundary. The transaction brought enough cash to cure the default, reduce the principal substantially, and fund essential maintenance without another loan. HBR approved the arrangement because it made financial sense, not because Grant was my husband.
Evelyn and I did not become close. She apologized once, awkwardly, for excluding me from Oliver’s party. Her words focused too much on “misunderstanding” and not enough on what she had actually done, but I accepted the apology for what it was. Then I established a rule: no more private financial rescues between us.
Grant and I had the harder conversation. He admitted he had sent the message because his mother spent the week telling him several wealthy donors and family friends would judge him if I “made things uncomfortable.” I asked what, specifically, I had ever done that embarrassed him. He could not give me a single example.
That silence forced him to confront something uglier. He had absorbed his family’s judgment because agreeing with them was easier than defending me. He had mistaken my willingness to ignore class snobbery for proof that it did not hurt. Couples counseling began two weeks later.
Oliver learned almost none of the financial details. He only knew that I had missed his birthday because “the adults made a bad decision.” Grant apologized to him for allowing it. Then we held a second celebration at home with pizza, a homemade dinosaur cake, and six children who destroyed the living room with inflatable fossils.
The next year, when Oliver turned nine, he made the guest list himself. My name appeared first. Evelyn attended too. There were no donors, no country-club politics, and no attempt to curate which parent looked respectable enough for photographs. That party cost less than one floral arrangement from the year before.
Hawthorne House remained in the family, but differently. After the land sale and debt reduction, Evelyn downsized the staff, canceled several expensive events, and stopped pretending every tradition had to survive unchanged. Financial reality did not destroy the family legacy. Pretending reality did not exist had nearly done that.
Three years later, HBR’s loan was paid off through a conventional refinance arranged with an independent bank. I signed the release documents without ceremony. Evelyn sent me a handwritten note afterward: I spent years thinking wealth meant never needing anyone. You taught me that the more dangerous mistake is needing someone and still treating them as inferior.
I kept the note, although it was Grant whose apology mattered most. He said, “I asked you to disappear from our son’s birthday so other people could feel important.” I answered, “Yes.” He understood by then that there was no elegant explanation hiding behind it.
We stayed married, but not because one dramatic foreclosure file repaired everything. Trust returned through smaller choices. Grant corrected relatives when they insulted me. He stopped allowing Evelyn to make decisions for our household. Most importantly, he stopped assuming that silence from me meant permission.
That became the lesson.
Money had never been the real power in Hawthorne House.
The dangerous power was the belief that appearances mattered more than people.
Evelyn protected appearances until she nearly lost her home.
Grant protected appearances until he nearly damaged his marriage.
And I protected them both until I finally understood that rescuing someone from consequences can sometimes help preserve the very behavior hurting you.
I did not foreclose on Hawthorne House.
I did something harder.
I stopped standing between the Reed family and the truth.
By sunrise, my decision had been simple: no revenge, no spectacle, no humiliation.
Just the contract.
And for people accustomed to believing I would always quietly save them, that was enough.