My son-in-law called and announced, “We froze your card.” Before I could respond, my daughter interrupted, “You’re getting old. From now on, ask us before spending any money.” I didn’t argue or raise my voice. I simply replied, “Understood.” Then I called my accountant. Three hours later, my phone showed 41 missed calls…
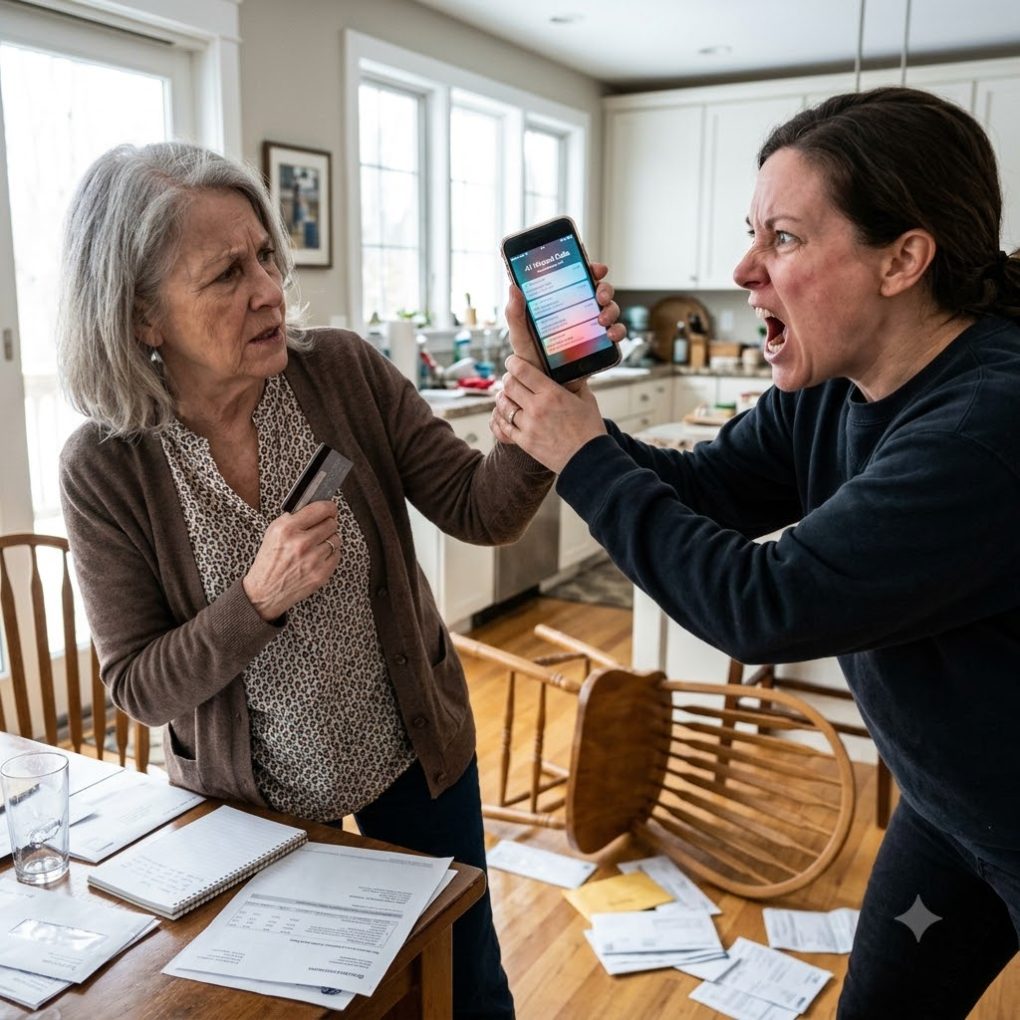
My son-in-law, Ryan, called me at 9:17 on a Tuesday morning.
“We froze your card,” he announced.
Before I could ask why, my daughter, Natalie, grabbed the phone.
“Mom, you’re sixty-nine. You’re getting old. From now on, you need to ask us before spending any money. We’re doing this for your own good.”
I stood in my kitchen, staring at the groceries I had just brought home.
“Understood,” I replied.
Natalie sounded relieved. “Good. I’m glad you’re finally being reasonable.”
I hung up without another word.
What my daughter didn’t understand was that silence wasn’t surrender.
My name is Helen Whitmore. I spent thirty-two years managing the finances of a construction company before retiring. My late husband and I had invested carefully, paid off our home, and built enough savings to live comfortably.
Six months earlier, I had given Natalie temporary access to my banking app while recovering from knee surgery. Apparently, she and Ryan had decided that helping me buy groceries entitled them to control my entire life.
I picked up my phone and called Paul Bennett, my accountant of eighteen years.
“Paul, I need you to check something.”
“What’s wrong, Helen?”
“My daughter just froze my debit card.”
There was a pause.
“That’s unusual. Let me review your accounts.”
Ten minutes later, Paul called back. His voice had changed.
“Helen, did you authorize a $160,000 transfer to a real estate escrow account?”
My stomach tightened.
“No.”
“There’s a pending wire request connected to Natalie and Ryan’s home purchase. It appears someone submitted it through your online banking access.”
I gripped the kitchen counter.
Three weeks earlier, Natalie had mentioned buying a larger house. She had asked whether I might help with the down payment. I told her we could discuss it after reviewing their finances.
I had never approved that amount.
“Paul,” I said quietly, “call the bank’s fraud department. I’m coming in.”
By noon, I had met with a bank officer, verified my identity, secured my accounts, and canceled the pending wire request.
My attorney was preparing the paperwork to formally revoke every financial authorization I had previously granted Natalie.
At 12:26, my phone began vibrating.
Ryan called first.
Then Natalie.
Then Ryan again.
By 12:48, I had forty-one missed calls.
Finally, a voicemail appeared.
It was Ryan, screaming so loudly his voice distorted.
“HELEN! WHAT DID YOU DO? THE CLOSING IS FALLING APART!”
I listened once.
Then I deleted the message and poured myself another cup of coffee.
At 1:15 that afternoon, someone started pounding on my front door.
I looked through the window and saw Natalie standing on the porch, her face red with anger. Ryan was beside her, pacing like a man who had just discovered the floor beneath him was disappearing.
“Mom! Open this door!” Natalie shouted.
I opened it but kept the security chain attached.
“What do you want?”
Ryan stepped forward.
“You canceled the wire! Do you have any idea what you’ve done?”
“Yes,” I answered. “I stopped someone from transferring $160,000 of my money without my permission.”
Natalie’s expression changed.
“Mom, we talked about helping us buy the house.”
“We talked about the possibility of helping. That’s very different from authorizing a transfer.”
Ryan slammed his palm against the doorframe.
“We’re supposed to close this afternoon! The sellers are threatening to walk away!”
“Then perhaps you should have secured your financing before making promises with somebody else’s money.”
For the first time since marrying my daughter, Ryan had nothing to say.
Natalie pushed closer.
“You’re ruining our future over a misunderstanding!”
I looked directly at her.
“Did you know about the transfer?”
She hesitated.
That hesitation told me more than her answer.
“Ryan said you had already agreed. He told me the paperwork was just a formality.”
“And you believed him?”
“He said you wouldn’t understand all the documents!”
I felt something inside me break.
Not because my daughter had called me old. Not because she had frozen my card.
Because she had apparently convinced herself that my age made my consent optional.
I closed the door.
Twenty minutes later, my attorney, Rachel Klein, arrived with a folder of documents.
Rachel had helped my husband and me prepare our estate plan years earlier. She understood how carefully we had worked to protect our savings.
“The bank stopped the transfer before the money left your account,” she explained. “They’ve also disabled the old login credentials. The attempted transaction is being reviewed.”
Then she showed me something else.
The mortgage lender had received a gift letter stating that I was providing $160,000 toward Natalie and Ryan’s purchase.
At the bottom was a signature resembling mine.
I stared at it.
“That’s not my signature.”
Rachel studied my face.
“Are you certain?”
“Absolutely.”
The signature looked remarkably similar to one I had used on a tax document the previous year. But the final stroke was wrong, and the date beside it was written in handwriting I didn’t recognize.
Rachel immediately contacted the lender’s compliance department.
By late afternoon, the closing had been postponed while the lender reviewed the gift letter and verified the source of the proposed funds.
At 6:30, Natalie called again.
This time, she wasn’t screaming.
“Mom,” she whispered, “Ryan says you can fix everything by calling the lender and confirming the gift.”
“Did you sign my name to that letter?”
Silence.
“Natalie?”
“I didn’t sign it.”
“Did Ryan?”
She began crying.
“He told me he could handle the paperwork. I didn’t ask how.”
I closed my eyes.
“Then you need to start asking questions.”
She sobbed harder.
“Mom, we’re going to lose the house.”
I looked at the framed photograph of my late husband on the mantel.
For forty-one years, he had reminded me that loving our daughter didn’t mean rescuing her from every consequence.
“Natalie, listen carefully. I love you. But I’m not going to lie to a mortgage lender to save a house you tried to buy with money I never agreed to give you.”
She whispered something I almost couldn’t hear.
“Ryan said you’d eventually forgive us.”
“Forgiveness and permission are two different things.”
Then she asked the question that made my blood run cold.
“Mom… are you going to tell the police?”
I didn’t answer Natalie’s question immediately.
Instead, I asked her something that had been troubling me all afternoon.
“Why did you freeze my debit card?”
She sniffled.
“Ryan thought you might start moving money around before the closing.”
“So you wanted to prevent me from spending my own money while you arranged to spend $160,000 of it?”
She started crying again.
“Mom, when you say it like that…”
“That’s exactly what happened, Natalie.”
I could hear Ryan shouting in the background, demanding that she hand him the phone.
Then the call ended.
The next morning, Rachel accompanied me to the bank for a follow-up meeting. The fraud investigator explained that the pending transfer had been stopped and that the bank would preserve the account records for its investigation.
Rachel advised me not to negotiate privately with Ryan while the disputed documents were being reviewed.
I agreed.
Two days later, Natalie came to my house alone.
She looked exhausted. There were dark circles beneath her eyes, and she wore the same gray sweater I remembered buying her the previous Christmas.
“Can we talk?” she asked.
I let her inside.
For several minutes, we sat across from each other at the kitchen table where she had done her homework as a little girl.
Finally, she spoke.
“Ryan told me we’d lose the deposit if the closing failed. He said we were already too committed to back out.”
“Did he tell you how much money he had saved?”
She shook her head.
“Did he show you the mortgage application?”
Another shake.
“Then why were you telling me I couldn’t handle my own finances when you didn’t understand yours?”
Tears rolled down her cheeks.
“Because I trusted him.”
“I trusted you,” I replied.
Those three words silenced her.
Natalie then admitted something else. Ryan had been pressuring her for months to convince me to transfer more of my savings into accounts they could manage. He argued that it would be easier to handle my eventual inheritance if they organized everything now.
I felt sick hearing it.
“I’m not an inheritance, Natalie. I’m your mother. And I’m still alive.”
She covered her face with both hands.
“I’m sorry.”
I believed she was sorry.
But I also understood that an apology couldn’t restore trust overnight.
Over the following weeks, the lender withdrew approval for the home purchase after the documentation concerns remained unresolved. The sale never closed.
The disputed gift letter was referred for further review. Rachel helped me provide the relevant records, and I left the investigation to the appropriate authorities rather than trying to settle it through family arguments.
Meanwhile, I updated my estate documents, changed my account permissions, and arranged for an independent professional to handle financial matters if I ever became unable to do so.
Natalie would no longer have access to my accounts.
Ryan sent several angry messages accusing me of destroying his marriage and financial future.
I never responded.
Six weeks later, Natalie called from a small apartment she had rented after separating from him.
“I got a job,” she told me. “Full-time. At a medical office.”
“That’s good, sweetheart.”
“I know you probably don’t trust me anymore.”
“Trust takes time to rebuild.”
“I understand.”
There was a long silence.
Then she said, “I miss having coffee with you.”
I looked toward the empty chair across my kitchen table.
“Sunday morning,” I answered. “Ten o’clock. Just you.”
She started crying.
That Sunday, Natalie arrived carrying blueberry muffins from the bakery near her apartment.
We didn’t discuss money.
We didn’t pretend nothing had happened.
We simply sat together, drank coffee, and began the difficult process of learning how to be mother and daughter again.
Before leaving, she hugged me tightly.
“I’m glad you’re okay, Mom.”
I held her for a moment.
“So am I.”
After she left, I picked up my phone and opened my banking app.
My accounts were secure. My bills were paid. My savings were still mine.
And for the first time in months, nobody else had the power to decide whether I could buy myself a cup of coffee.
My daughter had tried to take away my independence because she thought getting older meant becoming powerless.
But age hadn’t made me helpless.
It had taught me exactly when to stop explaining myself.
Forty-one missed calls had been enough to remind me of something important.
Sometimes the strongest response to someone trying to control your life isn’t an argument.
It’s quietly taking back the keys.