My son texted me, “Don’t contact us again until you’re ready to change.” I simply replied, “Okay.” Forty-eight hours later, he called in a panic. “The mortgage payment bounced, and they’re repossessing the car!” What he didn’t realize was that I’d already closed the accounts…
My son texted me at 8:43 on a Wednesday morning.
“Don’t contact us again until you’re ready to change.”
I stared at those eleven words for a long moment. Then I typed one simple reply.
“Okay.”
My name is Evelyn Carter. I’m sixty-eight years old, a retired school administrator living outside Columbus, Ohio. And until that morning, I had been quietly paying most of my forty-one-year-old son’s bills for nearly two years.
His mortgage was $2,850 a month. His SUV payment was $920. Both were automatically withdrawn from checking accounts I had opened specifically to help him.
When Patrick lost his management position eighteen months earlier, he promised the arrangement would be temporary.
“Six months, Mom. That’s all I need.”
Six months became twelve. Then eighteen.
Last Sunday, I finally asked him to show me his household budget before I continued sending money.
His response was explosive.
“You treat me like a child!”
“I just want to understand where the money is going.”
“My wife and I don’t need you controlling our lives!”
That was the argument that led to Wednesday’s message.
But Patrick had forgotten something important.
The accounts weren’t his.
They were mine.
At 10:15, I walked into my bank and asked to speak with the branch manager.
“I want to close two checking accounts,” I explained. “And transfer the remaining balances into my personal savings.”
She reviewed my identification and the account ownership.
Both accounts belonged solely to me. Patrick had been permitted to arrange certain bill payments from them, but he had no ownership rights.
I made sure no legal obligations or co-signed loans were attached to my name.
Then I signed the documents.
By lunchtime, both accounts were closed.
I didn’t call Patrick. He had specifically told me not to.
Exactly forty-eight hours after his message, my phone rang.
It was Patrick.
“Mom!” he shouted. “What did you DO?”
I stayed quiet.
“The mortgage payment bounced! The bank says the account is CLOSED!”
“That’s correct.”
His breathing became ragged.
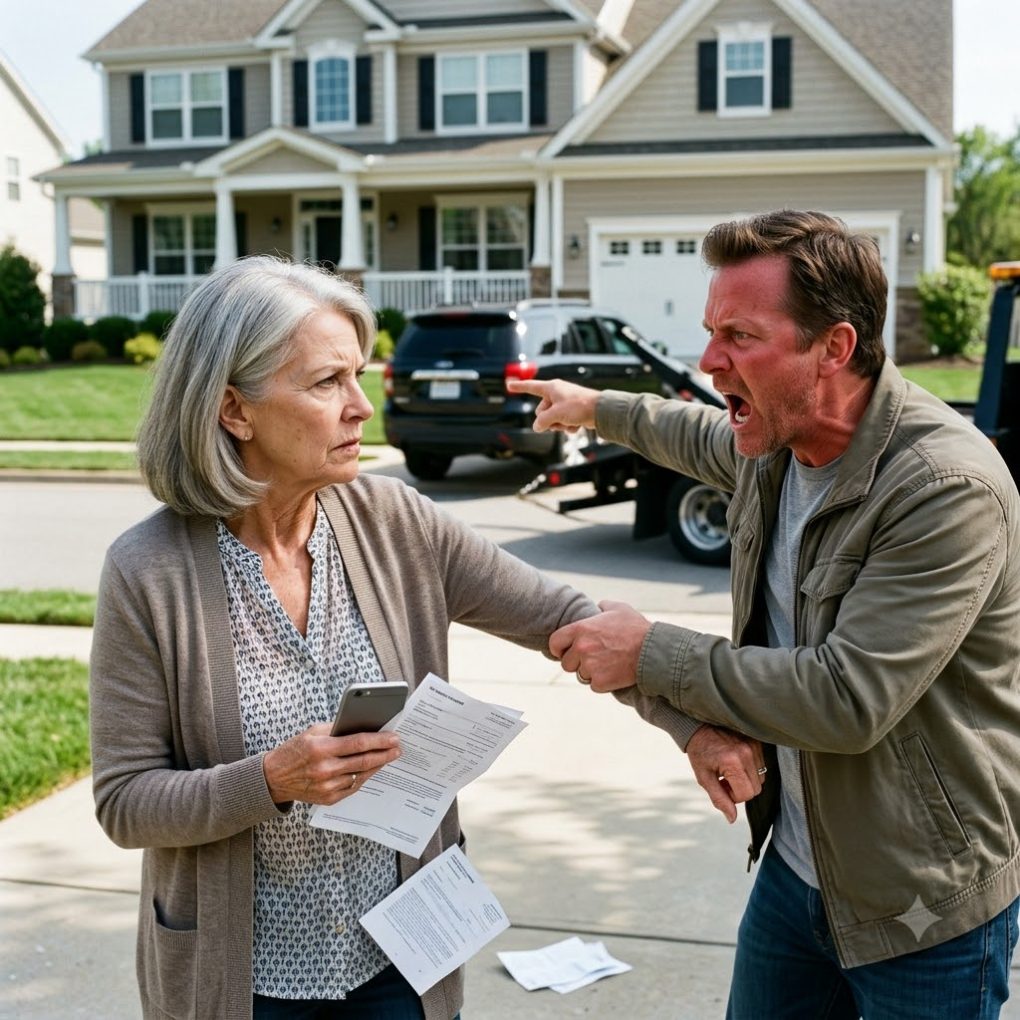
“And the car! They’re repossessing the car! There’s a truck outside our house!”
I looked toward my kitchen window.
“I’m sorry you’re having trouble.”
“YOU’RE SORRY? YOU DESTROYED EVERYTHING!”
“No, Patrick. I stopped paying for everything.”
For several seconds, he said nothing.
Then he whispered something that made my blood run cold.
“Mom, you don’t understand. If we lose that car, Laura’s going to find out what I’ve been hiding.”
I slowly lowered my coffee cup.
“What exactly have you been hiding, Patrick?”
Patrick didn’t answer immediately. I could hear shouting in the background, followed by a car door slamming.
“Mom, please,” he whispered. “Just send me ten thousand dollars. I’ll explain everything afterward.”
“Not another dollar until you tell me the truth.”
He cursed under his breath.
Then I heard my daughter-in-law, Laura, screaming.
“Patrick! They’re hooking up the SUV! Do something!”
My son covered the phone, but I could still hear him shouting back.
“Tell them the payment is coming!”
When he returned to the call, his voice had changed from anger to desperation.
“I haven’t been completely honest about the bills.”
“How dishonest?”
“The car payments are three months behind.”
I sat down.
“Patrick, I’ve been depositing enough money to cover that payment every month.”
“I know.”
“Then where did the money go?”
Silence.
Finally, he admitted that he’d been using part of my monthly deposits to cover credit card balances, business expenses, and personal loans Laura knew nothing about.
The SUV had already been scheduled for repossession because he had ignored repeated notices. He had planned to use that Friday’s payment to stop the process.
But Friday’s payment had been returned because my account was closed.
“And the mortgage?” I asked.
“It’s not in foreclosure,” he admitted. “But the latest payment was returned. We’re already behind on other bills.”
I closed my eyes.
For eighteen months, I had believed I was protecting my son’s family from financial disaster. Instead, I had been financing a disaster he refused to acknowledge.
“Does Laura know any of this?”
“No.”
“Then I suggest you tell her.”
“Mom, she’ll leave me!”
“Then you should have thought about that before lying to both of us.”
He suddenly became furious again.
“You can’t do this! You promised to help!”
“I promised temporary assistance when you lost your job. I never promised to pay your debts forever.”
“You’re choosing money over your own family!”
“No, Patrick. I’m choosing not to be manipulated by my own son.”
He hung up.
Twenty minutes later, Laura called.
She was crying so hard I could barely understand her.
“Evelyn, what happened? Patrick said you emptied our accounts out of revenge!”
“Laura, those were my accounts. I closed them after Patrick told me not to contact either of you.”
She went silent.
“What do you mean, your accounts?”
I explained the arrangement. The money had always come from my retirement savings. Patrick had been using it to cover major household payments while he supposedly got back on his feet.
Then I asked her something.
“Laura, did you know he hadn’t made the last three car payments?”
“No,” she whispered.
“Did you know he was using some of my money for credit cards and personal loans?”
Another silence.
Then she started crying again.
“He told me he’d been working with a consulting company. He said business was improving.”
My stomach sank.
Patrick had told me the same thing.
I asked Laura to check their financial records before making any more decisions.
That evening, she appeared at my doorstep carrying a folder of unopened envelopes.
Her hands were shaking.
“Patrick left the house,” she said. “He won’t answer his phone.”
I invited her inside.
She spread the envelopes across my dining table.
There were late-payment notices, credit card statements, and collection letters. The amounts were staggering.
More than $67,000 in unsecured debt.
Some statements went back over a year.
Laura looked at me with swollen eyes.
“I didn’t know, Evelyn. I swear I didn’t know.”
I believed her.
Then she pulled out one final envelope.
It was addressed to Patrick, but she had found it among the discarded paperwork in his home office.
Inside was a loan application.
And listed under additional household
My attorney, Margaret Ellis, had known my family for almost twenty years. She helped my late husband and me organize our estate documents before he passed away.
When Laura and I showed her the loan application the following morning, her expression became serious.
“Do you recognize this signature, Evelyn?”
“It resembles mine. But I never signed that document.”
Margaret examined the paperwork carefully.
“The application references a private personal loan. We need to confirm whether this was submitted, approved, or funded before drawing conclusions.”
She contacted the lender using the information printed on the document.
By that afternoon, we had an answer.
Patrick had submitted the application six months earlier, claiming that I had committed to providing regular financial assistance for five more years.
The lender confirmed that a loan had been issued in Patrick’s name. My purported agreement was among the supporting documents.
I felt physically sick.
My son hadn’t merely lied about how he was spending my money.
He had used my name to make his financial situation look stronger.
Margaret advised me to formally dispute the document and preserve every relevant message, statement, and financial record. She also recommended that I review my credit reports for any accounts I didn’t recognize.
Fortunately, the disputed loan was not listed as my debt. But the document bearing my supposed signature still required investigation.
That evening, Patrick appeared at my house.
His SUV was gone. He had borrowed a friend’s car, and his expensive watch was missing from his wrist.
“Mom, we need to talk.”
I remained standing in the doorway.
“Laura found the paperwork.”
His face changed.
“What paperwork?”
“The loan application with my signature.”
He looked away.
“Mom, I can explain.”
“Then explain.”
He rubbed his face with both hands.
“I was trying to keep everything together. I thought if I could get one more loan, I could pay the other debts and start over.”
“Did you sign my name?”
He didn’t answer.
“Patrick. Look at me.”
He slowly raised his eyes.
“I copied it from an old document,” he whispered. “I never thought anyone would check.”
I felt as though someone had reached inside my chest and squeezed my heart.
“You forged my signature?”
“I wasn’t trying to hurt you.”
“But you did.”
He began crying.
For a moment, I saw the little boy who used to run into my kitchen after school, frightened whenever he’d made a mistake.
But that little boy was gone.
Standing before me was a forty-one-year-old man who had repeatedly chosen dishonesty over responsibility.
“Mom, please don’t report this. I’ll lose everything.”
I took a slow breath.
“You’ve already lost something, Patrick.”
“What?”
“My trust.”
He stood silently while I explained that my attorney was handling the disputed paperwork. I would cooperate with any legitimate investigation, and I would not pretend the signature was mine.
He started crying harder.
“I thought you’d always be there for me.”
“I was there for you. For eighteen months, I paid bills that were your responsibility. I gave you time to find work, reduce your expenses, and rebuild your life.”
“I know.”
“But instead of using that help to become independent, you made yourself dependent on it. And when I asked questions, you told me to disappear.”
He lowered his head.
“I didn’t mean it.”
“Then why did you say it?”
He couldn’t answer.
For the first time in our lives, I didn’t rush to comfort him.
Over the next several weeks, Patrick’s financial problems became impossible to hide. Laura moved temporarily into her sister’s apartment while deciding what to do about their marriage.
The mortgage lender offered Patrick information about hardship assistance, but the bounced payment still had to be addressed. His car had already been repossessed after months of delinquency.
Margaret helped me complete the formal dispute of the questionable document. I changed my passwords, reviewed my accounts, and removed every remaining payment authorization connected to Patrick’s expenses.
I also made one decision that surprised even me.
I sold the large family house where I’d lived since my husband died.
Not because I needed money.
Because I was tired of maintaining a house filled with memories while everyone assumed my retirement savings belonged to them.
I bought a smaller home with a garden, a sunny kitchen, and a porch overlooking a quiet street.
Three months later, Patrick sent me a handwritten letter.
He told me he had started working full-time at a warehouse while taking evening accounting classes. He had entered a debt repayment program and was attending financial counseling.
He didn’t ask for money.
He didn’t blame Laura.
And for the first time, he didn’t blame me.
The final paragraph read:
“Mom, when I told you not to contact us until you were ready to change, I thought you were the problem. I was wrong. You spent years saving me from consequences I needed to face. I’m sorry for what I did, especially for using your name without permission. I don’t expect you to forgive me. I just wanted you to know I’m finally trying to change.”
I read the letter three times.
Then I placed it in my desk drawer.
I wasn’t ready to pretend everything was fine. The legal dispute hadn’t been completely resolved, and rebuilding trust would take more than a letter.
But a few weeks later, I agreed to meet him for coffee.
We sat across from each other at a small café in Columbus.
He looked thinner, older, and strangely more peaceful.
“How’s the new house?” he asked.
“Wonderful.”
He smiled faintly.
“Are you happy, Mom?”
I thought about the eighteen months of stress, the arguments, the guilt, and the endless fear of disappointing my son.
Then I thought about waking up every morning without wondering which of his bills would arrive next.
“Yes, Patrick,” I answered. “I really am.”
He nodded.
“I’m glad.”
We talked for another hour. Not about money, but about work, books, and ordinary things we hadn’t discussed in years.
When the check arrived, Patrick reached for it.
“I’ve got this,” he said.
I looked at him.
“Are you sure?”
He gave me a small smile.
“It’s two coffees, Mom. I can afford two coffees.”
And somehow, that simple moment meant more to me than all the expensive birthday gifts he’d purchased with money I had given him.
As we walked outside, Patrick stopped beside my car.
“Mom, there’s something I’ve wanted to ask you.”
I waited.
“Are you ever going to help me financially again?”
I looked into his eyes.
“No, Patrick.”
He swallowed, then nodded.
“Okay.”
For the first time, that word didn’t mean surrender.
It meant understanding.
My son once told me not to contact him until I was ready to change.
So I changed.
I stopped paying for his lifestyle. I stopped mistaking financial dependence for love. And I stopped allowing guilt to control my decisions.
The mortgage payment bounced. The car was repossessed. His secrets came out.
But the accounts I closed were never the thing that destroyed his life.
They were simply the accounts that had allowed him to avoid facing it.
And sometimes, the greatest gift a parent can give an adult child isn’t another payment.
It’s the chance to finally stand on their own.