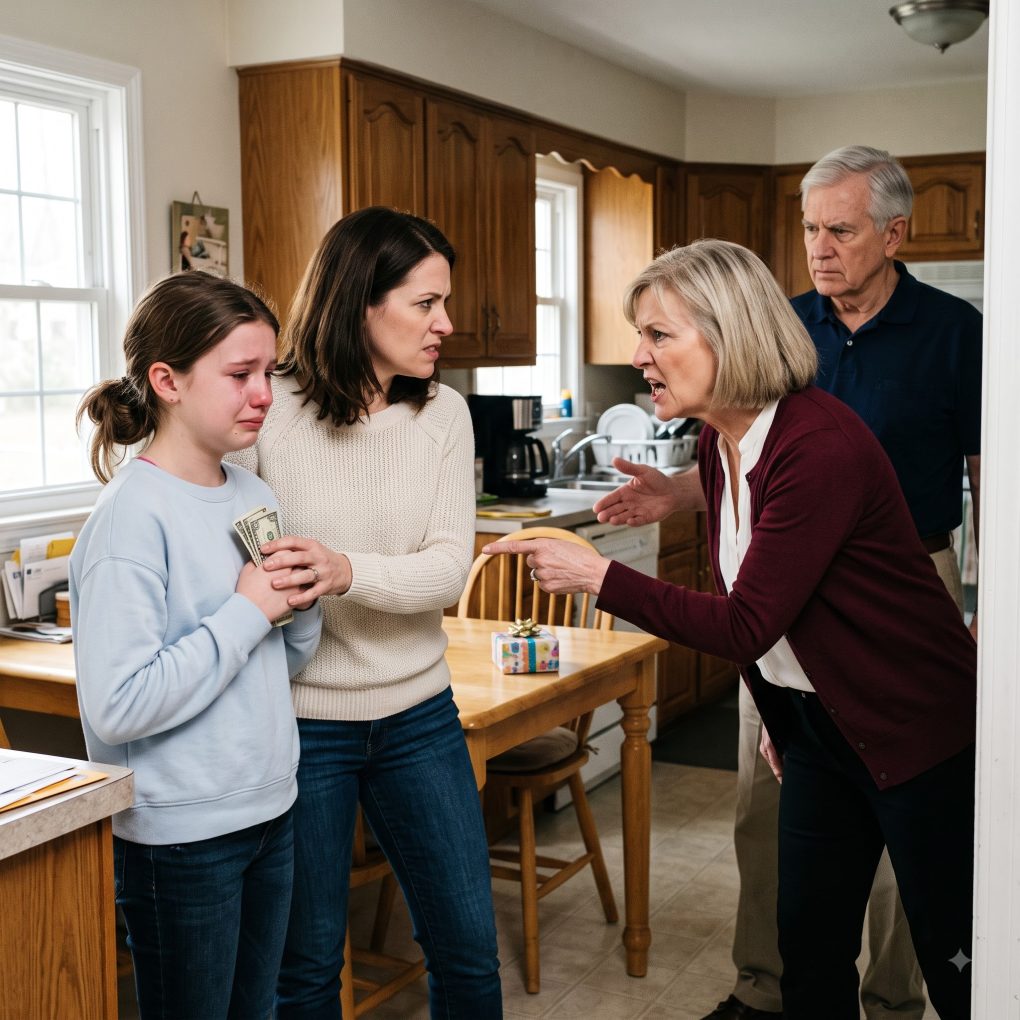
My mother blocked the kitchen door while my twelve-year-old daughter clutched the hundred dollars she had earned walking dogs.
“Pay for your cousin’s gift,” Mom said. “Or YOU ARE NO LONGER FAMILY.”
Emma looked at me. “But that’s for my class trip.”
Dad held out his hand. “Your grandmother asked you a question.”
Across the table, my sister, Brooke, kept scrolling through her phone. Her son’s birthday was Saturday. Apparently, his new gaming system required a contribution from a child who still asked permission to cross the street.
“No,” I said.
Mom’s smile vanished. “Then take her home. Don’t bring her back until she learns what family means.”
Emma folded the bills so tightly her knuckles went white.
I put my hand over hers. “Keep your money.”
Dad stepped aside, muttering that I had always made everything difficult.
In the car, Emma asked, “Can they really stop being my grandparents?”
“They can stop acting like them,” I said. “That doesn’t mean you did anything wrong.”
She stared at the cash. “I would have bought him something.”
“I know, baby.”
Once she was inside our house, I opened my banking app.
For eighteen months, I had paid my parents’ mortgage directly. I also covered their utilities. Dad called it temporary help after his surgery.
I canceled the scheduled payments that had not yet gone through.
Then I sent one message: If Emma isn’t family when she keeps her own money, you cannot claim family when you need mine. Future bills are yours.
The next morning, my phone showed 53 missed calls.
One voicemail came from a number I didn’t recognize.
“This is Melissa Grant from the mortgage servicing department. We need to discuss the borrower authorization submitted under your name.”
I had never submitted one.
Before I could call back, Mom texted a photograph.
It showed a document with my signature at the bottom.
Above it were two words:
ADDITIONAL BORROWER.
They wanted a hundred dollars from my daughter. But the document on my screen suggested they had already demanded something much bigger from me—without asking. And buried among those missed calls was the first clue to what they were desperate to hide.
I enlarged the photograph until my signature filled the screen. It looked right. That was what scared me.
I called the mortgage company using the number on its official statement, not the voicemail. After verifying my identity, the representative transferred me to Melissa. “The application hasn’t closed,” she said. “You’re listed as an additional borrower on a proposed refinance. Your parents told the loan officer you would confirm today.”
“I didn’t apply.” There was a pause, then the sound of typing. “I’m flagging the application. Please send a written statement disputing your participation. Our fraud department will contact you.”
My hands shook as I saved the email she sent. The loan amount was much higher than my parents’ remaining mortgage balance. This wasn’t about a missed utility payment.
Mom called again. This time, I answered. “You embarrassed us,” she said. “Brooke was sitting right there.” “Who signed my name?” “Don’t start using ugly words. We were going to explain.” “Explain what?”
Dad took the phone. “The refinance pays off some expenses. You’ve been making the payments anyway. Nothing would change.” “My legal responsibility would change.” “You’re our daughter.” “Yesterday, mine wasn’t your family.” He hung up.
I checked my credit reports and found a recent mortgage inquiry I didn’t recognize. I froze my credit, changed my email password, and called an attorney named Rachel Kim. Rachel asked one question that made my stomach drop. “Have you ever given them copies of your identification or signed financial documents?”
After Dad’s surgery, Mom had asked me to sign a payment authorization. She said it would let the mortgage company discuss their account with me. I had signed at their dining table. “Find your copy,” Rachel said. “And preserve everything.”
I searched my email while Emma sat beside me, doing fractions. She kept glancing at my face. “Are we in trouble because I said no?” I closed the laptop. “You protected your money. The adults are responsible for what they did.”
That afternoon, Brooke appeared on my porch with an envelope. She looked nothing like the bored woman at dinner. “I didn’t know they put you on it,” she said. “Put me on what?” “The loan. Mom said the house was collateral, and Dad said you’d agreed.”
She pulled out a printed invoice. The proposed cash payout wasn’t for medical bills. It was a deposit on a storefront for Brooke’s business. Then she handed me another page: an email from Mom. If she won’t cooperate, use the authorization. We have her signature.
Brooke swallowed. “There’s something else,” she said. “They’ve already sent a letter to Emma’s school.”
“What kind of letter?” I asked. Brooke held out her phone. Mom had emailed Emma’s school counselor, claiming I was having a breakdown and asking that Emma be released to her after school. She described herself as an authorized emergency contact. She was one. I had listed her years earlier, when I still believed being someone’s grandmother meant wanting that child safe. “They said they needed Emma with them so you’d come over and talk,” Brooke whispered.
I called the school immediately. Emma was home beside me, but tomorrow suddenly felt dangerous. The principal confirmed receiving the email. No pickup change had been approved. I removed both grandparents from the authorized list, arranged a password with the office, and sent written instructions. Then I forwarded the email to Rachel. Brooke started crying. “I thought they were just trying to get you to answer.” “You brought me the evidence,” I said. “Now tell me everything.”
She sat at my kitchen table and finally put her phone away. Her business had been losing money for months. She wanted a storefront because she believed customers would take her seriously with a physical location. Our parents promised to help. When their income wasn’t enough for the refinance, they suggested adding me. “Did you ever ask whether I agreed?” “Dad said he’d talked to you.” “Did you hear me agree?” “No.” That answer stayed between us. Brooke had accepted the version that gave her what she wanted.
The hundred dollars, she admitted, had never been necessary for her son’s present. Our parents had already bought the gaming system on a credit card. Mom wanted everyone to contribute because, in her words, I was teaching Emma to be selfish. “She said if Emma obeyed, you would too.” I looked through the doorway at my daughter, reading on the couch. They had turned a birthday gift into a test of whether they could still control us.
Rachel arranged a meeting at her office the following afternoon. Before we went, I found my original payment authorization in an old email attachment. Its signature matched the refinance document exactly, including a small ink dot where my pen had leaked. Someone had lifted the signature image and placed it on another form. The document Mom photographed wasn’t an approved loan. It was part of an application package waiting on verification. They had sent it to frighten me into finishing what they started.
The 53 calls finally made sense. Canceling my payments had exposed how little money they actually had. Refusing to answer threatened the new loan. Mom’s photograph was supposed to convince me that backing out was already impossible. Rachel helped me submit a fraud report to the lender and a police report with the original authorization, the altered document, the messages, and the school email. She explained that the lender would investigate its own records. We couldn’t decide what charges might follow, but we could make sure my denial was documented.
My parents arrived at her office carrying a bakery box. Mom set it on the conference table. “Emma loves these.” “Emma isn’t here,” I said. Dad sat down heavily. “We’ve all made mistakes.” Rachel placed copies of the two documents in front of him. “My client authorized account discussions. She did not authorize this application.” Mom pushed the pages away. “She was helping us already.” “Helping you wasn’t consent,” I said. Dad stared at the ink dot.
Then Mom turned toward me. “Your sister could lose her chance.” “Then you should have asked me before promising her my income.” “You would have said no.” The room went quiet. There it was. No misunderstanding. No missing conversation. They had known my answer and tried to replace it with a signature. Rachel asked them to leave after making clear that future communication about the dispute should go through her. Mom grabbed the bakery box on her way out. Dad never touched the papers again.
Over the next several weeks, the lender confirmed the application had been withdrawn and that I had no obligation under it. The disputed inquiry was eventually removed from my credit report. The investigation continued separately; I stopped treating every unanswered question as something I had to solve before I could protect Emma. Without my payments, my parents had to review their finances honestly. They listed their house and moved into a smaller rental after the sale. They had enough equity to manage the transition. What they lost was the assumption that my paycheck would always rescue their choices.
Brooke canceled the storefront plan. She sold excess inventory and kept working online. She also returned the gaming system and bought her son a less expensive gift. She asked to apologize to Emma. I asked Emma first. At our kitchen table, Brooke said, “You never owed us that money. I should have spoken up.” Emma studied her. “Did you know Grandma would say I wasn’t family?” “No. But I heard her say it, and I stayed quiet. That was wrong.” Emma nodded. She didn’t hug her. Brooke accepted that.
My parents sent messages through relatives about forgiveness. I gave the relatives one answer: Emma would not be available for another lesson in obedience. Visits were off the table. Any future contact would depend on accountability and on what my daughter felt comfortable with. Mom eventually mailed a letter that said she had been under stress. It never mentioned the signature or the school. I filed it with the other documents and didn’t respond.
In May, Emma went on her class trip with the money she had earned. When she came home, she handed me a little magnet from the museum gift shop. “I paid for it myself,” she said. That night, she asked the question she had carried since the kitchen door. “Are we still a family if they don’t come over anymore?” I moved closer on the couch. “Yes. Family isn’t something you buy for a hundred dollars.” She leaned against me, finally relaxed. I hadn’t shown my parents who was “no longer family” by hurting them back. I had ended their access to the two people they thought they could threaten into submission. And my daughter had kept far more than her hundred dollars.