“This is the most brilliant idea I’ve ever seen, Vanessa. Tell me, how exactly did you come up with it?”
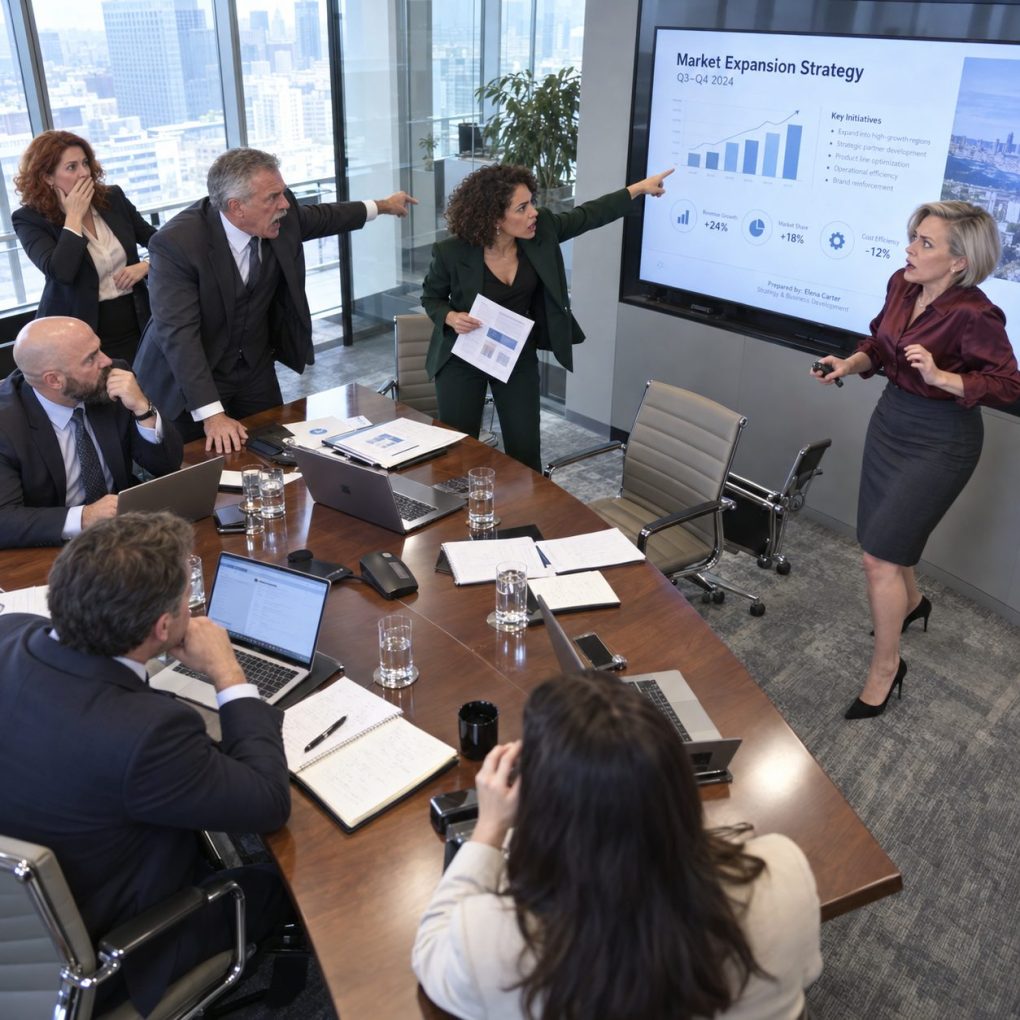
Our CEO, Richard Caldwell, leaned forward as Vanessa Brooks stood beside the conference room screen, smiling like a woman who had just secured her next promotion. Twenty senior executives were watching her presentation, and every slide contained material stolen from my computer, including one critical recommendation I had deliberately left there for her to take.
“Honestly, Richard, it came to me while I was reviewing our operational expenses,” Vanessa replied confidently. “I realized we could save the company nearly eighteen million dollars annually by eliminating unnecessary vendor contracts.”
My name is Emily Parker, and I was thirty-two years old when I finally decided to stop letting my coworker steal my work. For three years, I had been a senior financial analyst at a Chicago-based logistics company called Meridian Freight Solutions, where Vanessa had built an impressive reputation by presenting my research as her own.
She had stolen credit for a warehouse optimization project, claimed responsibility for my forecasting model, and even received a promotion after presenting recommendations I had developed during six exhausting weeks of overtime. Whenever I complained, our department director dismissed my concerns as jealousy and reminded me that Vanessa possessed the leadership qualities I supposedly lacked.
But three weeks before the quarterly executive meeting, I discovered something that changed everything.
While reconciling vendor payments, I noticed repeated invoices from a consulting firm called Northbridge Advisory, totaling more than $2.4 million over eighteen months. The invoices contained vague descriptions, identical approval patterns, and services that nobody in our operations department could confirm receiving.
I reported the discrepancies through our internal compliance channel, attaching the relevant invoices and requesting a confidential investigation. Then I created a separate presentation outlining the suspicious payments and recommending an independent audit rather than immediate contract termination.
Vanessa somehow learned that I was examining vendor expenses.
Two days later, she accessed a shared project folder containing an early draft of my analysis, copied the financial tables, and began presenting the findings to our director as her own discovery. I knew because the file’s revision history showed her activity, and because she repeated a distinctive calculation error I had intentionally left in the draft while testing the model.
Now she was standing in front of the CEO, confidently explaining why Northbridge Advisory should be removed from our vendor network.
Richard studied the slide before asking one question.
“Vanessa, did you personally verify that Northbridge provided no legitimate services?”
“Absolutely,” she answered without hesitation. “I investigated every invoice myself.”
I watched Richard’s expression change.
He placed his pen on the table and turned toward our chief legal officer.
“That’s interesting,” he said quietly. “Because Northbridge Advisory is already the subject of a confidential investigation.”
Vanessa’s smile faltered.
Then Richard looked directly at me.
“Emily, would you like to explain why her presentation contains information from your restricted compliance report?”
For several seconds, Vanessa stood motionless beside the screen, her fingers tightening around the presentation remote as every executive turned toward me. I could see her trying to understand how Richard knew about my compliance report, especially because she had spent the previous week telling our director that I had contributed nothing meaningful to the project.
“I submitted the original report eighteen days ago,” I answered calmly. “It included the vendor invoices, payment comparisons, and an audit recommendation, but I never authorized Vanessa to present that investigation as her independent work.”
Vanessa recovered quickly, raising her chin and forcing a confident smile.
“Emily and I collaborate all the time,” she insisted. “I’m sure she’s simply confused about who contributed which sections.”
Our chief legal officer, Margaret Ellis, opened a folder in front of her.
“Then perhaps you can explain why your presentation contains a calculation that appeared only in Emily’s preliminary working file,” she said. “The corrected figures were submitted to compliance before your presentation was created.”
Vanessa glanced at the screen.
The slide claimed that canceling certain contracts would save eighteen million dollars annually, but the number included expenses that could not legally or operationally be eliminated. I had deliberately left that preliminary estimate in an early draft while testing alternative assumptions, and the final report explained why the realistic savings could be substantially lower.
“The eighteen-million-dollar figure was never a verified savings estimate,” I explained. “It was a preliminary scenario, clearly marked for review in the working file, and Vanessa copied it without understanding the underlying assumptions.”
Richard turned toward Vanessa.
“Did you independently validate the calculation before recommending that we terminate these contracts?”
She hesitated.
“I relied on the numbers available to our department.”
“That wasn’t my question.”
The room became painfully quiet.
I had expected Vanessa to deny taking my work, but I hadn’t anticipated how aggressively she would defend a conclusion she couldn’t explain. Instead of acknowledging the error, she accused me of sabotaging the presentation by placing misleading information in a shared folder.
“Emily knew I was preparing this for the executive team,” she snapped. “If those figures were wrong, why didn’t she warn me?”
I looked directly at her.
“Because you never told me you were using my draft, and you removed my name from the material before presenting it.”
Margaret asked the meeting to pause while she reviewed a document on her laptop. The company had retained system logs showing that Vanessa downloaded my preliminary spreadsheet, created a new presentation from its contents, and deleted several comments identifying the unfinished calculations.
Those records alone did not prove every accusation I had made about her previous behavior, but they established exactly how this presentation had been assembled. More importantly, the compliance team had already instructed senior leadership not to take action against Northbridge until the vendor investigation was complete.
Richard closed his notebook.
“Vanessa, you’ve represented unverified financial information as independently confirmed research,” he said. “And you’ve recommended terminating contracts that our legal department is currently reviewing.”
Vanessa’s face flushed.
“I was trying to protect the company!”
“Then why did you tell us you personally investigated every invoice?”
She didn’t answer.
Our department director, Thomas Reed, finally spoke, suggesting that the discussion should continue privately because Vanessa’s reputation was being damaged in front of senior leadership. Richard turned toward him with an expression I had never seen before.
“Thomas, you approved this presentation,” he said. “Did you know Emily had already filed a compliance report?”
Thomas stared at the table.
His silence told everyone more than an explanation could have.
Margaret then revealed that the vendor investigation had uncovered possible conflicts of interest involving Northbridge’s invoices and a senior manager responsible for approving them. She carefully avoided naming anyone before the review was complete, but Richard immediately ordered that no disputed contracts or records be altered without legal authorization.
Vanessa was instructed to surrender her access badge to HR pending a formal investigation into document misuse and misrepresentation. Thomas was also removed from responsibility for the vendor review, while the executive meeting was adjourned.
As everyone began leaving, Vanessa stepped toward me.
“You planned this,” she whispered furiously. “You wanted to destroy my career.”
I gathered my notebook and stood.
“No, Vanessa. I wanted my work evaluated honestly, and you kept making that impossible.”
She stared at me with tears gathering in her eyes.
Then Margaret approached with another document.
“Emily,” she said, “there’s something else we found in the financial records, and I think you need to see it before you leave.”
Margaret led me into a smaller conference room overlooking downtown Chicago, where two members of the company’s compliance team were waiting. On the table sat a folder containing eighteen months of vendor payment records, internal approvals, and a series of emails that had never appeared in the material Vanessa presented.
“We’ve discovered that the Northbridge invoices were approved through an exception process controlled by Thomas Reed,” Margaret explained. “And some of the supporting documentation appears to have been created after the payments were authorized.”
I stared at the approval records, recognizing Thomas’s name beside several transactions that had previously seemed routine. He had repeatedly discouraged me from investigating vendor expenses, and I suddenly understood why he had been so eager to promote Vanessa’s inaccurate presentation instead of acknowledging my confidential report.
“Are you saying Thomas was stealing money?” I asked.
“I’m saying the evidence raises serious concerns that require an independent investigation,” Margaret replied. “We aren’t going to accuse anyone of criminal conduct until the facts have been established.”
The company retained an outside forensic accounting firm and instructed relevant employees to preserve financial records, emails, and communications. Over the following weeks, investigators interviewed department managers, reviewed payment approvals, and compared Northbridge’s invoices with contracts and services that could actually be verified.
I cooperated fully, providing my original spreadsheets and explaining how I had identified the irregularities. Investigators also examined Vanessa’s previous presentations, many of which contained portions of my work that had been copied without proper attribution.
The discovery was humiliating for Vanessa, but the findings surrounding Thomas were considerably more serious.
The independent review established that Thomas had knowingly approved unsupported invoices from Northbridge, whose principal was a longtime personal associate he had failed to disclose. Financial records also revealed payments from that associate to a separate business in which Thomas held an ownership interest, creating evidence of a concealed financial relationship.
The company referred its findings to the appropriate authorities and began pursuing recovery of the disputed payments through legal action. Thomas’s employment was terminated, although any criminal liability would depend on a separate investigation rather than the company’s conclusions alone.
Vanessa’s situation was different.
The investigators found no evidence that she had received money from Northbridge or knowingly participated in Thomas’s financial misconduct. However, they confirmed that she had repeatedly claimed credit for work performed by other employees, altered presentation histories, and made false statements about independently verifying financial conclusions.
HR terminated her employment for serious violations of company policy.
I expected to feel victorious when Margaret informed me, but instead I remembered the countless evenings I’d worked alone while Vanessa accepted applause for projects she barely understood. Losing her job didn’t return those hours, and it couldn’t erase how small I’d felt every time my manager dismissed my concerns.
Two days later, Richard requested a private meeting.
“I reviewed your performance history, Emily,” he began. “You were responsible for several projects that significantly improved our operations, but the recognition repeatedly went elsewhere.”
I nodded, unsure what to say.
“Thomas recommended Vanessa for promotion twice while describing you as technically capable but unsuitable for leadership,” Richard continued. “Those evaluations were neither balanced nor supported by the documented work.”
He explained that the company would correct my personnel records, formally acknowledge my contributions, and review the compensation decisions affected by the inaccurate evaluations. The board had also approved stronger controls for project ownership, financial reporting, and employee complaints.
Then Richard offered me a newly established position as director of financial controls and analytics.
The salary was considerably higher, but what mattered most was that the role came with direct reporting access to the chief financial officer and authority to recommend independent reviews. For the first time in my career, someone was offering responsibility based on the work I had actually performed.
I accepted after reviewing the position’s responsibilities and discussing the terms.
Three months later, I received an unexpected email from Vanessa.
She said she had struggled to find another senior position and regretted how she’d treated me, although she also believed Thomas had encouraged her to compete for recognition at any cost. She asked whether I would consider writing a recommendation that emphasized her presentation skills.
I read the message several times before replying.
I told her I hoped she could rebuild her career, but I couldn’t honestly recommend her professional integrity based on our experience. I also explained that while Thomas had created an unhealthy department, he hadn’t forced her to erase my name from presentations or claim she had completed work she hadn’t done.
She never answered.
By the following spring, our new financial controls team had completed its first company-wide audit, improved vendor verification procedures, and introduced clear documentation standards for collaborative projects. Our department’s financial results improved, and employees who had previously been afraid to report concerns began bringing questions directly to us.
One afternoon, a young analyst named Jordan entered my office holding a presentation he had prepared for senior management. He nervously asked whether I wanted him to remove the names of the junior analysts who had helped build the model.
“Why would you remove them?” I asked.
He shrugged.
“That’s what people used to do here.”
I turned the presentation toward him and pointed to the title slide.
“Then we’re going to do things differently,” I said. “Everyone who contributed should receive the credit they’ve earned.”
That afternoon, Jordan presented his analysis with every contributor properly acknowledged. Watching the team receive recognition together felt more satisfying than seeing Vanessa embarrassed in front of the CEO.
Looking back, I understand that the presentation I allowed Vanessa to steal wasn’t a magical trap or a fabricated disaster designed to ruin her. It was an unfinished analysis she should never have claimed as her own, containing assumptions she would have recognized as unreliable if she’d actually performed the work.
Vanessa thought stealing my ideas would take her into the executive suite, but the one presentation she wanted credit for exposed everything she had spent years hiding.
And the lesson I learned was even more important.
You don’t always have to fight someone who keeps taking credit for your work. Sometimes, the most powerful thing you can do is make sure the truth has a documented path to the people who need to see it.