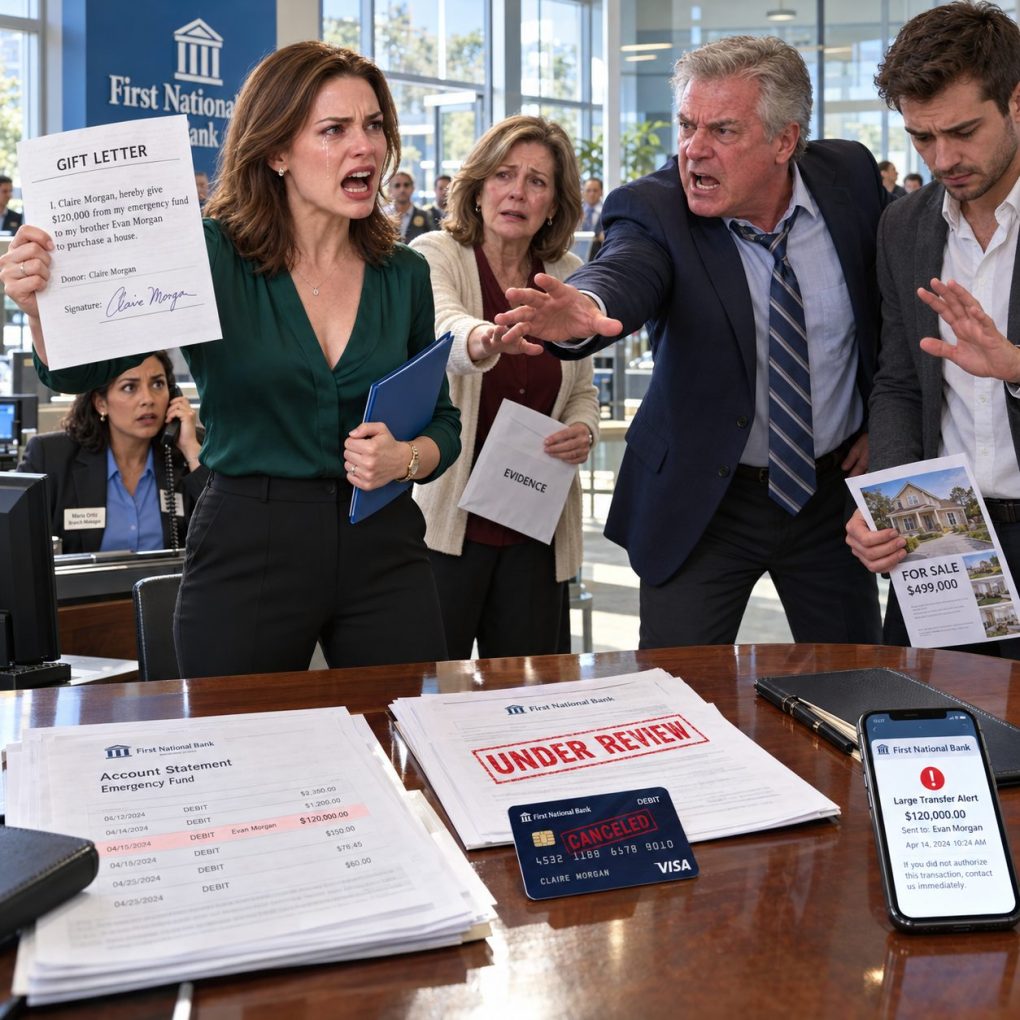
My father slid a blue folder across the kitchen table and kept his palm on it until I looked up.
“I used your emergency fund to buy your brother a house,” he said. “No arguments.”
Evan lifted his coffee mug as if Dad had announced a promotion. Mom kept smoothing the same corner of her napkin.
Inside the folder lay a listing for a $312,000 house, a mortgage estimate, and a bank confirmation. Dad’s thumb covered the transaction status.
The amount was $120,000.
I had earned every dollar, and nobody had asked me.
“That’s my money,” I said.
Dad leaned back. “And he’s your brother. You don’t need three bedrooms to sit alone counting invoices.”
I was thirty-one, a freelance bookkeeper, and saving to buy a small townhouse. That fund covered illness, unpaid client bills, and the possibility of starting over. Six years of work had put $148,000 between me and a crisis.
Evan was twenty-eight. According to Dad, his management job was steady, but rent was preventing him from getting ahead.
“You could have asked,” I said.
“You would have made it complicated,” Evan replied.
Mom finally spoke. “Your father thought telling you afterward would spare everyone a fight.”
The blue folder had belonged to me since high school. I’d left it here after surgery three years earlier, with account information and a temporary authorization allowing Dad to pay my bills for thirty days.
Apparently, he’d kept more than the folder.
“Did you log in as me?” I asked.
Dad tapped the listing. “Look at that kitchen. Your brother deserves a proper home.”
My own kitchen had one drawer that wouldn’t close. Last month, I’d shown Mom photographs of a townhouse ninety minutes away. She had asked who would handle Dad’s shop invoices if I moved.
I had laughed because I thought she was joking.
Evan pushed a second page toward me. “Closing is Monday. Don’t embarrass us over this.”
I reached for the confirmation. Dad caught my wrist, then released it when I looked directly at his hand.
“Be sensible, Claire.”
For years, sensible had meant paying Evan’s overdue insurance, doing the shop’s books without charge, and apologizing when I resented either obligation. I kept hoping generosity would earn me a place that didn’t depend on being useful.
I stood.
“Fine. Just wait.”
Dad smiled, mistaking quiet for surrender.
In the driveway, I called the bank’s fraud number from its official app. I reported an unauthorized transfer, secured my login, and asked them to stop anything still pending. The representative promised an urgent review.
Ten minutes after Dad handed me the folder, my phone rang.
“Claire Morgan? This is Maria Ortiz, your branch manager. We’ve held the wire before release.”
My knees loosened with relief.
Then she asked, “Did you also authorize the monthly transfers to the account ending in 8126?”
Those four digits matched the account on Dad’s personal checks.
“What monthly transfers?”
“I’ve opened the history,” Maria said. “Before I read it, are you somewhere private?”
Part 2
“I’m in my car,” I told Maria. “Please read it.”
“Six hundred dollars every month for twelve months. Seven thousand two hundred altogether. Today’s wire is separate.”
I stared at my parents’ kitchen window. Mom stood behind the glass, watching me.
Maria explained that the $120,000 wire had triggered manual review because of its size and unfamiliar destination. Dad had submitted my expired authorization as supporting paperwork. My call reached them before the funds left the bank.
The smaller transfers had gone through earlier. Their legitimacy would require a separate investigation.
I asked whether Dad was an owner of the account. Maria confirmed he wasn’t. His name appeared only in the old authorization file. Having my credentials had given him access, not ownership or continuing consent.
“I didn’t authorize any of them,” I said.
Maria sent statements through the bank’s secure portal. Twelve identical withdrawals marched down the screen. Statement notifications had been changed to Dad’s email address while I was recovering from surgery.
I had trusted the balance on my budgeting spreadsheet, updating deposits while assuming nobody else could spend the savings. I should have checked the actual statements. That mistake hadn’t given Dad permission.
“There’s another document,” Maria said. “A gift letter submitted with the wire request.”
The letter claimed I was giving Evan $120,000, expected no repayment, and understood that I would acquire no interest in his house.
Underneath was an imitation of my signature.
I returned to the kitchen with the document open on my phone.
“Who signed this?”
Dad glanced at it. “The lender needed routine paperwork.”
“That’s not an answer.”
“I signed for you. You gave me authority.”
“For thirty days. Three years ago.”
Evan set down his mug. “He was helping both of us.”
“Where did the monthly money go?”
Dad folded his arms. “Your brother needed support. I wasn’t going to let him crawl to you every month.”
Mom whispered, “I thought you knew.”
“Did you ever ask me?”
She looked away.
I photographed every page in the folder. Then I told Maria to cancel the pending wire, remove all saved access, restore my contact details, and flag any further instruction from my father for verification directly with me.
I changed my email password and signed out other devices. At Maria’s suggestion, I also checked my credit reports and placed protective freezes. No unfamiliar loan appeared, but I preserved the reports.
By afternoon, the wire was canceled. My available savings were $140,800. The missing $7,200 remained disputed.
Evan called from the lender’s office.
“They need you to confirm the gift. Dad says the bank misunderstood.”
“The bank understood.”
He forwarded the mortgage coordinator’s email, apparently hoping the deadline would frighten me. Beneath it was his earlier reply, sent Wednesday with the gift letter attached.
Claire won’t ask for repayment. Dad has handled her account for years. Please proceed.
Evan had told me that morning he knew nothing about Dad’s access.
“You helped sell them the lie,” I said.
“I thought you’d agree once you saw the house.”
When I refused, his voice softened.
“I’m sorry it happened this way. Let the closing happen, and we’ll talk about boundaries afterward.”
“You want my apology to cost $120,000.”
He hung up.
I wrote down each conversation while I could remember the wording. Then I emailed Evan asking him to preserve the lender correspondence. He replied that he was busy handling an employment issue. Dad called it paperwork, but that phrase stayed with me.
That evening, Dad told our relatives I had promised Evan a gift and withdrawn it out of jealousy. An aunt called me selfish before asking a single question.
I sent her the expired authorization and disputed gift letter. She stopped answering, which was better than another lecture.
Dad then demanded a meeting at the bank Monday morning. He wanted Maria to explain everything with the family present, certain that witnesses would make me retreat.
I accepted, provided Maria agreed and nobody brought additional relatives.
On Monday, I arrived carrying the blue folder. Mom waited outside Maria’s office, holding a sealed white envelope.
“Don’t sign anything,” she whispered.
Then Dad opened the door.
Part 3
Dad opened the door wider, and Mom followed me into Maria’s office. Evan sat beside the desk with the house listing balanced on his knees.
I put the blue folder between us. Mom kept the white envelope in her lap. “We’ve had a misunderstanding,” Dad began. “Claire gets anxious about money.”
Maria turned toward me. “Do you authorize this gift or any of the twelve earlier transfers?”
“No.”
“Then the wire remains canceled. Your father has no current authority over this account. We can discuss the disputed withdrawals and documentation.”
Dad pushed forward a fresh gift letter. “Sign this, and the problem disappears.”
“Your problem,” I said. Evan’s jaw tightened. “The seller can keep my earnest money if financing falls apart.”
“How much?”
“Twenty-four hundred.”
“Where did it come from?”
He looked at Dad. Maria wrote something down.
Dad leaned toward me. “Do you want your brother humiliated? The whole family knows about that house.”
There it was: my money had become a public promise without my participation. Now my refusal was supposed to break it.
“You announced a gift I hadn’t made.”
“After everything we spent raising you.”
I opened the folder to an old college repayment statement. I’d found it among the papers Dad had returned reluctantly that morning. “My scholarship covered tuition. I borrowed for housing and paid that loan myself. You keep telling people you sacrificed your retirement to educate me.”
“We fed you,” Dad snapped.
“I was your child.”
Mom looked up. “Richard, stop.”
He stared at her as if she had spoken out of turn. She turned to me. “I saw the first statement last year. I asked him what the transfers were. He said you preferred helping quietly.”
“And you believed him?”
“I chose to. Asking you would have meant admitting something was wrong.”
The admission hurt more than her earlier excuse. It also finally sounded true. “When you asked about my townhouse, were you worried about me?” I asked.
“I was worried about managing without you,” Mom said. “I let your father call that concern.” Evan stared at her. She had never contradicted Dad with both children watching. I wanted to reach for her hand. Instead, I waited. One honest sentence couldn’t repair twelve months in which she had quietly watched my money disappear.
Dad dismissed her with a wave. “Helen doesn’t understand accounts.”
“I understand asking permission,” Mom said.
She took my old emergency debit card from her purse and placed it beside the folder. “He told me to keep this safe. I should have returned it when you recovered.”
Maria confirmed the card was already canceled. I took it anyway. Getting it back settled one small piece of what they had kept from me.
Evan slid the listing closer. “I can pay you back eventually.”
“That letter says you won’t.”
“We can change the letter.”
“Then it’s a loan. Tell your lender the truth and see whether you qualify.”
He went silent. I pointed to the mortgage estimate. “You said your job was steady. Why is your employment verification still outstanding?”
Dad answered too quickly. “Administrative delay.”
Mom tightened her fingers around the envelope.
Maria explained that the bank would preserve the submitted paperwork. A report about the false signature was my decision, separate from whether my relatives repaid the missing money.
Dad rose.
“If you make this official, don’t come crying when you need family. You wanted independence. Enjoy it.”
For a second, I saw every holiday chair becoming empty.
Then Mom set the envelope on the desk.
“Before you decide, read this.”
“Helen,” Dad warned.
She held my gaze. “I kept quiet because I was afraid he would blame me. That made you pay for my fear.”
Inside were folded pages and a photograph of a message exchange.
Evan reached for them, then stopped when Maria shifted forward.
I lifted the first page. Mom’s handwriting filled the margin beside a date six weeks earlier.
“What happened that day?” I asked.
Evan lowered his eyes.
Part 4
“I lost my job,” Evan said.
The first page was his separation notice from the home improvement store where he had managed a department. It cited repeated attendance violations. The date was six weeks before our meeting.
“You told me you were taking vacation,” I said.
“I thought I’d find something before closing.”
His mortgage application still listed his former salary. The lender had asked for final employment verification, and Dad had been trying to push the down payment through before that check happened.
I turned to the photographed messages. Mom had printed the exchange from her own phone.
Evan had written that he couldn’t afford the payments without another job. Dad had answered that a large gift would keep the mortgage manageable. Then, beneath Mom’s question about asking me, came another message.
If Claire has less sitting there, she’ll postpone moving. She won’t walk away from the shop when we’re helping Evan get established.
I read it twice.
The theft hadn’t merely favored my brother. It had been designed to leave me too frightened to make my own plans.
Mom’s handwritten note described the conversation she’d overheard afterward. Dad wanted me to keep doing the shop invoices and payroll. Evan could learn the business while living nearby in a house purchased largely with my savings.
“You were building his future with the money that made mine possible,” I said.
Dad looked at Maria. “These are private family discussions.”
“So was my account,” I replied.
He sat down again.
Maria asked whether I wanted a few minutes outside. I shook my head. For once, I wanted everyone to hear the same words at the same time.
“Explain the monthly transfers.”
Dad stared at the canceled card.
“Evan was short. I helped.”
“With my money. Where did all $7,200 go?”
After several evasions, the amounts became clear. Dad had moved $600 each month into his personal checking account, the one ending in 8126. From each transfer, $450 went toward Evan’s expenses. The remaining $150 paid Dad’s credit card.
Over twelve months, Evan had received $5,400 and Dad had used $1,800. Evan had saved $2,400 of his portion for the earnest deposit. The rest had covered car payments and other bills.
Evan had originally believed Dad was using his own money. Wednesday, when Dad prepared the gift letter, he learned the account belonged to me. He sent the mortgage coordinator his reassurance anyway.
“I thought stopping then would waste everything we’d done,” Evan said.
“You mean everything you’d spent.”
He nodded without looking up.
Dad admitted he had kept the login details from my surgery folder. The temporary authorization had expired, but the information hadn’t vanished. He had changed the notification address during my recovery and never restored it.
For two years, he had apparently left the savings alone. Then my brother began missing payments. Dad discovered that small transfers attracted little attention, and my silence became, in his telling, permission.
“I assumed you’d noticed,” he said.
“You sent the statements to yourself.”
He had no answer.
I had continued using a spreadsheet built from deposits and interest estimates. Since I rarely withdrew money, I hadn’t compared it with actual statements. I remembered feeling proud that the fund was growing while Dad quietly reduced it.
That carelessness belonged to me. The deception belonged to him. Both facts could exist without canceling each other.
“Why didn’t you help Evan yourself?” I asked.
Dad spread his hands. “We’re retired. We don’t have your earning potential.”
Mom removed one last page from the envelope: a recent statement from their joint brokerage account. Dad had shown it to her while discussing their taxes.
The balance was just over $42,000.
Their house was paid off. Together, their pensions brought in $3,200 each month, and Dad still earned additional money from the repair shop. They weren’t wealthy, but they weren’t facing eviction or hunger.
Dad tapped the brokerage statement. “That’s retirement security.”
“And mine was emergency security.”
He flinched at the repetition.
The $120,000 wasn’t a price the family could comfortably pay. Dad had chosen it because reducing Evan’s proposed loan to $192,000 made the purchase look achievable on his former income.
Even before losing his job, Evan had brought home about $3,600 monthly. The mortgage estimate, taxes, and insurance approached $1,650. Utilities, his car payment, existing debt, and ordinary living expenses left almost nothing.
His delivery work now earned roughly $1,900 in a good month. A house wouldn’t fix that arithmetic. It would give the arithmetic an address.
“You needed a cheaper plan,” I told him. “You decided I should pay for pretending otherwise.”
Dad pulled the fresh gift letter toward me again.
“Enough. You can still save this. Let him close, give him time to find work, and we’ll restore what you need later.”
“From what income?”
“Families don’t demand guarantees.”
“Your lender does.”
He switched tactics.
“All right. Take an interest in the house. We’ll put your name somewhere. You won’t lose anything.”
“You cannot repair a false gift by inventing another arrangement at this desk.”
Evan looked at the listing. “Dad, she said no.”
It was the first time either man had treated the word as something that might end a discussion.
Dad ignored him.
“Your mother will suffer if you report this. People talk. I’ll have to sell the shop. She’ll lose the life we built.”
Mom’s eyes filled, but she stayed seated.
“Don’t use me,” she said. “I already let you do that once.”
Dad turned back to me.
“Choose carefully, Claire. A bank balance won’t visit you in the hospital.”
Three years earlier, he had visited every evening after my surgery. He had brought soup in a thermos and adjusted my pillow. Those memories were real. So were the passwords he’d carried away.
I could keep the tenderness without giving it authority over everything that followed.
“I wanted a family I could trust when I was vulnerable,” I said. “You used that vulnerability to get access. Then you tried to keep me vulnerable.”
I moved the gift letter out of my way.
“Maria, I want copies of everything submitted under my name. I’ll make the report. I won’t withdraw it in exchange for the money.”
Dad stared at me.
I asked Maria to record my denial of authorization, preserve the expired document and signature, and tell me how to obtain the transaction records. Then I called the mortgage coordinator using the number on Evan’s forwarded email.
With Evan beside me, I stated that I had never offered the gift and had not signed the letter. I followed the call with an email attaching my written denial. Evan sent his own correction about his employment.
There would be no closing that morning.
Dad stood so abruptly his chair struck the wall.
“You’ve destroyed your brother’s chance.”
Evan folded the listing.
“I lost my job. I lied. Stop making that her fault.”
It wasn’t absolution. It was a beginning, spoken too late to erase his earlier choice.
Dad left without taking the fresh gift letter. I watched the office door close and felt the familiar urge to follow him, soften my words, and buy back the afternoon.
Instead, I gathered my documents.
Outside, Mom asked if she could sit with me on the bench near the parking lot. I agreed to ten minutes.
“Why didn’t you call me?” I asked.
She pressed her palms together.
“Because I knew you’d ask a question I couldn’t answer honestly. Whether I was protecting you or protecting myself from your father.”
“You told him where I wanted to move.”
“Yes. I complained about losing your help. I didn’t know he would do this, but I helped make your independence sound like abandonment.”
That was the apology I had needed: specific enough to have edges.
“You don’t get updates about my money anymore,” I said. “And you don’t carry messages from Dad.”
“I understand.”
“Understanding isn’t the same as doing it.”
She nodded.
Evan waited beside my car. When Mom left, he handed me the folder’s remaining pages and my spare apartment key. Dad had given it to him months earlier for an errand; he had never returned it.
I took the key. The locks would change anyway.
“I thought you always landed on your feet,” he said.
“Because you didn’t see the bills afterward.”
“Dad said you liked being the dependable one.”
I remembered being seventeen, hearing that I was mature while Evan was allowed to be difficult. I had mistaken the compliment for love without conditions. Eventually, I began volunteering before anyone asked, terrified that saying no would expose how little else they wanted from me.
“I liked being loved,” I said. “I kept confusing the two.”
He wiped his face with his sleeve.
“I can’t repay everything today.”
“Then make a plan you can actually follow.”
That afternoon, I filed a police report and supplied the documents. I also completed the bank’s dispute forms. Maria had stopped the large wire, but she couldn’t declare the older withdrawals recovered or decide criminal responsibility. Those processes took time.
I hired an attorney to review the records and put repayment terms in writing. Dad acknowledged using $1,800 and paid that amount after receiving the formal demand. Evan acknowledged receiving $5,400 and agreed to twelve monthly payments of $450.
The agreement recorded the full loss and each payment so any bank reimbursement could be reconciled without collecting twice. Ultimately, the missing money came back through restitution, and the bank closed the dispute with those payments documented.
The seller kept Evan’s $2,400 deposit under the purchase agreement after the financing deadline passed. I wasn’t a party to that agreement, owned no part of the house, and had no mortgage obligation. The false gift letter was withdrawn from the loan file.
Dad wanted me to cover the forfeited deposit as a gesture of goodwill. I declined.
I ended my unpaid work for the shop. I provided the existing bookkeeping files, a final reconciliation, and a written handover date. Dad could hire someone, do the work himself, or reduce his business. My departure didn’t erase his records or transfer his responsibilities to Mom.
My laptop, original documents, and remaining belongings came out of their house the following Saturday. Evan carried the boxes while Mom checked rooms against my list. Dad stayed in the garage.
When I went in for a box of tax records, he set down his wrench.
“You were always the capable one,” he said. “Evan needed encouragement.”
“He needed you to let him face consequences.”
“My father never helped me. Everything was a test. I wasn’t going to raise a son who felt that alone.”
“You raised a daughter who believed she’d be alone unless she helped everyone else.”
He looked toward the open door, where Evan was loading my car.
“I didn’t think you’d leave us over money.”
“I was planning a move before you took it. Leaving town wasn’t leaving the family. You made staying connected cost me control of my life.”
For a moment, his face changed. Then he asked whether I would at least finish the next month’s payroll. I picked up the box and went outside.
I returned the shop key and kept no family card. My bank account moved to a new number with instructions requiring verification through my own contact details. The old card was cut up. My apartment locks changed.
When Dad sent a message calling me vindictive, I replied once: communication about restitution or records could go through the attorney. Personal contact would require a direct acknowledgment of what he had done and an end to insults.
He called that blackmail. I stopped answering.
Three weeks later, Evan started work at a distribution warehouse. His first paycheck was smaller than his former salary, but regular. He moved into our parents’ spare room, paid them rent, and sold his expensive car.
He showed me his new budget because our repayment agreement required an income update. His monthly take-home pay was about $2,700. Four hundred went to our parents for his room, four hundred fifty to restitution. A used car bought with the proceeds of his sale reduced his transportation costs. The numbers left room for food, insurance, and modest savings. There was no imagined raise filling the gaps. When overtime became available, he used some of it to clear his remaining card balance. He never asked me to celebrate the plan as generosity.
He set up the $450 monthly payment before buying another vehicle. For the first time, inconvenience stayed with the person whose decisions had caused it.
Mom began calling on Sunday afternoons. When she slipped into “your father misses,” I ended that call calmly. The next week, she apologized without finishing his message.
She stopped asking about my account. She asked about a client project, a recipe, the book beside my bed. Sometimes our conversations were awkward. Sometimes I cried afterward because ordinary interest felt unfamiliar.
Dad’s case moved slowly. Investigators compared the submitted signature, the expired authorization, bank records, and the family’s statements. Evan provided his email correspondence; Mom provided her messages. Repayment didn’t make the false documents disappear.
Months later, Dad accepted a plea concerning the forged paperwork and received probation. I gave a statement describing both the financial harm and his attempt to prevent my move. I didn’t ask the court to preserve his reputation by erasing my experience.
He paid what he owed, but still insisted that his intentions should settle everything. They didn’t. Our contact stayed limited.
By the following spring, I bought the townhouse I’d shown Mom. I chose a smaller down payment than I’d once planned so I could retain a substantial emergency reserve. A home inspection identified a faulty water heater; I negotiated the repair instead of pretending desire made the cost irrelevant.
On moving day, Mom arrived at the agreed time with bread and no surprise guests. Evan came separately, after asking permission. He assembled a bookshelf, then handed me the remaining screws rather than leaving me to discover what was missing.
His last restitution payment arrived twelve months after the bank meeting. I confirmed the balance was zero and kept the records. Repayment restored money. Our relationship recovered more slowly.
I invited him to dinner occasionally. I didn’t lend him money, share account access, or accept Dad’s messages through him. He stopped asking me to. That mattered more than the speeches he’d once made about family.
Fourteen months after Dad slid the folder across the table, I placed that same blue folder in my own kitchen drawer. It now held my closing papers, inspection receipts, and a handwritten list of repairs I had chosen.
The drawer shut properly.
Outside, rain tapped the window. My dinner simmered on the stove, and there was enough money set aside to handle whatever tomorrow brought.
Nobody had decided how I would spend it.
I set one clean white plate on the table and sat down in the home I had chosen for myself.