The day our divorce became final in Chicago, Richard pressed a bank card into my hand and said, “There’s three thousand dollars on it. Use it if you need it.” I never spent a cent. Five years later, at sixty-five, I finally inserted that card into an ATM. The balance on the screen made my knees buckle.
My name is Eleanor Hayes, and Richard had been my husband for thirty-two years.
Our divorce was not explosive.
No affair.
No screaming courtroom.
Just the slow collapse of two people who had stopped knowing how to reach each other.
Richard had built a successful commercial flooring company.
I had spent most of our marriage raising our two children, managing the house, and later working part-time at a library.
By the time we divorced, our children were grown.
The settlement gave me the condo I already lived in, part of our retirement accounts, and enough savings to remain secure if I was careful.
Richard kept the business.
As we left the courthouse, he stopped beside me on the sidewalk.
“I know the settlement is done,” he said.
Then he handed me a plain gray debit card.
“There’s three thousand dollars on it. Use it if you need it.”
I almost refused.
But his expression stopped me.
Richard had never been good at emotional sentences.
Money was often the language he used when words failed.
So I took it.
Then I put the card inside an envelope and locked it in my desk.
I never activated online banking.
Never checked the balance.
Never used it for groceries, repairs, or emergencies.
For five years, life moved forward.
Richard and I spoke occasionally about our children.
Birthday messages.
Holiday logistics.
Nothing more.
Then, three months after my sixty-fifth birthday, my furnace failed.
The replacement estimate was $8,600.
I had the money, but taking that much from savings frightened me.
That night, while searching through documents, I found the envelope.
The card was still inside.
I smiled when I remembered Richard saying there was three thousand dollars on it.
Even if the account had fees, I thought perhaps enough remained to soften the furnace bill.
The next morning, I walked to my neighborhood bank.
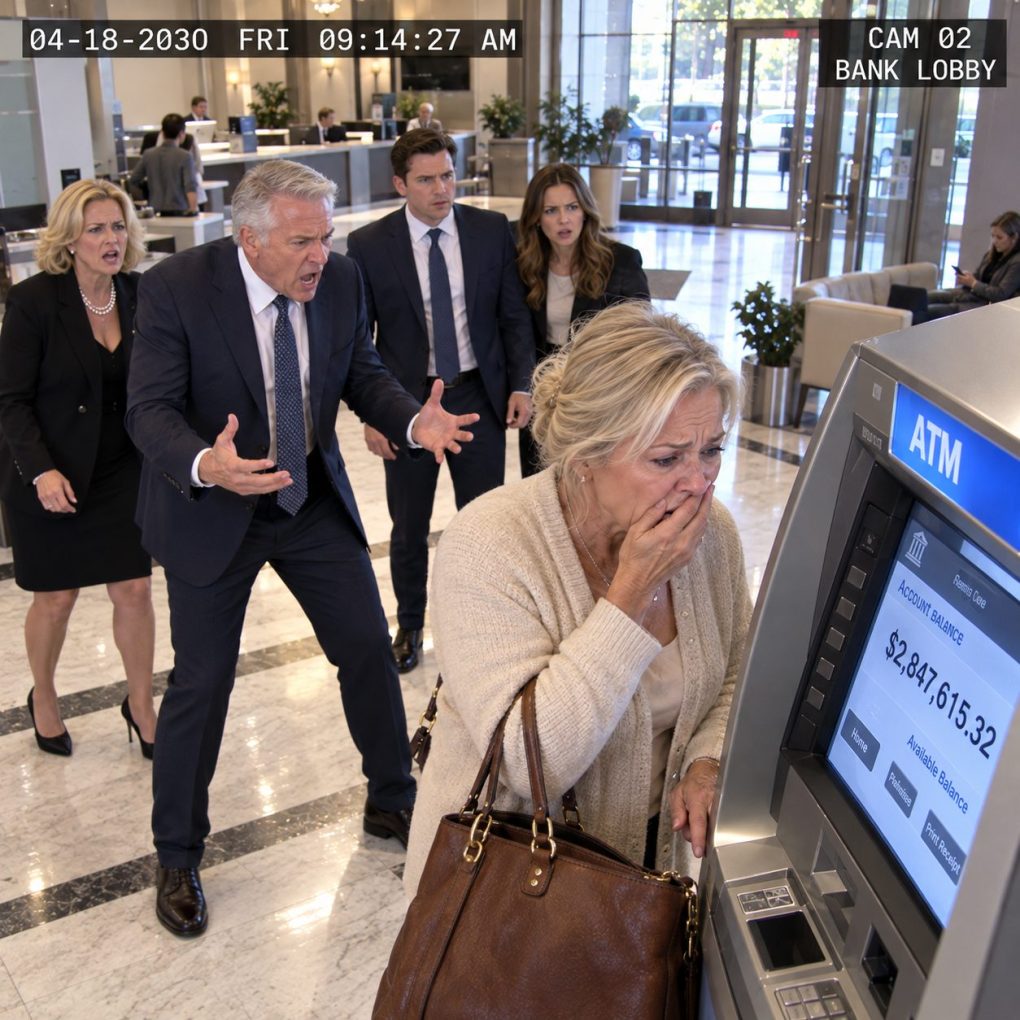
I inserted the card into the ATM.
Entered the PIN Richard had written on the back of the envelope.
Selected Balance Inquiry.
Then stared.
I read the number once.
Then again.
$1,184,327.42
My hands went cold.
I grabbed the machine for balance.
A woman waiting behind me asked if I was all right.
I barely heard her.
Three thousand dollars had not somehow become more than a million through ordinary interest.
Something else had happened.
I canceled the transaction, took the card, and drove straight home.
Before calling Richard, I called my divorce attorney.
Because one question was suddenly louder than the number itself.
Was that money actually mine?
My attorney, Laura Bennett, told me not to spend anything until we knew exactly what kind of account the card accessed. The physical card carried only the bank’s name and the last four digits. I sent her photographs, then called the bank with her guidance. Because my name appeared on the account, the representative confirmed I was an authorized owner, but detailed records required an in-person identity review.
The next morning, Laura went with me. The account had been opened two days after our divorce became final. Richard had deposited exactly $3,000 initially, just as he said. But every month afterward, additional deposits arrived automatically from an account linked to Hayes Commercial Flooring. Some months were $8,000. Some were $15,000. Several year-end transfers exceeded $100,000.
I stared at the statements. “Why would his company be paying me?” Laura asked the bank to identify the transfer descriptions. Most were labeled HCF Distribution — EH Interest. That phrase immediately concerned her because our divorce settlement had specifically awarded Richard all ownership interest in Hayes Commercial Flooring.
We pulled out my settlement documents. Buried in an exhibit describing business assets was a clause I had forgotten entirely. Before the divorce, Richard had transferred a small nonvoting profit interest into an irrevocable trust for my benefit. The agreement stated that the trust was not part of the marital division because Richard had funded it separately and I could not demand or control business decisions through it.
Laura remembered the provision once she saw it. She had advised me about it five years earlier, but its expected value had been modest. Richard’s company was stable then, not spectacular. The trust was projected to distribute only a few thousand dollars annually, and the card account had apparently been created as the destination for those payments.
What changed was the business. Three years after our divorce, Hayes Commercial Flooring won major hospital and municipal contracts throughout Illinois and Wisconsin. Revenues surged. Richard later sold a controlling stake to a private-equity group while retaining management rights. The trust’s profit interest participated in part of that transaction.
That explained the enormous deposits, but not why nobody told me. Laura contacted the trustee named in the agreement. The trustee had mailed annual statements to an address listed in the original trust file—our old marital home. Richard had remained there for two years before selling it. Afterward, the correspondence was returned, yet the bank account continued receiving distributions automatically.
I called Richard that evening. He answered after three rings. When I said, “I checked the card,” there was a long silence. Then he asked quietly, “How much is there now?” I told him. He exhaled as though he had known this conversation would eventually happen.
“Why didn’t you tell me?” I asked. Richard said he thought the trustee had. When I explained the statements never reached me, he sounded genuinely surprised. Then he admitted something more important: the trust had been deliberate from the beginning.
During the divorce, Richard knew I worried that keeping the company meant he would continue benefiting from decades of work while I received only fixed assets. Our settlement had been fair on paper, but he also knew I had supported the business when it was nothing more than two vans and a rented warehouse. The trust was his attempt to preserve a small share of future success without reopening ownership disputes.
I asked why he never explained it clearly on the courthouse steps. His answer sounded exactly like the man I had married. “Because if I had said, ‘I created a trust because you helped build my life,’ you would have cried, and then I would have cried, and I was trying very hard not to do that.”
For the first time in five years, I laughed while talking to my ex-husband. Then Laura interrupted the sentiment with the question that still mattered: before I touched a dollar, we needed to confirm the trust terms, tax history, and whether any distributions had been reported incorrectly.
The financial review took several weeks. The account was legitimate, the trust was valid, and the distributions belonged to me under its terms. Nothing had been hidden from the divorce court. The trust had been disclosed, reviewed by both attorneys, and signed as part of the final settlement package. My failure to remember its significance did not change its legal status.
Taxes were the next concern. The trustee had filed the necessary trust returns and issued annual tax documents, but several had been mailed to outdated addresses. Some income had already been taxed at the trust level; other distributions required corrections to my personal filings. My accountant prepared amended returns, and I paid what I owed without pretending the million-dollar balance was entirely spendable cash.
After everything was reconciled, I still had far more money than I had imagined. I replaced the furnace. I also repaired the condo roof assessment I had been postponing and increased the reserves in my retirement plan. What I did not do was buy a sports car, a mansion, or anything else that would have looked satisfying in a photograph but ridiculous in my actual life.
Richard and I met for coffee a month later. I brought the original envelope with the faded card instructions still inside. “Three thousand dollars?” I asked. He smiled. “That was true when I gave it to you.” I told him a warning about the trust might have been useful. He admitted communication had never been his strongest talent, which was one reason we had ended up divorced.
Then I asked the question that had bothered me most: was the trust guilt? Richard shook his head. “No. Recognition.” He reminded me that during the first decade of Hayes Commercial Flooring, I handled invoices at our kitchen table, answered customer calls while raising toddlers, and used my teaching savings to cover payroll during one bad winter.
None of that had made me an owner later, and I had never asked to become one. But Richard said he could not accept a future where the company became extraordinarily valuable while pretending its earliest years had belonged only to him. The nonvoting trust interest was designed to acknowledge that history without tying us together as business partners after divorce.
That explanation affected me more than the money. Divorce has a way of reducing decades into columns: property, retirement, debts, furniture. Our paperwork had accurately divided assets, but it could not fully describe the thousands of unpaid, ordinary acts that had allowed both of us to build the lives we eventually separated.
Our children were shocked when I finally told them. My son immediately joked that I was now the family millionaire. My daughter asked a better question: “Does this change how you feel about Dad?” I told her yes, but not in the way she meant. It did not make me regret the divorce. It simply reminded me that a marriage can end without every good thing inside it becoming false.
Richard and I never reconciled romantically. He eventually started seeing someone, and I was genuinely happy for him. I traveled more, volunteered at the library foundation, and established education accounts for my grandchildren. I also created my own estate plan because receiving unexpected wealth taught me how dangerous it is to assume someone else will eventually explain important paperwork.
The old debit card expired the following year. I kept it anyway. Not because it represented $1.18 million, but because it represented something I had misunderstood for five years. Richard had not handed me emergency charity outside the courthouse. He had handed me access to a financial structure meant to keep recognizing a contribution neither of us had known how to value precisely.
At sixty-five, the ATM balance made my knees buckle. But the number itself was not the part I remembered most. What stayed with me was realizing that after thirty-two years together and five years apart, Richard had found one final imperfect way to say something he had always struggled to express: You helped build this too.