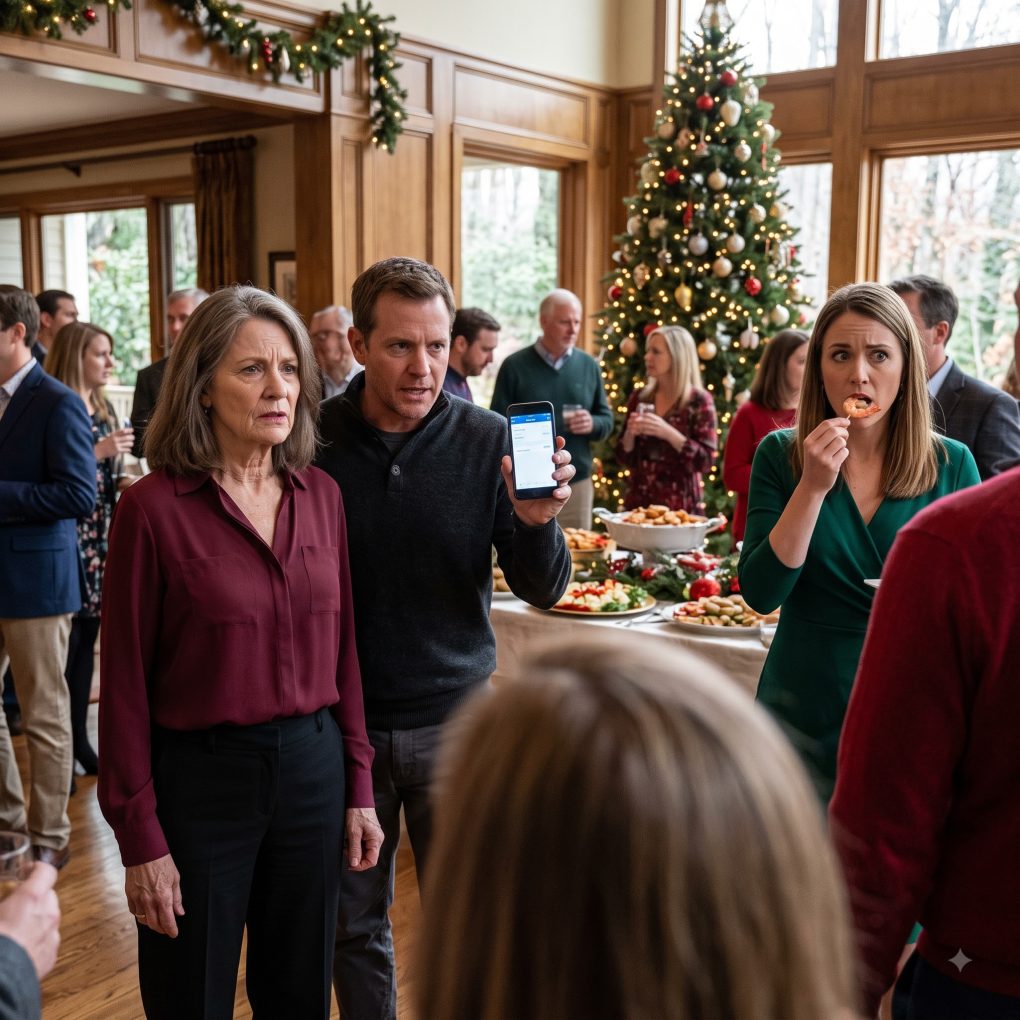
“Are you enjoying the five thousand I send you every month?”
Boyd slipped one arm around my shoulders as if he were asking whether I liked the Christmas ham.
I laughed.
Then I saw his face.
“Boyd, I work two jobs. I’ve never received a dollar.”
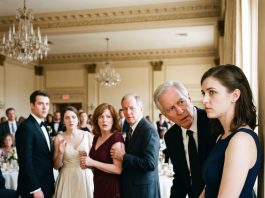
The room kept moving around us. Nearly forty people crowded my son’s house outside Raleigh, laughing beside the tree, balancing cocktails and paper plates while Christmas music drifted from the speakers.
Across the living room, my daughter-in-law, Edna, stopped with a shrimp halfway to her mouth.
Boyd’s arm slid from my shoulders.
“What do you mean, never?”
“I mean exactly that.”
He stared at me. “Mom, I’ve been sending you five thousand dollars every month for more than two years.”
My stomach tightened.
I was sixty-four. I worked mornings in a medical office and four evenings a week at a grocery store. Boyd knew I hated asking anyone for money, especially after his father died. I had turned down his offers more than once.
“That isn’t possible.”
“It’s automatic.”
“To where?”
He lowered his voice. “The account in your name.”
Edna put the shrimp back on her plate.
Then she walked toward us.
“What are you two whispering about?”
Boyd didn’t look away from me. “Mom says she hasn’t been getting the money.”
For one second, Edna’s expression disappeared completely.
Then she smiled.
“Oh. That.”
I felt something inside me go cold.
“What does ‘that’ mean?”
She glanced toward the guests. “Can we not do this in the middle of Christmas?”
Boyd already had his phone out.
He opened his banking app and showed me the recurring transfer.
$5,000.
Every month.
Recipient: ELEANOR J. WADE.
That was me.
The receiving bank was Carolina Commonwealth, an institution I had never used.
“How long?” I asked.
Boyd scrolled.
“Twenty-six months.”
I did the math without meaning to.
One hundred thirty thousand dollars.
My knees nearly weakened.
Edna touched my elbow. “Eleanor, there’s an explanation.”
I moved away from her.
Boyd opened an email attachment labeled PAYMENT INSTRUCTIONS.
“It came from you,” he said.
“No, it didn’t.”
The document showed my full name, a routing number, an account number, and what looked like my signature beneath authorization language.
I had never seen it.
Then I noticed the mailing address.
It wasn’t mine.
It was the condominium where Boyd and Edna had lived before buying this house.
Boyd saw it too.
“Edna?”
She went pale.
“I handled some paperwork for your mother after Walter died.”
“My husband died four years ago,” I said. “This account was opened two years later.”
Nobody spoke.
Boyd enlarged the signature.
I stared at the loop in the E, the sharp angle in the W, and remembered exactly where Edna had seen me sign my name dozens of times.
She had helped me organize Walter’s estate papers.
“Did you open a bank account using my identity?”
Edna set down her plate.
Then she grabbed Boyd’s phone and ran toward the hallway.
The Christmas party had gone silent around us, but the missing monthly payments were only the beginning. One document in Boyd’s office was about to make the secret account look almost harmless.
Boyd caught Edna before she reached the stairs.
“Give me the phone.”
She held it against her chest. “Not with everyone watching.”
“Then give it back.”
The music had ended. Conversations were thinning behind us. Boyd took the phone from her hand, led us into his home office, and shut the door.
Edna folded her arms.
“I was going to explain.”
“When?” I asked. “After another hundred and thirty thousand dollars?”
Her eyes flashed. “You weren’t supposed to know about the account.”
Boyd stared at her.
That sentence landed harder than anything else.
He sat behind his desk and searched old emails. Edna paced near the window.
“Mom refused every check I offered,” Boyd said. “You told me she finally agreed if I didn’t make a big deal about it.”
Edna said nothing.
“You gave me those banking instructions.”
“I was trying to help.”
“Who?”
She looked at me. “All of us.”
I called Carolina Commonwealth using the number on its official website. Because I couldn’t answer the online-banking security questions, the fraud representative wouldn’t discuss transactions. After I explained that an account appeared to have been opened in my name without permission, she froze access and told me to visit a branch with identification the next morning.
Then she asked whether I recognized the email address attached to the profile.
She read it aloud.
Boyd slowly looked at his wife.
It was Edna’s private email.
Edna sat down.
“I can fix this.”
“How?” Boyd asked.
“I can put it back.”
My heart pounded.
“So you took it.”
She covered her face.
Boyd opened another folder. “Where is the money?”
Edna wouldn’t answer.
Then he remembered something.
Six months earlier, she had claimed an aunt left her money. Soon afterward, Edna bought a two-bedroom townhouse near Lake Norman as an “investment.” Boyd had never seen inheritance papers.
He pulled up the county property search.
The townhouse was owned by EJM Holdings LLC.
Edna Joan Mercer.
My daughter-in-law.
Boyd turned the screen toward her.
“Did my money buy this?”
Edna started crying.
“Yes.”
Boyd leaned back as though she had struck him.
She claimed it had started as temporary. She planned to replace the money after selling the townhouse and close the false account before anyone discovered it.
But there had been twenty-six transfers.
“Why keep taking them?” I asked.
Her crying stopped.
“Because I needed somewhere to go.”
Boyd frowned. “Go where?”
Edna looked at the closed office door.
“I was leaving you.”
Silence.
The townhouse was supposed to become hers after she filed for divorce. The stolen payments had covered its down payment, mortgage, furnishings, and an emergency fund Boyd knew nothing about.
Boyd shook his head.
“That still isn’t a hundred and thirty thousand.”
Edna’s eyes dropped.
He opened the desk drawer and removed a folder.
“I found this last week.”
Inside was a personal-loan statement bearing my name.
Original amount: $42,000.
Remaining balance: $36,411.
I had never borrowed it.
The mailing address was mine.
The full account number matched the secret checking account.
I didn’t sleep that night.
At nine the next morning, Boyd drove me to a Carolina Commonwealth branch. I brought my driver’s license, Social Security card, copies of Walter’s estate documents, and the payment instructions Edna had sent him.
The bank’s fraud specialist confirmed enough to turn my fear into something solid.
The checking account had been opened online twenty-six months earlier in my name, but with Edna’s email address and phone number. The mailing address had initially been Boyd and Edna’s old condominium. Someone had uploaded an image of my driver’s license and information that matched my Social Security record.
I knew where she got both.
After Walter died, Edna had helped scan documents for the estate.
The bank froze the account and opened an investigation. I froze my credit with all three major bureaus and filed identity-theft reports. Boyd contacted his attorney and gave investigators every transfer record he had.
The $42,000 loan was the second reason Edna had created the account.
She had applied in my name months after Boyd began sending money. The proceeds landed in the same checking account before being transferred to EJM Holdings. The monthly deposits from Boyd made the account look active and gave Edna a place to receive money without using her own name.
By then, only $7,903 remained.
The rest had gone toward the Lake Norman townhouse, furnishings, loan payments, credit-card bills, and ordinary spending.
Edna moved out of Boyd’s house before New Year’s.
The legal part took months. The lender removed the fraudulent loan from my responsibility after reviewing the identity-theft documentation. Carolina Commonwealth closed the false account. Prosecutors later filed fraud and identity-theft charges based on the account, loan, and supporting records.
Recovering the money was slower.
Boyd’s attorney traced much of it into the townhouse. When the property was eventually sold during the financial settlement, funds were used to resolve claims connected to the stolen transfers. Boyd recovered a substantial portion, though not every dollar.
He apologized to me more times than I could count.
“I thought I was taking care of you.”
“You were trying to.”
“I should have asked you directly.”
“Yes,” I said. “You should have.”
That was the part neither of us could skip.
Edna had stolen the money, but secrecy had made the theft easy. Boyd assumed pride was the reason I never thanked him. I assumed my son was too busy to notice I worked seven days most weeks.
We had both let someone else speak between us.
Three months later, Boyd came into the grocery store near closing and watched me straighten canned soup.
“Mom, quit this job.”
I laughed. “You’re not my boss.”
“No. So I’m asking.”
This time, we went together to my credit union. No secret account. No intermediary. No forged instructions.
I agreed to let him help with enough each month that I could finally give up the evening shifts.
The following Christmas, Boyd handed me a small envelope.
Inside was a bank statement from my real account and a handwritten note.
ASK MOM. DON’T ASSUME.
I looked across the room.
He smiled.
Then he asked, “Did the money arrive?”
I checked my phone.
“Yes.”
For the first time, it actually had.