My daughter threatened me, “Either put my name on the property deed, or I’m calling the police!” I looked at her calmly and replied, “Go ahead.” She was convinced the officers would force me to sign over part of my property. But when the police arrived, her plan backfired in a way she never expected…
My daughter Lauren slammed a property deed onto my kitchen table and pointed to the blank space beside my name. “Either put my name on the deed, or I’m calling the police!” I was sixty-nine years old, standing in the house my late husband and I had paid for over thirty years. “Go ahead,” I said. She actually dialed. “My mother is confused and refusing to cooperate,” she told the dispatcher. “I need officers here before she does something reckless.” My name is Evelyn Reed, and I had spent my whole adult life believing my daughter would never use my trust against me. Now I could barely recognize her.
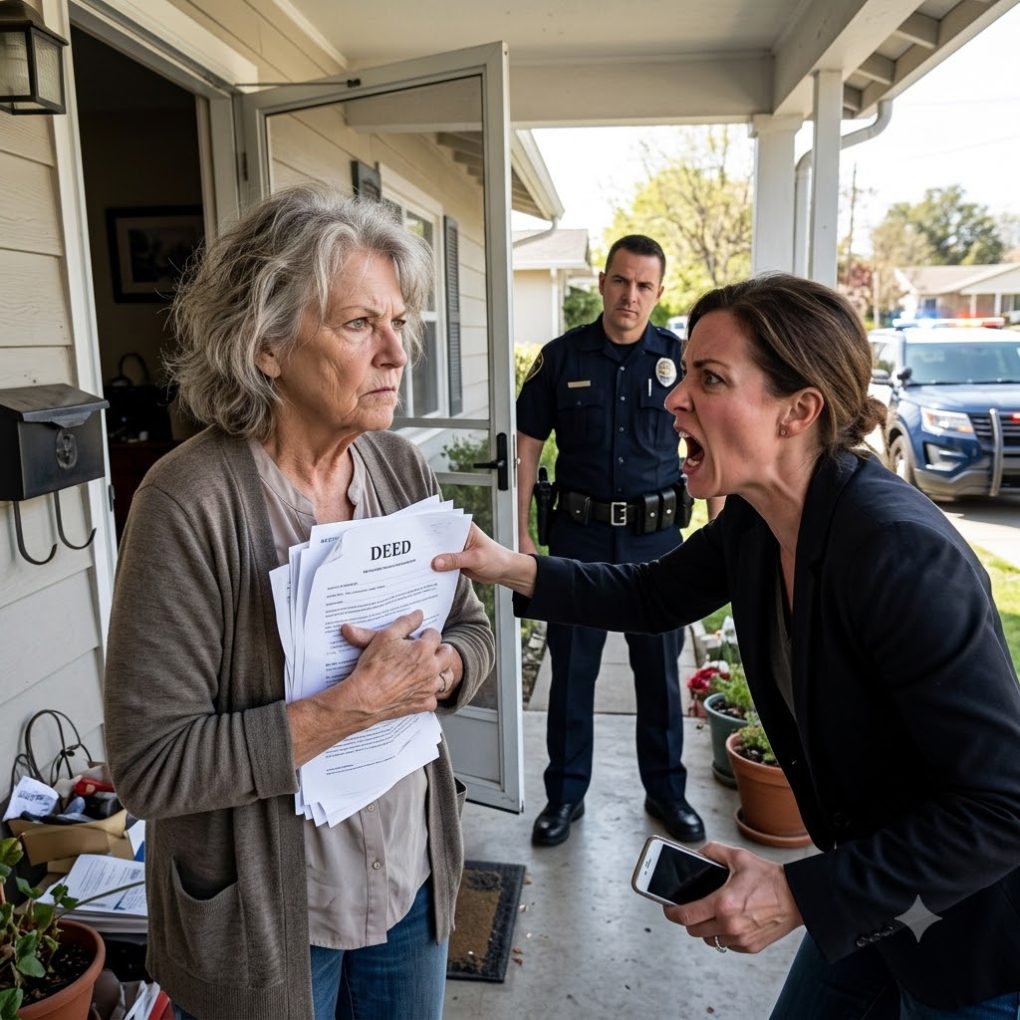
When two officers arrived at my home outside Columbus, Ohio, Lauren met them at the door. She spoke rapidly, insisting that I was becoming forgetful and that adding her name to the property would protect me. Then she made her real demand. “Tell her she has to sign. I’m her only daughter.” Officer Maya Torres looked at me. “Ma’am, do you want to transfer an interest in your house?” “No.” “Then no one here can make you.” Lauren’s face turned crimson. “She doesn’t understand! I’ve already arranged everything with the bank!” That was the first I’d heard about a bank.
Officer Torres asked what arrangements she meant. Lauren dug through her handbag and produced a folder. Inside was an application for a home-equity loan and an authorization letter bearing what appeared to be my signature. “I never signed this,” I said. Lauren lunged toward the papers. “Mom, stop lying!” The second officer stepped between us. “Please keep your distance.” Officer Torres examined the letter. “Lauren, did your mother authorize this application?” “She was supposed to. She kept changing her mind.” “That isn’t what I asked.” My daughter stared at the floor. I recognized the bank’s name but not the handwriting beneath mine. Then I spotted the amount on the application: ninety-two thousand dollars. My stomach dropped.
“Why would you borrow against my house?” I asked. Lauren’s voice broke into a shout. “Because you have a paid-off house while I’m drowning in bills! You could help me, and you won’t!” Officer Torres set the folder on the table. “We’ll need to document the disputed signature and speak with the lender. For now, nobody is signing anything.” Lauren looked from the officers to me, suddenly pale. “You called them to make me give you my house,” I said quietly. “Instead, you’ve shown them what you tried to do behind my back.”
The officers separated us while they took statements. Lauren paced my hallway, muttering that everyone was overreacting. I sat in the dining room with Officer Torres and explained that I had never applied for a loan, never given Lauren authority to act for me, and had no intention of adding her to the deed. “Does she have access to your records?” the officer asked. “She used to have an emergency key. And last month she offered to organize my paperwork while I recovered from pneumonia.” I remembered how grateful I’d been when Lauren brought groceries and sorted the overflowing drawer in my desk. Among those papers were my property-tax bills, insurance statements, and a photocopy of the deed. I’d trusted her because she was my daughter. Now I understood why she had been so interested in documents I’d never asked her to touch.
Officer Torres photographed the letter with my permission and gave me an incident number. She explained that the disputed signature would need further investigation; the officers couldn’t decide a forgery case in my kitchen. But they could make clear that Lauren had no authority to remove me or compel a transfer. When Lauren was asked to leave, she turned to me. “If you loved me, you’d stop this.” “I loved you before you needed money,” I answered. “I’ll love you afterward. But I won’t sign.”
The next morning, I called the lender’s fraud department using the number on its official website. The representative confirmed that an application had been submitted naming my house as proposed collateral. No loan had been approved, and the lender had requested direct verification from me as the legal owner. I disputed the application and asked for written confirmation that it would not proceed without my authorization. Then I called my attorney, Helen Grant. She checked the county property records and confirmed that the deed still showed me as sole owner. She helped me prepare a written notice that Lauren was not authorized to act for me in property matters. I changed the locks, updated my emergency contacts, and secured my financial documents.
Three days later, Lauren called from an unfamiliar number. This time she wasn’t shouting. “I owe money,” she whispered. “More than I told you.” “How much?” “Almost eighty thousand. Credit cards, a business loan, interest. I thought if I could get the money from the house, I could fix everything before you found out.” “And the signature?” A long silence followed. “I copied it from an old check,” she admitted. I closed my eyes. Hearing her confess hurt more than seeing the document. She hadn’t made one impulsive threat. She had planned the loan, used my records, and forged my name. The police call was supposed to be the final pressure that made me cooperate. “Lauren,” I said, “you need a lawyer and a plan to face your debts. You cannot solve them by stealing my signature.” She began to cry, but I did not take back my words.
Over the following weeks, a detective contacted me about the authorization letter. I provided the documents my attorney had collected, along with the messages Lauren had sent demanding a share of the house. The lender confirmed that it had halted the application once my lack of consent became clear. Whether any criminal charges would follow was for investigators and prosecutors to decide. I refused to speculate, but I was no longer willing to hide what had happened. My neighbors noticed the new locks, and one asked whether I was selling. “No,” I told him. “I’m finally making sure the house stays mine.”
That house wasn’t simply an investment. My husband, Robert, and I had skipped vacations and driven aging cars to pay off the mortgage early. He had planted the maple tree beside the front steps. After he died, I’d kept the home because every room held a piece of our life together. Lauren had grown up there. Perhaps that familiarity had convinced her that loving a house meant owning it. A month after the police visit, she wrote me a letter. There were no demands this time. She said she had met with a debt counselor, spoken to an attorney, and started negotiating repayment terms with her creditors. She also admitted that she had told herself the loan would be temporary, even though she had no realistic way to repay ninety-two thousand dollars.
“I kept saying I was protecting my future,” she wrote. “I was willing to take yours.” I read that sentence several times. It was the first thing she had said that suggested she understood the harm. We met in a public café two weeks later. Lauren looked tired. She placed her phone face down and asked how I was doing before mentioning her own problems. I told her I missed our Sunday dinners and the easy conversations we once had, but I could not pretend trust returned just because she apologized. “I know,” she said. “What happens now?” “We start with the truth,” I answered. “You handle your debts. You cooperate with the investigation. And you don’t touch my financial affairs again.” She nodded without bargaining. That was new.
I never transferred the deed. My attorney helped me review my estate plan, including how I wanted my property handled after my death. I made those decisions privately and without threats hanging over me. One Sunday evening, months later, Lauren called simply to ask whether I wanted company for dinner. She didn’t mention money. I said she could come, and we ate soup at the kitchen table where she had once slammed down the deed. The relationship wasn’t repaired in one meal. But when she left, she thanked me for having her, not for giving her something. The day she called the police, Lauren believed their uniforms would make me surrender my home. Instead, those officers reminded us both of a truth she had forgotten: being someone’s child does not make you the owner of their life.